Metaplanet sold Bitcoin to demonstrate liquidity to creditors
Corporate Bitcoin treasuries are discovering that holding vast coin reserves requires constant cash management to service debt and maintain financing access. This trend reshapes how investors should evaluate whether accumulation announcements reflect sustainable strategy or temporary market conditions.
- Metaplanet sold 10,000 BTC and repurchased 11,000 at roughly 9.3% higher per-coin cost to demonstrate asset liquidity to creditors pursuing a credit rating.
- Strategy held 848,000 BTC as of October 4 alongside $4.88 billion in a dedicated reserve and $833.4 million in separate cash to cover debt service.
- Corporate Bitcoin holdings now face competing demands: creditors need cash repayment certainty on fixed schedules, while shareholders expect indefinite accumulation of volatile assets.
- ¥11.57B Price difference Metaplanet paid on 10,000-coin replacement versus sale proceeds
- $5.71B Strategy’s combined dedicated reserve and separate cash as of October 4
- ¥75.49B Metaplanet’s short-term borrowings and near-term bonds versus ¥1.34B in liquid cash
- $5.91B Principal of Strategy’s convertible notes with holder repurchase rights during 2027 to 2028
Corporate Bitcoin treasuries are facing a structural tension between asset accumulation and debt service that forces difficult trade-offs, according to CryptoSlate reporting. Metaplanet, a Japanese treasury company, demonstrated the problem in October by selling 10,000 BTC and immediately repurchasing 11,000 at a higher average price, absorbing a ¥11.57 billion loss on the round trip. The sale was designed to convince creditors assessing a potential credit rating that management could convert Bitcoin holdings into cash to meet obligations, even though the company’s stated strategy centers on long-term accumulation.
Selling Bitcoin to prove it could be sold
Metaplanet received ¥124.7 billion from its sale and spent ¥149.9 billion on the subsequent purchase, paying roughly 9.3% more per coin. The company disclosed this activity on October 5 in a filing explaining why the swap was necessary to access better financing terms and demonstrate balance-sheet credibility. Creditors need assurance that management retains the practical ability to service debt, even if shareholders hold the company specifically because of its Bitcoin reserve.
The swap proved expensive before accounting for transaction costs and potential tax effects.
Cash gaps force competing priorities between debt and accumulation
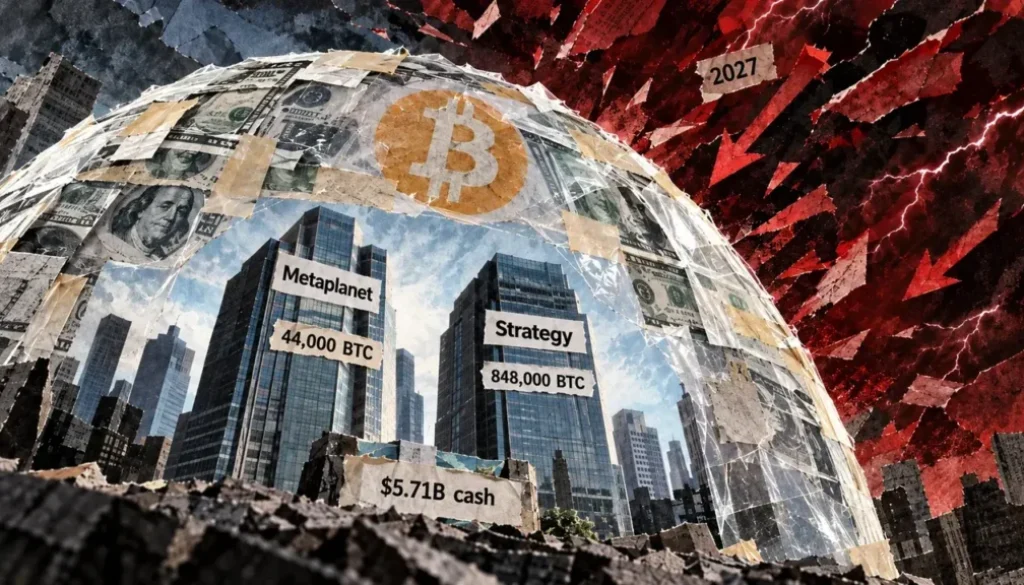
Metaplanet’s June financial statement, filed with Japanese regulators, revealed why creditors demanded proof of asset liquidity. As of June 30, the company held ¥1.09 billion in cash and deposits and ¥250 million in USDC against ¥67.49 billion in short-term borrowings and ¥8 billion in bonds payable within a year. The gap between liquid reserves and near-term debt obligations meant the company’s much larger Bitcoin reserve, which stood at 44,000 BTC by September 30, could not be treated as reliable collateral without management demonstrating a willingness to sell.
Strategy, the U.S.-listed Bitcoin treasury company, has built a larger cash cushion to manage similar pressures. Its October 5 filing with the SEC reported a $4.88 billion dedicated reserve designated for preferred-stock dividends and debt interest, plus a separate $833.4 million in dollar-denominated cash, totaling approximately $5.71 billion as of October 4. Strategy held 848,000 BTC at that date, purchased for approximately $63.97 billion, so Bitcoin dominated its balance sheet by a large margin.
Financing deadlines create selling pressure independent of Bitcoin’s price
Strategy faces specific repayment obligations that turn abstract balance-sheet concerns into concrete deadlines. Holders of $1.01 billion in convertible notes can request cash repurchase on September 15, 2027, and similar note holders possess rights to demand repayment of approximately $4.9 billion during 2028. While those holders must exercise their rights and conversions could reduce actual obligations, the company has clear points when access to cash matters more than confidence in Bitcoin’s eventual appreciation.
Between September 28 and October 4 alone, Strategy used $142.5 million from its reserve for dividends and interest, spent $154.1 million repurchasing preferred shares, and bought $13 million of Bitcoin. The cash balance provides breathing room when payments come due, helping the company avoid selling coins simply because market conditions have turned unfavorable. Metaplanet’s experience shows that if cash reserves prove inadequate, management faces the choice between selling Bitcoin at inconvenient prices, issuing shares at a discount to existing holders, or seeking expensive additional financing.
Neither company’s disclosures indicate an imminent forced liquidation, but both demonstrate how financing obligations reshape purchase decisions.
Income-producing investments create new risks for treasury companies
Metaplanet’s revised allocation policy targets roughly 85 to 90 percent of assets in Bitcoin and 10 to 15 percent in strategic investments, including income-producing securities. The company is pursuing what it calls a Net Interest Income Strategy, seeking to earn more from those investments than it pays to finance them. Possible investments include preferred securities issued by other Bitcoin treasury companies, meaning one company’s plan to generate cash for debt service could depend on collecting payments from another company facing similar balance-sheet pressures.
This arrangement creates the possibility of exposure to the same weakness twice: falling Bitcoin prices could reduce Metaplanet’s core asset value while simultaneously reducing the value or reliability of securities issued by other treasury companies. The policy acknowledges potential correlation between these risks, but the actual danger depends on what specific investments the company makes and how it finances those positions. It demonstrates how far corporate Bitcoin strategy can drift from the simple proposition of holding coins until they appreciate.
The BlockWest read. We do not see imminent defaults or forced liquidations, but we read Strategy’s cash cushion and Metaplanet’s expensive swap as evidence that accumulation announcements now signal temporary market appetite, not structural strategy. Management flexibility on selling may ultimately benefit shareholders more than adherence to a never-sell pledge financed through expensive borrowing or excessive share dilution.
Metaplanet’s round trip still must earn its keep through better credit access or more favorable borrowing terms, since the October disclosure does not confirm whether a rating agency ordered the sale or whether cheaper financing has been secured. Strategy’s next material test arrives September 15, 2027, when holders of $1.01 billion in notes gain the right to demand cash repurchase, forcing the company to demonstrate whether its current reserve provides sufficient flexibility or whether market conditions have tightened financing access before that deadline.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.