Strategy Increases Stock Repurchase Program to $2 Billion in Effort to Restore STRC Shares to $100
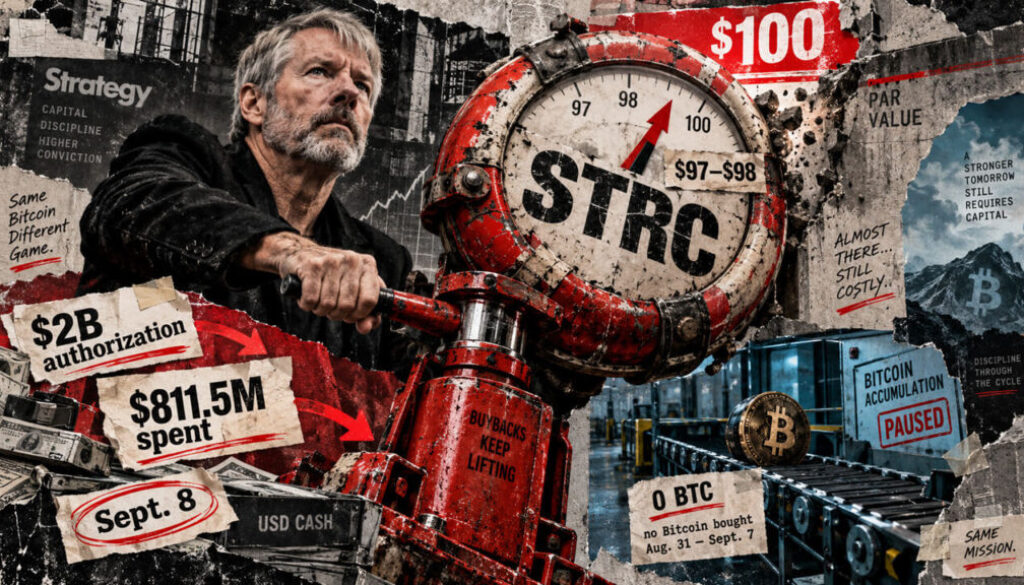
Strategy has doubled its preferred-stock buyback authorization to $2 billion as STRC shares remain short of their $100 stated value, signaling the company is willing to commit additional balance-sheet resources to restore the security to par. The move reveals how STRC’s recovery has consumed capital faster than initially planned, forcing the company to choose between supporting its flagship preferred product and expanding its Bitcoin holdings.
- Strategy increased STRC repurchase authorization from $1 billion to $2 billion on Tuesday as the preferred traded around $97 to $98, roughly 2% below par.
- Between August 31 and September 7, Strategy acquired 1.81 million STRC shares for $176.3 million at an average price of $97.36, the largest weekly purchase to date.
- The company has now spent approximately $811.5 million of its original $1 billion authorization in seven weeks, with cumulative spending leaving roughly $188.5 million remaining before the increase.
- $2B New total repurchase authorization, doubled from prior $1 billion program
- $811.5M Cumulative STRC buyback spending since July through September 7
- $97.36 Average price paid per share in latest week versus $100 par value
- 845,050 Bitcoin holdings as of September 7 at $63.73 billion acquisition cost
Strategy has expanded its preferred-stock repurchase program as its campaign to restore STRC shares to $100 par value accelerated far beyond its original spending plan. The board’s decision to double the authorization to $2 billion arrived as STRC traded at $97 to $98, just shy of the $100 stated value that marks the security’s operational threshold. The increase reflects how quickly the company’s buyback effort has consumed available capital, with roughly 81% of the original $1 billion authorization deployed in seven weeks of progressively larger purchases.
Preferred-stock buyback programs traditionally serve to manage capital structure and support security valuations during temporary market dislocations. Strategy’s deployment represents an unusually aggressive commitment, driven by the specific mechanics of STRC’s dividend structure and its role within the company’s capital framework. Unlike common equity buybacks, which reduce share count and increase per-share metrics, preferred-stock retirements directly reduce the company’s preferred capital and associated fixed dividend obligations.
Buyback spending accelerates as discount narrows
Strategy’s repurchase activity has moved in the opposite direction from management’s initial framework. The company had planned to purchase more aggressively when STRC traded well below $100, where each share retired at a discount removed $100 of preferred capital along with associated dividend obligations. As the discount narrowed, Strategy intended to reduce its presence and allow outside market demand to support the price. Instead, weekly purchases have grown from $25 million in the opening week to $176.3 million in the most recent reporting period.
STRC had fallen to near $71 before the buyback campaign began in late July. Strategy spent $25 million in the first week at an average price of $86.52, then increased weekly purchases to $81.2 million, $108.6 million, $132.2 million, $136.4 million, and $151.8 million as the preferred climbed closer to par. The latest $176.3 million purchase between August 31 and September 7 represents the largest deployment yet, despite the discount collapsing from more than 13% in the opening week to less than 3% currently.
The spending reversal illustrates how the mathematics of STRC support change as the security approaches par. Each dollar spent buying shares at $97.36 delivers substantially less capital relief than purchases made at $71 or $86, yet Strategy has found it necessary to spend more to reach the price target. This counterintuitive pattern reflects how preferred-stock markets behave near their stated values, where psychological and mechanical support factors become more powerful than simple discount economics.
Bitcoin accumulation halts when STRC buybacks draw from cash reserves
The expanded repurchase program has forced Strategy to pause Bitcoin purchases after a brief resumption one week prior. During the week ending August 30, Strategy raised $602.8 million through common-stock sales, spent $151.8 million on STRC buybacks, and still directed $369.7 million toward acquiring 4,603 Bitcoin. That sequence suggested the company could fund both its preferred-stock obligations and expand its core asset holdings simultaneously.
The pattern reversed in the most recent week. Strategy completed no share sales through its at-the-market program between August 31 and September 7 and purchased no Bitcoin, directing the entire $176.3 million STRC repurchase from its USD Cash balance. The company held $1.44 billion in cash and $5.10 billion in its separate USD Reserve at period-end. Strategy designates the cash pool for Bitcoin acquisition, reserve increases, capital structure management, and other treasury purposes, while the reserve exists to support preferred-stock dividends and debt service.
The distinction reveals how STRC’s accelerating buyback needs compete directly with Bitcoin expansion within Strategy’s capital allocation. Without fresh equity issuance, the company must choose whether to retire preferred shares or acquire more Bitcoin. This tradeoff represents a fundamental tension in Strategy’s business model, where Bitcoin accumulation drives long-term value creation while preferred-stock support maintains the current capital structure and investor confidence in its flagship security.
Path to par depends on sustained Capital deployment
Strategy has strong incentive to restore STRC to $100 par because the security becomes operationally useful only at that price level. STRC was designed as a perpetual funding vehicle whose variable dividend adjusts to encourage market price stability around par. The company adopted a policy against issuing additional STRC below par, meaning the preferred cannot serve its intended financing role while trading at a discount. A sustained return to par would reopen that capital channel and reduce reliance on common-stock sales.
STRC’s initial 2025 offering demonstrates the scale of capital the preferred can access. The offering expanded from an expected 5 million shares to more than 28 million following strong investor demand, ultimately raising approximately $2.52 billion. The security has since grown to a market value of roughly $10 billion, making it Strategy’s flagship preferred product. Restoring it to issuance territory would significantly enhance the company’s capital-raising flexibility and reduce execution risk in future financing efforts.
Preferred-stock investors value par restoration because it signals management confidence and validates the security’s fundamental credit quality. Strategy’s willingness to commit additional capital sends a message about underlying asset values and the company’s ability to support its obligations. The timing also reflects competitive pressures within the preferred market, where multiple issuers compete for investor capital and execution ability determines future funding access.
September 8 served as an informal milestone after Michael Saylor compared STRC’s recovery trajectory to the roughly 70 trading days the security initially required to climb from its $90 offering price to $100, though the date was never a contractual deadline. The board’s decision to double the repurchase authorization indicates the final stage of recovery may require substantially more balance-sheet support than initially anticipated. The next critical test is whether Strategy must deploy a significant portion of the additional $1.19 billion authorization before outside market demand can hold STRC at par, or whether the expanded program signals sufficient confidence that par can be reached and sustained without consuming the full new ceiling.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.