Stifel and Mizuho raise AMD price targets above $700 on AI chip strength
Two major Wall Street firms have raised their price targets on Advanced Micro Devices to $700 and above, betting the chipmaker’s AI business will keep expanding ahead of its next earnings report. The upgrades reflect growing confidence that AMD is closing the gap with Nvidia in the data center AI chip race.
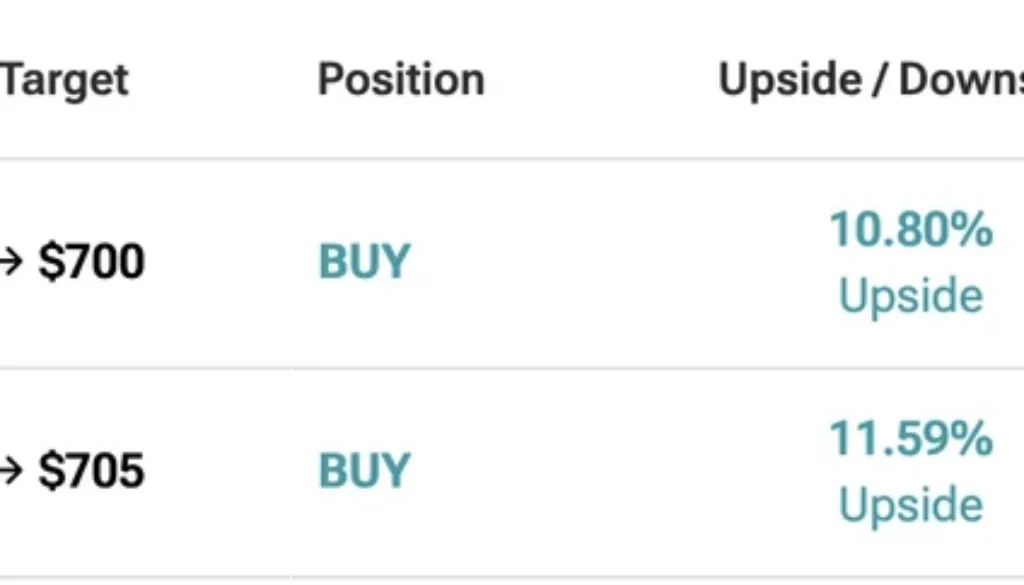
- Stifel Nicolaus analyst Ruben Roy raised his AMD price target from $635 to $700, a 10.80% upside from current levels
- Mizuho Securities analyst Vijay Rakesh lifted his target from $580 to $705, implying roughly 11.60% upside
- AMD reports third-quarter earnings on November 3, 2026, with investors watching Helios chip sales for signs of data center strength
- $700 Stifel’s new AMD target, up from $635 previously
- $705 Mizuho’s new target, its highest estimate yet for AMD
- 11.60% upside Mizuho sees versus AMD’s current share price
- Nov 3 date AMD reports Q3 2026 earnings results
Advanced Micro Devices has drawn fresh bullish calls from two Wall Street firms, with analysts pointing to the company’s position as the primary challenger to Nvidia in artificial intelligence chips. According to reporting by Watcher Guru, Stifel Nicolaus analyst Ruben Roy raised his price target on AMD from $635 to $700, representing an upside of 10.80% from current trading levels. Mizuho Securities analyst Vijay Rakesh went further, lifting his target from $580 to $705, an implied gain of about 11.60%.
Stifel and Mizuho both push targets above $700
The two targets, now separated by just $5, mark a sharp jump from where each firm stood previously. Roy’s prior target of $635 and Rakesh’s prior figure of $580 both predate the latest round of AI-driven optimism around AMD’s chip roadmap.
AMD has been among the stronger performers in the semiconductor sector over the past year, with the artificial intelligence buildout cited by both analysts as a central driver. The company is widely viewed as the only direct competitor capable of challenging Nvidia’s dominance in AI accelerators, even as other chipmakers including Intel remain in the market. Current Wall Street consensus data compiled by TipRanks shows a broader analyst community that has largely tracked in the same bullish direction as Roy and Rakesh.
AMD’s data center unit stays the focus ahead of November 3
AMD’s data center business has become one of its most significant revenue sources, driven by enterprise demand for AI model training infrastructure. Analysts expect that segment to remain the company’s top earner when AMD reports third-quarter results on November 3, 2026.
Investor attention is centered on AMD’s Helios chip line, with many anticipating strong sales figures to show up in the upcoming report. Roy and Rakesh appear to be positioning their targets ahead of that print rather than reacting to it.
More analysts could follow before the Q3 report lands
With two major firms raising targets in quick succession, additional Wall Street analysts may issue similar revisions before AMD’s November 3 earnings date. The pattern echoes how analyst sentiment has shifted around AMD at prior points in its competition with Nvidia for AI data center share.
The BlockWest read. We see this less as a verdict on AMD’s quarter and more as a positioning trade. Analysts raising targets before results land are effectively wagering on data center guidance, not confirmed numbers. For allocators, the real signal arrives November 3 when Helios sales either validate these targets or expose them as premature.
AMD is scheduled to release its third-quarter 2026 financial results on November 3, when Helios chip revenue and data center performance will test whether the Stifel and Mizuho targets hold up.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.