France approves 31.4% tax on regulated stablecoin conversions from January 2027
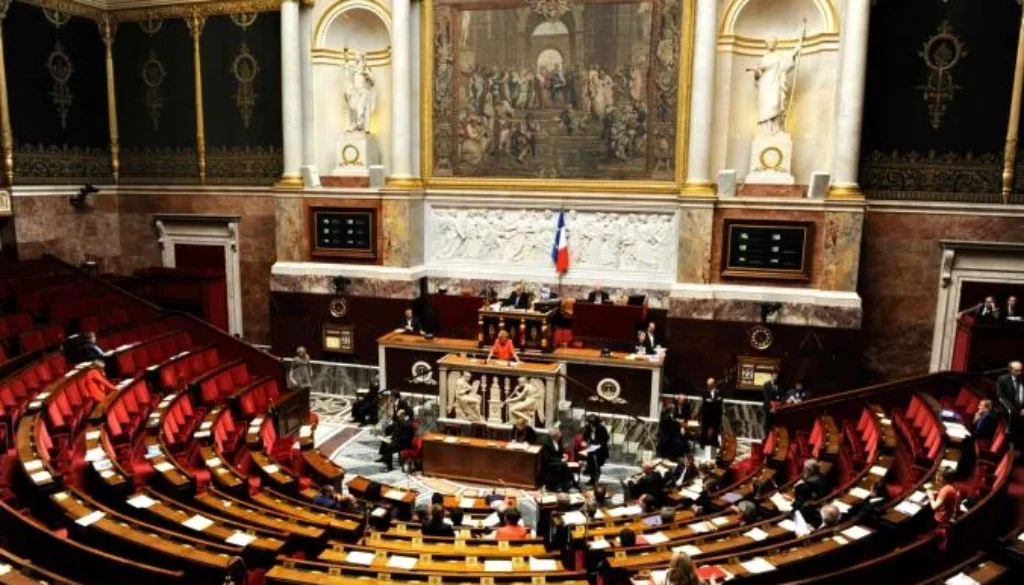
France’s lawmakers are advancing a tax framework that would treat conversions to regulated stablecoins as taxable events, potentially reshaping crypto trading behavior across the EU. The proposal highlights an emerging tension between regulatory compliance and tax avoidance, as policymakers attempt to widen their tax base while inadvertently creating incentives to use less transparent alternatives.
- France’s finance committee approved an amendment on October 7 taxing swaps from cryptocurrencies into EU-regulated stablecoins at 31.4% beginning January 1, 2027.
- A second amendment approved October 9 would require disclosure of self-hosted wallets holding €100,000 or more, with fines up to $11,600 for non-compliance.
- The full National Assembly must resubmit and vote on these measures by October 20, as the finance committee rejected the revenue section of the 2027 budget 31 votes to 3.
- 31.4% France’s capital gains tax rate on crypto transactions
- €100,000 Minimum wallet size requiring disclosure to French tax authorities
- 33 Physical attacks on crypto holders in France through July 2026
- 10% Capital gains tax Greece is preparing to impose on crypto
France’s National Assembly is advancing a series of cryptocurrency tax measures as part of the country’s 2027 budget deliberations, according to reporting by CoinDesk. The most significant proposal would classify conversions from cryptocurrencies into stablecoins regulated under the European Union’s Markets in Crypto-Assets (MiCA) framework as taxable events, subjecting them to France’s standard 31.4% capital gains rate starting January 1, 2027. Currently, swapping one cryptocurrency for another does not trigger capital gains tax in France, and the measure would specifically target so-called electronic money tokens that fall under MiCA’s scope following the regulation’s full implementation on July 1.
Regulated stablecoins face targeted tax treatment starting 2027
The amendment, adopted by the National Assembly’s finance committee on October 7, creates a narrow but significant distinction in how France treats digital asset conversions. By taxing only swaps into EU-regulated stablecoins and not other cryptocurrency-to-cryptocurrency trades, the framework effectively penalizes the use of compliant financial instruments while leaving unregulated alternatives untaxed.
Francois Volpoet, Chainalysis’ CEO for France, cautioned that the approach risks undermining regulatory objectives. “Do we want more taxpayers to declare their assets, or a higher tax rate applied to a base that is increasingly evaded?” he said in comments to CoinDesk. Volpoet noted that authorities can more readily track regulated stablecoin transactions than trades conducted through decentralized finance platforms or self-hosted wallets, suggesting that the tax structure may inadvertently incentivize traders to migrate toward less transparent channels.
Disclosure requirements and physical security concerns
A second amendment approved on October 9 mandates that French taxpayers disclose self-hosted cryptocurrency wallets holding at least €100,000 in assets, with penalties of up to $11,600 for violations.
Volpoet raised security objections to the disclosure mandate, pointing to a sharp rise in physical attacks targeting cryptocurrency holders in France. Through July 2026, Europe experienced 39 of 52 recorded global incidents of this type, with France alone accounting for 33 attacks or 63.5% of the worldwide total. The concentration of attacks in France underscores potential risks associated with mandated asset disclosure, as public records of large holdings could make individuals targets for theft or coercion.
The legislative package also includes an amendment adopted October 7 that would allow investors to carry forward cryptocurrency losses for up to 10 years, aligning the tax treatment of digital assets more closely with equities. A separate measure would extend France’s exit tax, which applies to wealthy individuals relocating abroad, to cryptocurrency holdings worth approximately $900,000.
Budget deadlock forces resubmission to full assembly
The finance committee rejected the revenue section of the government’s 2027 budget by a vote of 31 to 3, requiring all crypto-related amendments to be resubmitted to the full National Assembly for debate.
Lawmakers are scheduled to vote on the revenue section on October 20 (Tuesday). None of the proposed measures have become law. The outcome remains uncertain, as the broad rejection of the budget’s revenue framework suggests deeper fiscal disagreements that could reshape or eliminate individual provisions during full assembly proceedings.
France’s push for expanded crypto taxation contrasts sharply with regulatory approaches elsewhere in the EU. Greece is preparing to impose a 10% capital gains tax on cryptocurrency, making it among the bloc’s lowest-taxed jurisdictions on digital assets. Germany, Italy, and France are all setting or planning capital gains rates exceeding 25%, fragmenting the EU’s tax treatment of crypto across member states.
The BlockWest read. The proposals reveal a fundamental mismatch in regulatory design: lawmakers want both compliance and revenue, but the tax structure punishes compliance. If traders migrate to unregulated stablecoins and DeFi to avoid the 31.4% rate, France’s tax base shrinks while regulatory visibility into the market declines. The real cost is not the rate itself but the incentive structure it creates.
The October 20 (Tuesday) full assembly vote on the revenue section will determine whether these amendments advance to law or face further revision. France’s National Assembly must pass the entire 2027 budget by December 10, leaving narrow time for negotiation if the current measures face rejection or substantial amendments during plenary debate.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.