Canadian banks receive exemption from cross-exchange cryptocurrency hedge requirements in upcoming 2027 capital regulations
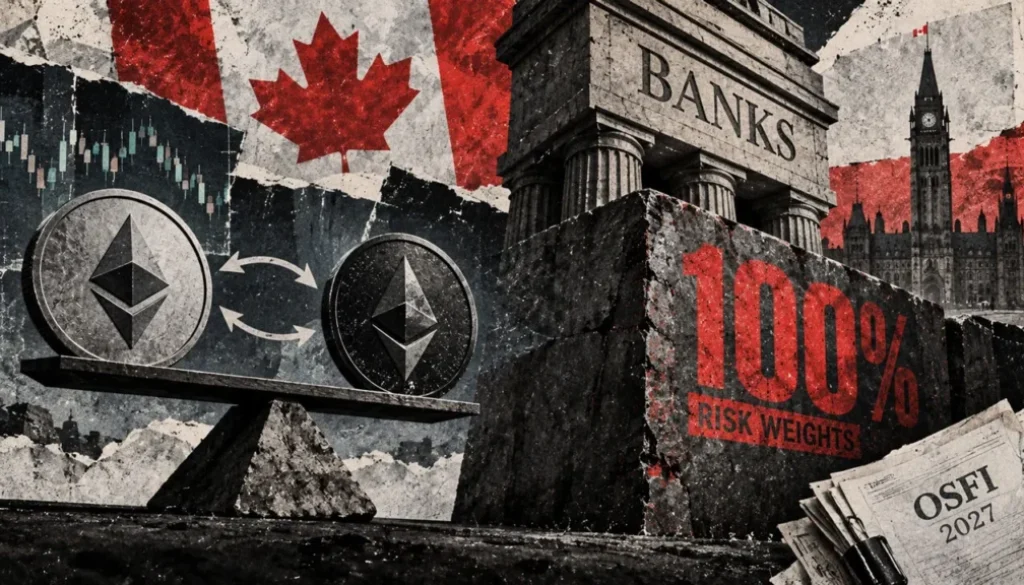
Canada’s banking regulator has narrowed a technical relief for crypto positions held across multiple exchanges, allowing banks to net certain market-neutral trades without broadly easing capital requirements on digital assets. The change addresses how banks calculate risk for qualifying crypto exposures but preserves strict treatment for non-qualifying positions and maintains an aggregate exposure ceiling.
- OSFI treats all regulated exchanges as a single venue for delta-risk calculation on Group 2a crypto exposures effective Nov. 1, 2026
- Relief applies only to positions meeting hedging-recognition tests including product structure, regulatory approval, liquidity and data-history conditions
- Unregulated exchanges receive no cross-exchange recognition, and Group 2b assets face substantially stricter deduction requirements from capital
- 94% Correlation parameter for delta and vega capital calculations within Group 2a crypto buckets
- 100% Risk weight applied to delta and vega for all Group 2a crypto exposures
- 5% Aggregate gross exposure limit for Group 2 crypto assets as percentage of Net Tier 1 capital
- Nov. 1, 2026 Guideline effective date for institutions with October 31 fiscal year-end
The Office of the Superintendent of Financial Institutions finalized amendments to its 2027 crypto capital guideline on September 10, introducing a targeted adjustment to how Canadian banks calculate hedging relief for digital-asset positions. The change permits banks to treat all regulated exchanges of traditional financial assets as a single exchange when computing delta risk for qualifying Group 2a crypto exposures, allowing positions in the same asset across different exchanges to receive full capital recognition if they share the same maturity date. The modification addresses a specific gap between real-world trading practice and regulatory capital calculations without fundamentally altering Canada’s conservative approach to crypto risk weighting.
Canada’s approach to crypto regulation has historically favored stricter capital requirements than many international jurisdictions, reflecting persistent concerns about asset volatility, market maturity, and operational risks in digital-asset trading infrastructure. OSFI has maintained these heightened standards even as global regulators debate appropriate frameworks for crypto exposure in regulated institutions. The narrowly tailored relief announced in September represents a pragmatic acknowledgment that certain trading activities genuinely warrant technical refinement, while still preserving the overarching protective stance that has defined Canadian crypto guidance.
Market-Neutral strategies drive the hedging relief
OSFI identified in its May consultation materials that banks predominantly employ market-neutral strategies when managing crypto exposures and that prices for identical assets move nearly in lockstep across major regulated exchanges. Calculating risk on a per-exchange basis inflated both the measured delta risk and the capital required against it relative to the actual underlying position. The regulator concluded that treating exchanges as fungible venues for capital purposes would better reflect how these hedges actually function in practice.
Delta risk, which measures the rate of change in an option or derivative position relative to changes in the underlying asset price, represents the primary capital driver for most crypto hedging strategies employed by Canadian banks. By allowing cross-exchange netting on delta calculations, OSFI reduces the artificial inflation created when a single underlying exposure is fragmented across multiple venues for operational or liquidity reasons. The relief recognizes that if a bank holds a long bitcoin position on one regulated exchange and a short position on another to achieve price neutrality, forcing separate capital calculations would penalize the bank for pursuing a fundamentally risk-neutral strategy.
The relief is expressly limited to Group 2a exposures that satisfy the guideline’s full battery of hedging-recognition conditions.
Positions must meet product-structure and regulatory-approval tests, demonstrate adequate liquidity, maintain sufficient price data history, and either qualify for clearing through a recognized venue or receive explicit regulatory sign-off. Unregulated exchanges gain no such cross-venue netting treatment, and maturity mismatches between legs still prevent capital recognition. The framework retains a 94 percent correlation parameter for delta and vega calculations and maintains 100 percent risk weights for both, preventing any reduction in the absolute capital charge applied to Group 2a assets.
The distinction between Group 2a and Group 2b represents OSFI’s fundamental dividing line in crypto regulation. Group 2a encompasses assets that meet rigorous standards for liquidity, market development, and regulatory governance. Bitcoin and Ethereum qualify as Group 2a in most cases, provided they trade on approved venues and meet data requirements. Group 2b captures all other digital assets, including smaller-cap cryptocurrencies, tokens with limited trading history, or assets that fail to meet the regulatory approval thresholds OSFI has established.
Group 2b Assets face substantially harsher treatment
Crypto exposures classified as Group 2b, which fail to meet Group 2a hedging criteria, remain subject to far more stringent capital deductions. Banks must deduct from common equity tier 1 capital the greater of the absolute aggregate long or short position in each Group 2b asset, or the amount produced by the prescribed market-risk and credit-valuation-adjustment calculation, whichever is higher. This dual-hurdle approach eliminates any offsetting between long and short positions and effectively penalizes concentrated exposure to unhedged or non-qualifying crypto assets.
The Group 2b treatment reflects regulatory concern that smaller or less-developed digital assets lack sufficient market depth, price transparency, and regulatory oversight to justify capital-efficient hedging recognition. Institutions holding these exposures face a choice between accepting substantially higher capital charges or reducing their positions. This design creates a strong incentive for banks to concentrate crypto activity in Group 2a assets while minimizing speculative or illiquid holdings that would trigger the more punitive calculation methodology.
OSFI preserved Canada’s aggregate gross exposure limit for all Group 2 crypto assets at 5 percent of Net Tier 1 capital, excluding certain client-clearing derivatives from the calculation. A breach of this ceiling triggers automatic reclassification of an institution’s entire Group 2 crypto portfolio into the Group 2b category, cascading the stricter treatment across all holdings. The net effect is a hard ceiling on bank crypto exposure regardless of asset quality or hedging sophistication.
This aggregate cap serves as a backstop that prevents any individual institution from building a material crypto franchise regardless of how conservatively it manages individual positions. For a bank with 10 billion in Net Tier 1 capital, the 5 percent limit allows only 500 million in gross crypto exposure across all Group 2 assets combined. This ceiling ensures that crypto remains a marginal activity for the Canadian banking system as a whole, even if individual institutions pursue sophisticated risk management practices.
Implementation timeline and regulatory scope
The guideline takes effect November 1, 2026, for institutions with an October 31 fiscal year-end and January 1, 2027, for those with a December 31 fiscal year-end, aligning with the schedule OSFI announced when it opened consultation in May.
The effective dates provide approximately 16 months for affected institutions to assess their existing crypto portfolios, restructure positions to qualify for cross-exchange recognition where eligible, and implement system changes to track hedging relationships across venues. Banks holding Group 2b assets or exceeding the 5 percent aggregate limit will face the most material compliance burden, as reclassification or position reduction may be required to optimize capital efficiency.
OSFI’s staggered implementation timeline for different fiscal year-ends reflects standard practice in Canadian banking regulation and prevents any single cohort of institutions from facing disproportionate compliance pressure. The 16-month window is longer than many regulatory changes require, suggesting OSFI recognizes that system reconfiguration for crypto tracking and hedging documentation may require substantial IT investment and process redesign at many institutions.
Market participants should monitor whether Canadian institutions use the implementation window to reduce crypto holdings or restructure existing positions to meet Group 2a conditions, as banks’ capital optimization decisions will signal whether the relief is meaningful enough to sustain or expand their digital-asset operations. If institutions respond by exiting crypto markets entirely rather than reorganizing to claim the cross-exchange netting benefit, it would suggest that OSFI’s regulatory framework, while technically refined, remains too restrictive to support a material banking industry presence in digital assets.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.