Bitcoin faces shifting economic conditions as the Federal Reserve ends stimulus measures while the Treasury ramps up expenditures
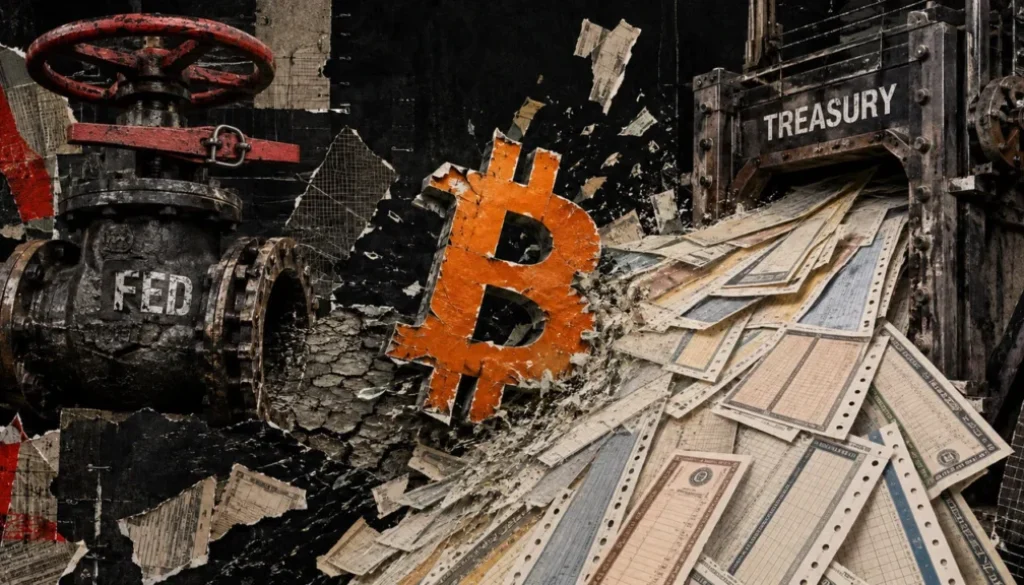
Bitcoin’s price outlook hinges on conflicting signals from the Federal Reserve and Treasury Department, each pursuing distinct policy goals that push financial conditions in opposite directions. Understanding which force dominates will prove crucial for investors positioning long-duration assets including cryptocurrencies.
- Federal Reserve held rates at 3.50% to 3.75% in July while three members voted for a rate increase, shifting discussion toward potential further hikes.
- Treasury Department doubled the maximum size of certain buyback operations for 10 to 30 year bonds from $2 billion to $4 billion per operation, effective Sept. 9.
- The 30-year Treasury yield fell initially after the Treasury announcement but returned to near prior levels within two weeks, suggesting markets assigned limited significance to the buyback program.
- 3.50%-3.75% Federal Reserve target range, with discussion shifting toward potential increases
- $4 billion New maximum per Treasury buyback operation for longer-duration government bonds
- 5.28% 30-year Treasury yield on Aug. 18, the day before the buyback announcement
- 25-30 bps Rise in nominal Treasury yields during July Fed meeting, driven by higher real rates
Bitcoin and other long-duration assets now navigate a macroeconomic environment where two separate U.S. government institutions pursue objectives that push markets in opposite directions simultaneously. On August 19, the Treasury Department announced it would double the maximum size of certain buyback operations for government bonds carrying 10 to 30 years remaining to maturity, raising the cap from $2 billion to $4 billion per operation beginning September 9. That same day, the Federal Reserve released minutes from its July meeting disclosing that three members had voted for a quarter-point rate increase, with many others believing another hike would be warranted if inflation failed to decline further. The Fed maintained its target range at 3.50% to 3.75%, though discussion had shifted from how long rates should remain elevated to whether they should climb higher. These concurrent announcements created competing pressures on bond markets: the Federal Reserve was attempting to make borrowing more expensive across the economy, while Treasury debt managers were seeking to improve trading conditions for older long-term government bonds. Borrowers and investors experience both effects at once, influencing everything from mortgage rates to cryptocurrency valuations.
Treasury buyback program shows limited market impact in initial response
The 30-year Treasury yield closed at 5.28% on August 18, fell to 5.19% following the buyback announcement, then returned to 5.27% by September 2, according to Treasury daily yield data. Despite the initial dip, the yield showed no lasting repricing in response to the buyback expansion. Multiple forces moved yields during those two weeks, and the larger buybacks had not yet begun, so the round trip cannot be attributed to Treasury action alone.
The modest response demonstrates that markets assigned little lasting significance to the announcement regarding the cost of government borrowing across a 30-year horizon.
Real Yields drive bitcoin’s immediate opportunity cost against bonds
Bitcoin reacts swiftly to changes in real yields because they represent how much investors can earn while accepting minimal credit risk. Bitcoin offers no contractual return, making a government bond offering generous real yields more attractive by comparison. The July Fed minutes disclosed that nominal Treasury yields had risen 25 to 30 basis points during the July meeting window, driven primarily by higher real rates rather than inflation expectations, indicating that investors demanded better returns once inflation was stripped away.
The same principle extends to technology shares valued on distant future profits, since elevated real yields discount those future earnings more severely in present-dollar terms. A higher cost of capital reaches far-dated cash flows, creating headwinds for long-duration assets including Bitcoin. Markets had already priced in a quarter-point increase by the September Fed meeting and another by the end of the first quarter of 2027, embedding expectations of sustained monetary restraint into asset valuations.
Treasury confronts enormous refinancing burden spanning hundreds of billions
The Treasury Department confronts a distinct challenge shaped by Congress’s control over federal spending and tax collection. Treasury debt managers must finance the resulting deficit, refinance maturing securities, and maintain U.S. government debt’s role as the world’s primary collateral pool. Treasury expects $739 billion of privately held net marketable borrowing from July through September, followed by another $628 billion from October through December.
The department must place an enormous volume of securities into private hands while preventing older bonds from becoming illiquid and expensive to trade. Buybacks sound more powerful than they actually are because the terminology suggests debt disappears, but the operation more accurately resembles exchanging one form of debt for another. Treasury sells new benchmark securities, uses cash to repurchase older issues, and creates room for dealers to move inventory that has become harder to trade, while the government still owes the replacement debt.
Treasury has stated that buybacks should have minimal effect on net marketable borrowing because new issuance replaces repurchased securities, distinguishing the program from quantitative easing.
Long-Term Yields absorb competing pressures from deficits and infrastructure demand
Long-term yields compress several competing pressures simultaneously. Federal deficits compete for a finite pool of savings while the artificial intelligence buildout pulls vast sums toward data centers and power generation infrastructure. Investors must price decades of inflation and political risk, while dealers and foreign reserve managers operate under their own constraints. The 30-year yield emerges from a far more complex interaction of forces than the Fed can control independently through its overnight operations and interest-on-reserves mechanisms.
The Fed pays interest on reserve balances and uses overnight operations to maintain the federal funds rate within its target range, but the long end of the curve operates under a system where investors estimate where short-term rates might average across coming decades, account for inflation expectations, and demand additional compensation for locking capital away. Economists refer to this final component as the term premium, essentially the price charged for waiting an extended period. Neither the Fed nor Treasury can control the 30-year yield independently because the market price reflects an interconnected system incorporating monetary policy expectations, fiscal trajectory, and multiple other factors.
Bitcoin faces dual pressure from monetary tightness and fiscal skepticism
Bitcoin typically experiences the Federal Reserve side first, as a higher expected policy path makes cash more attractive, supports the dollar, and raises the cost of holding leveraged cryptocurrency positions. A high real return on government debt creates a daily opportunity cost for owning an asset generating no contractual income. Treasury reaches Bitcoin through liquidity and fiscal credibility channels as well, since heavy issuance draws cash toward government auctions and can leave less balance-sheet room for risk assets depending on Treasury General Account levels and reserve conditions.
Bitcoin can trade like a long-duration risk asset during weeks when real yields spike sharply, then draw support across years from investors skeptical of the fiscal trajectory that helped push those yields higher. Persistent deficits and a larger federal interest bill strengthen the long-term case for holding a scarce asset outside the sovereign balance sheet. This longer-horizon fiscal-hedge support moves much more slowly than a bond selloff driven by rising real yields.
Multiple scenarios could reshape bitcoin’s trading range in coming quarters
Under a base case where real yields remain elevated but stable and heavy issuance continues with buybacks providing marginal liquidity support, Bitcoin would likely trade in a range, pulled between opportunity cost from elevated yields and fiscal-hedge demand. A bull scenario with falling real yields or fading Fed hike expectations, combined with persistent debt concerns and easing liquidity conditions, could benefit Bitcoin as risk appetite improves while fiscal-hedge demand persists.
A bear scenario featuring rising real yields with elevated term premiums would push Bitcoin to trade like a long-duration risk asset facing valuation pressure. A stress scenario involving disorderly yield spikes or worsening liquidity could initially drive Bitcoin lower alongside other risk assets before regaining attention as a sovereign-balance-sheet hedge. The Treasury yield curve operates as one interconnected system where the 2-year yield carries much of the expected Fed policy path, the 10- and 30-year yields incorporate debt supply considerations and term compensation, and real yields show Bitcoin’s opportunity cost.
The Federal Reserve controls key machinery by making overnight dollars more expensive, and the Treasury controls which bonds to issue or repurchase, but the long end of the curve still belongs to investors willing to commit capital for decades. Watch for the September Federal Reserve meeting decision on whether to implement the quarter-point rate increase multiple Fed members signaled as warranted, and track whether the doubling of Treasury buyback operations to $4 billion per transaction beginning September 9 produces meaningful improvements in long-bond liquidity or fails to arrest any further yield movement.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.