Federal Reserve publishes index showing financial leverage in elevated risk band
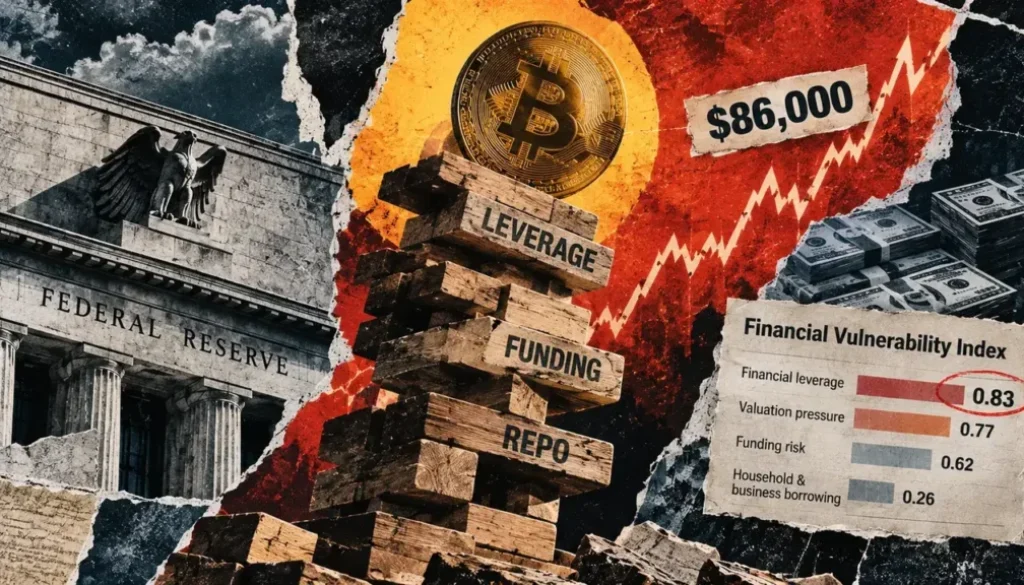
A new Federal Reserve working paper on structural financial risk landed the same week Bitcoin surged past $86,000, and the two signals describe entirely different timeframes. BlockWest readers watching leveraged crypto positioning should note that the Fed’s gauge is not built to call market timing, but it does measure how far the next shock could travel through the system.
- Bitcoin touched $86,000 on September 21, more than 10% above the prior Sunday close.
- The Fed’s Financial Vulnerability Index puts financial leverage at 0.83, inside its “elevated” band.
- Large hedge funds held $4 trillion of Treasury exposure and $3 trillion of repo borrowing as of September 2025.
- $86,000 Bitcoin’s high on September 21, over 10% above Sunday’s close
- 0.83 Fed financial-leverage reading, inside the elevated risk band
- $41B Bitcoin options open interest tracked this week by Glassnode
- $4T hedge funds’ gross Treasury exposure as of September 2025
Bitcoin traded to $86,000 on September 21, more than 10% above the prior Sunday close, driven by positive spot taker flow and rising volume, according to reporting by CryptoSlate. The same week, Federal Reserve researchers published a working paper introducing the Financial Vulnerability Index, a measure designed to track slow-building structural weakness rather than day-to-day market stress. Bitcoin’s price reflects today’s demand and positioning, while the index is built to show how much damage the next shock could cause.
Bitcoin touches $86,000 as short liquidations drive monday’s leg higher
Short liquidations helped push Bitcoin higher, as spot taker flow turned positive and trading volume rose, CryptoSlate reported. Futures open interest and the funding rates paid by long positions both climbed above Glassnode’s historical high bands.
Options open interest reached roughly $41 billion, and the options market was pricing in less movement than Bitcoin ultimately delivered, according to the same data. Rapid short covering paired with underpriced volatility can amplify a rally beyond what spot demand alone would produce.
Fed’s Financial vulnerability index reads ‘Elevated’ on Leverage
The Fed’s Financial Vulnerability Index differs from conventional financial-conditions gauges, which rise as credit tightens and stress becomes visible. It is instead built to capture vulnerability that accumulates during calmer periods and then declines once a crisis actually materializes.
A separate working paper detailing the index puts the aggregate FVI at 0.65, in the “notable” range on the paper’s five-tier scale. Valuation pressure scores 0.77 and funding risk 0.62, both also “notable,” while financial leverage sits at 0.83, inside the “elevated” band covering the top fifth of its historical distribution. Household and business borrowing is far lower, at 0.26, in the “low” band.
The paper’s chart labels the four subcomponents “Q1” and the aggregate index “Q2,” with 2026 as the final axis mark, but the underlying dataset and several estimation samples are described elsewhere in the paper as ending in 2025:Q4. It does not clarify whether the chart’s endpoint reflects a later-vintage observation, a nowcast, or a labeling convention, which limits how precisely the index’s current reading can be dated.
The paper’s historical model shows why the reading matters beyond the current cycle. In periods when the FVI was high, the same modeled business-cycle shock produced deeper declines in consumption and long-term investment than in low-FVI periods. Fed researchers describe the index as an amplifier gauge, measuring how much a shock could be magnified rather than predicting when one will hit.
The paper’s disclaimer notes it reflects the authors’ analysis and does not indicate concurrence by the Federal Reserve Board.
Hedge funds hold $4 trillion in Treasury exposure, Fed note shows
A June Fed staff analysis, Decomposing Hedge Funds’ U.S. Treasury Exposures, estimated that large hedge funds carried $4 trillion of gross Treasury exposure and $3 trillion of repo borrowing as of September 2025. Roughly $830 billion of that exposure ran through cash-futures basis trades and about $305 billion through swap-spread trades, the note’s proxy estimates show.
A separate Fed review of government bond-
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.