Bank of Japan will more than double annual ETF sales starting 2027
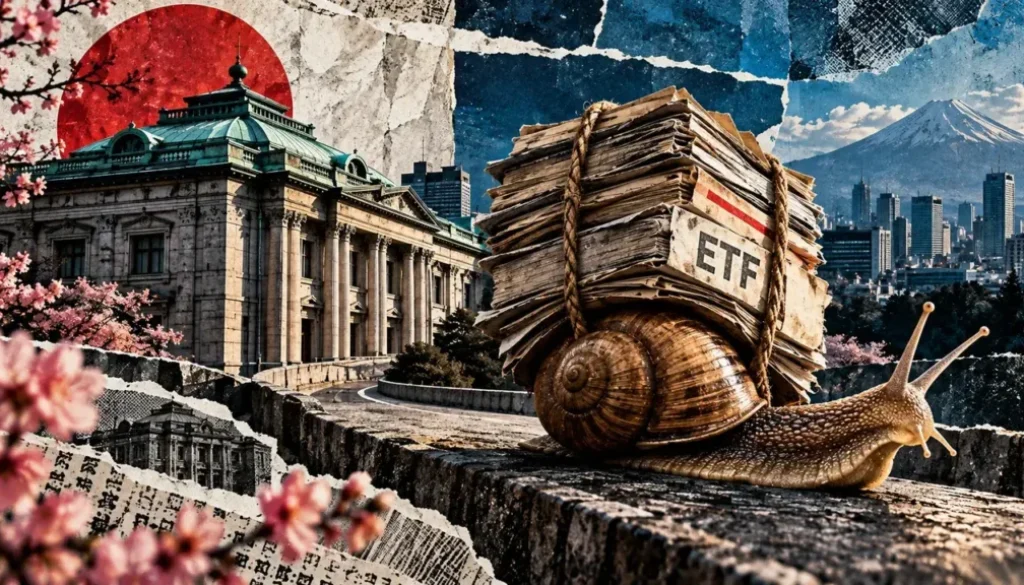
Japan’s central bank will more than double the pace of its stock fund sales starting next year, yet even at this accelerated rate faces a four-decade timeline to unwind decades of equity purchases made during its monetary easing campaign. The BOJ’s prolonged exit from equities highlights how difficult it can be for central banks to reverse large-scale asset purchases without destabilizing markets.
- The BOJ will sell ETFs at ¥860 billion annually by book value from January 2027, up from ¥330 billion.
- Even at the faster pace, the bank estimates it will take 43 years to exit its equity holdings, down from 112 years under the previous plan.
- The accelerated sales represent roughly one-thousandth of trading volume on the Tokyo Stock Exchange’s Prime Market, reflecting the bank’s effort to avoid market disruption.
- 2.6x Ratio of new annual ETF sales pace to the previous sales pace
- 43 years Estimated time to complete equity portfolio exit at accelerated sales rate
- ¥2.46 trillion Market value equivalent of annual sales, compared to ¥860 billion book value
- January 2027 Start date for the accelerated ETF disposal program
The Bank of Japan announced on Friday (October 30) that it will nearly triple its annual stock fund sales beginning in the new year, a move designed to speed its exit from equities accumulated over more than a decade of unconventional monetary policy. CryptoSlate reported the decision reflects the central bank’s challenge in unwinding one of the world’s largest holdings of exchange-traded funds without destabilizing the domestic equity market.
The BOJ’s prolonged equity ownership stems from its 2010 decision to purchase ETFs
The Bank of Japan began acquiring exchange-traded funds in 2010 as part of its comprehensive monetary easing program, when the economy faced weak demand and persistent deflation. By holding baskets of company shares through ETFs rather than picking individual stocks, the bank could reduce the extra return investors demanded for holding risky assets, a technique aimed at encouraging broader investment when short-term interest rates were already near zero. In a November 2010 speech, then-Governor Masaaki Shirakawa acknowledged that the program carried potential losses and deeper central bank involvement in allocating resources across companies and industries, responsibilities that would extend beyond the purchase phase itself.
The bank halted new ETF purchases in March 2024 but found itself unable to simply let the portfolio expire. Unlike bonds, which have maturity dates when issuers repay principal, ordinary equity ETFs have no fixed end point. To reduce its holdings, the BOJ must find actual buyers willing to absorb the risk of future price movements at prices the central bank considers acceptable.
The new sales pace aims to balance exit speed against market impact
The accelerated disposal program represents annual book-value sales of ¥860 billion, compared with ¥330 billion previously, beginning January 2027.
Book value differs materially from market value, a distinction that illustrates the complexity of unwinding large equity positions. The BOJ estimates that the new ¥860 billion annual pace in book value corresponds to approximately ¥2.46 trillion at current market prices, reflecting the gap between what the bank originally paid and what buyers will actually transfer. The central bank’s disposal rules require seeking “appropriate prices” while avoiding both losses and disruptions to Japanese markets, constraints that explain why even a 161 percent increase in the sales pace still stretches the exit over four decades rather than years.
The bank estimates that its revised sales will represent roughly one-thousandth of trading volume on the Tokyo Stock Exchange’s Prime Market, based on activity during January through September 2026. Officials have reported that sales since the program began in January 2026 have proceeded smoothly with no major market effects, providing confidence that the faster pace can be sustained without triggering adverse dynamics.
Future officials inherit both the assets and discretion to adjust the exit timeline
The 43-year estimate assumes a constant annual sales pace and should not be read as a completion forecast or proof that markets require four decades to absorb the portfolio.
The BOJ retained the option to adjust or suspend disposals when market conditions warrant, giving future policymakers flexibility to respond to shifting economic circumstances. The decision to accelerate also accounts for higher overall trading activity compared to when the original 112-year estimate was calculated. Because the bank is willing to hold equities longer in exchange for limiting the annual volume offered to buyers, the timeline reflects a choice about distribution rather than a market capacity constraint.
The structure of Japan’s equity exit has indirect implications for global financial markets, particularly for investors using yen-funded leverage to finance foreign assets including Bitcoin.
Traders who borrow yen at low rates to purchase dollar-denominated investments face exposure to yen strengthening, which erodes returns by reducing the yen proceeds from converting foreign assets back to repay loans. Higher borrowing costs in Japan or strain on yen funding markets could force liquidations across otherwise unconnected asset classes if investors need to raise cash to meet obligations. However, Ministry of Finance data does not show clear evidence of forced selling. During October 18-24, Japanese investors covered by the weekly foreign investment report sold ¥92.6 billion of foreign long-term debt but purchased ¥430.8 billion of foreign securities overall, suggesting net capital flows remained positive across broader categories despite selective debt reduction.
The BlockWest read. The BOJ’s four-decade math underscores how difficult central banks find it to exit once they enter equity markets. The bank chose prolonged ownership over rapid liquidation precisely because dumping assets quickly would crater prices and force losses. Future officials will inherit both the constraint and the discretion to change course, but market reality may bind them as tightly as it bound their predecessors.
Investors should watch whether trading conditions allow the BOJ to maintain the accelerated pace through 2027 without requiring adjustments, and whether higher yen funding costs begin to appear in emerging stress indicators, particularly in derivatives markets or financing spread data that would signal actual deleveraging pressure on yen carry trades.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.