Autonomous shopping agents strain merchant refund systems as regulators weigh liability rules
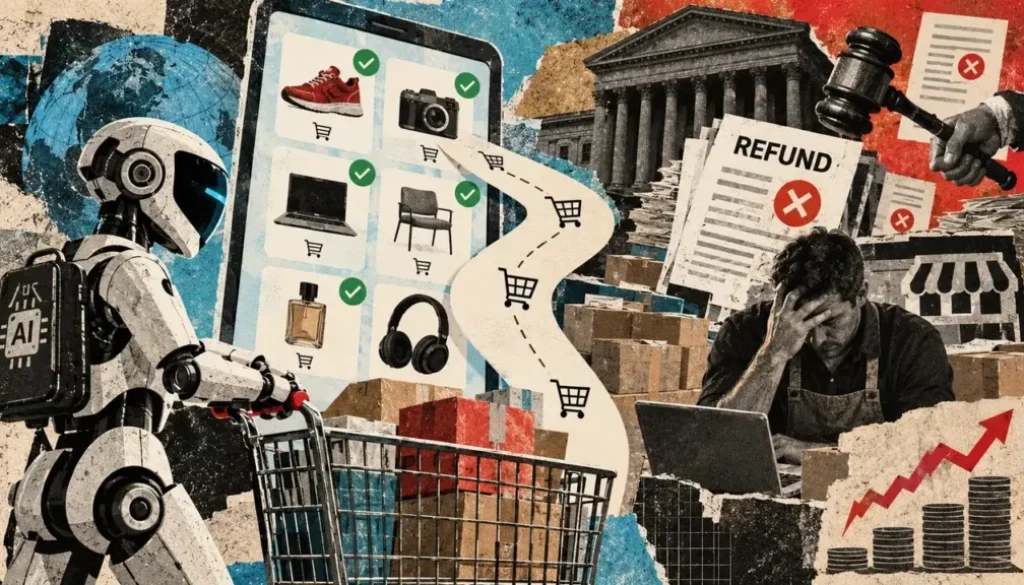
AI shopping agents can now make purchases autonomously, but the dispute resolution systems built for human shoppers are breaking under the weight of automated refund requests. Merchants face billions in new operational costs unless regulators and platforms establish clear liability rules before agent-driven commerce scales beyond early adopters.
- Amazon’s Bedrock AgentCore Payments, built with Coinbase and Stripe, enables AI agents to discover services, authenticate, and pay with stablecoins under spending limits.
- A 5 percent increase in chargebacks would add 16.2 million disputes and roughly $2.1 billion in operational costs for merchants globally, based on Mastercard’s $128 per-chargeback benchmark.
- The Reserve Bank of Australia documented merchant concerns on October 6 that chargeback liability remains unclear when AI agents act outside their authority, with regulatory priorities due by end of 2026.
- $128 Average merchant cost per chargeback in US, covering internal and third-party fees
- 324M Projected global chargebacks by 2028 under current Mastercard and Datos outlook
- 6.6M Consumer complaints to CFPB in 2025, double the prior year volume
- 6.9% Increase in favorable CFPB relief probability when LLM assistance files complaints
AI agents are moving money for online purchases before dispute systems designed for human shoppers can handle the load. According to CryptoSlate reporting, Amazon’s Bedrock AgentCore Payments, built jointly with Coinbase and Stripe, already allows autonomous agents to find services, verify identity, and pay using stablecoins and x402 tokens within preset limits. The technical layer works. The crisis lies in what happens after: when a buyer’s agent successfully completes a transaction but the customer then demands the money back, no established arbiter exists to say whether the agent acted within its authority or whether the merchant actually delivered what was promised.
Dispute automation threatens to overwhelm merchant operations
Edgars Nemse, CEO of the GenLayer Foundation, told CryptoSlate that payment itself is straightforward because deterministic: “the money moved, or it didn’t.” Fulfillment is not.
Payment “is the easy part, because it’s deterministic: the money moved, or it didn’t,” while “the outcome isn’t.” Defining if work was delivered as promised is a judgment call.
Edgars Nemse, CEO, GenLayer Foundation
Every dispute system has historically depended on a hidden assumption: that filing a complaint is tedious enough that most customers skip it. AI erodes that friction.
Complaints to the Consumer Financial Protection Bureau doubled to 6.6 million in 2025, and the regulator warned that language models and autonomous software can flood complaint systems with duplicative submissions. A Nature Human Behaviour study estimates that LLM use raises the probability of favorable CFPB relief by 6.9 percentage points. When disputing is free for an AI agent and costs merchants staff time to defend, the incentives flip entirely.
Mastercard and Datos projected 324 million chargebacks worldwide by 2028. Using Mastercard’s 2026 US merchant benchmark of $128 per chargeback for internal costs and third-party fees, excluding lost goods, a 5 percent increase from automation would add 16.2 million disputes and approximately $2.1 billion in operational costs. A 15 percent increase would add 48.6 million chargebacks and roughly $6.2 billion. Nemse noted that human staff reviewing each case are “already bending,” and those queues exist “Amazon’s included.”
Regulators flag unclear liability when agents exceed their mandate
The RBA received written submissions from 75 stakeholders to its payments review, published on October 6. Merchants, payment service providers, and issuers flagged that chargeback rules leave liability ambiguous when an agent acts beyond its authorization.
Submissions stated that agentic commerce could raise merchant costs and that payment networks may struggle to determine whether an agent followed its customer’s actual instructions. One stakeholder reported an additional 4 percent charge for AI-assisted purchases. Submissions generally described adoption as early, evidence of harm as limited, and preferred industry standards and monitoring over new regulation. The RBA plans to announce regulatory priorities by the end of 2026, and the central bank said it will draw on these submissions in considering which issues to prioritize under its mandate to control financial risk and promote payments efficiency.
Platforms control interfaces and judges, leaving small merchants dependent on their rules
Amazon blocked Meta’s Muse shopping agent citing unauthorized access and its own policies. Nemse sees this as a fight over control: Amazon has no doubt the agent can complete a purchase, but blocking it prevents handing over customer relationship, data, and advertising real estate worth billions. Google faces the same tension and will likely block outside agents while shipping its own. Shopify has moved toward admitting browser-based AI shopping agents into checkout.
Discovery of where to shop covers half the job; platforms own the interface and the judge. Small merchants can gain distribution through agents but have weak recourse unless neutral dispute standards emerge.
A CI&T survey of 1,011 US consumers found 27 percent comfortable with full AI shopping. Nemse argues the ceiling on agentic commerce is “the loss they’ll accept with no recourse.” API calls cost cents; agents pay those costs. For work, insurance claims, or refunds, “nobody lets an agent commit” without clear liability and someone bearing responsibility. “Better payment rails don’t move that ceiling,” Nemse said, because the problem is not speed or settlement but determining what was owed and who owes it.
Four competing models for agent dispute resolution are taking shape
Google’s AP2, Mastercard Agent Pay, and Visa Intelligent Commerce focus on authorization through signed mandates, tokenized credentials, and spending controls tied to agent identity. These prove what the buyer instructed but leave fulfillment judgment open. The card-network approach uses existing chargeback rails, familiar to merchants but potentially struggling to determine agent intent and subjective service delivery.
Nemse’s GenLayer Foundation proposes validators running AI models that reach consensus on outcomes, with verdicts enforced on-chain and subject to appeal. Common cases can resolve in roughly 30 minutes; fully escalated ones take about three hours. Fees, bonds, or reputation penalties must make frivolous disputes uneconomic when filing is free for an agent. Validators judge the evidence supplied—receipts, tracking, task specs—and appeals protect against bad model outputs while adding time and cost. An on-chain verdict governs escrowed funds, whereas a card refund sits outside its reach.
If merchants and networks establish standards with verifiable mandates, merchant evidence records, and escrow filtering disputes before they become chargebacks, agents can move from API calls into unfamiliar services. If disputes stay cheap to file and costly to resolve, merchants raise fees, restrict agent purchases, or redirect buyers back to trusted platforms.
The BlockWest read. Settlement infrastructure exists for deterministic payments; what remains unbuilt is the adjudication layer that lets small merchants and agents transact on open infrastructure. Platforms have every incentive to keep disputes inside their walled gardens. Whether neutrality emerges depends on whether regulators—now examining the gap—mandate standards before merchant costs force them to raise prices or shrink the addressable market for agent-driven commerce.
The RBA is scheduled to publish its regulatory priorities by the end of 2026, setting whether Australia will require agent mandates, evidence standards, or escrow mechanisms before merchants bear the full cost of dispute automation. That decision will likely shape whether other jurisdictions adopt similar rules or let platforms arbitrate agent commerce unilaterally.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.