Bitcoin hedge funds face liquidation despite profitable hedges split across exchanges
Institutional Bitcoin hedge funds face a structural vulnerability when their offsetting positions span multiple exchanges with separate collateral accounts. The risk intensifies as funds use leverage to amplify capital efficiency, creating scenarios where profitable hedges can be forcibly liquidated despite overall portfolio gains.
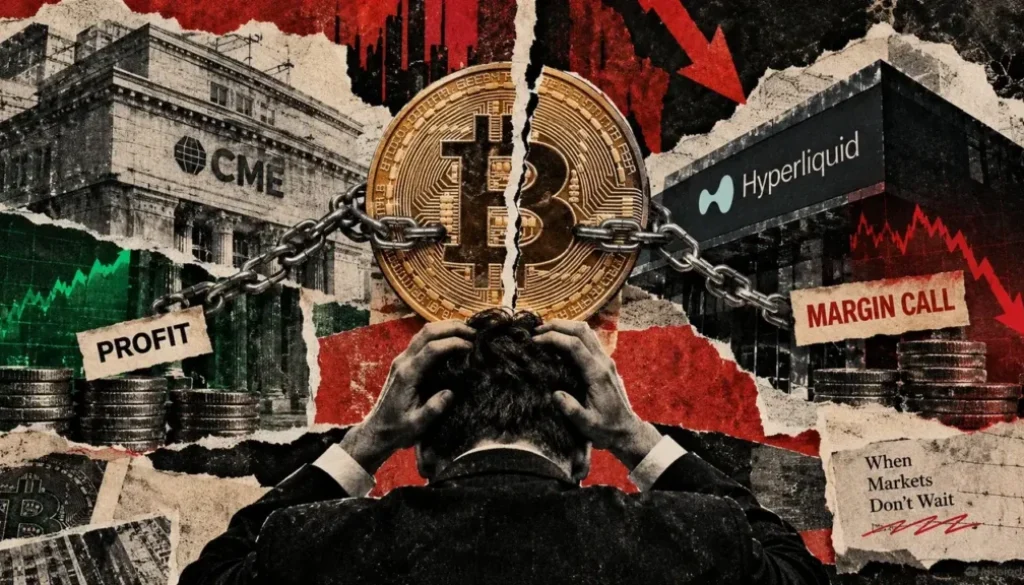
- A fund holding $4.5 million long on Hyperliquid and $4.5 million short on CME futures can face liquidation on one exchange despite offsetting profits on the other exchange when a 20% Bitcoin decline prevents capital transfer between separate margin accounts.
- Using $1 million in capital plus $2 million in borrowed funds, a hedge fund can control $9 million in total Bitcoin positions across exchanges by combining deposits with derivative leverage on each venue.
- Traditional prime brokers lack coordination across fragmented crypto markets, forcing funds to maintain separate collateral pools at each exchange despite positions designed to hedge each other.
- $4.5M Position size on each exchange in offsetting hedge example
- 20% Bitcoin decline that breaks the hedge despite matching profits and losses
- $9M Total position exposure funded by $1 million capital and $2 million borrowed
- 30-90 days Typical loan term duration through institutional platforms
Bitcoin hedge funds employing market-neutral strategies face an overlooked liquidation risk that strikes even when their overall portfolios remain profitable, according to analysis by CryptoSlate. The problem emerges because exchanges treat collateral as isolated pools rather than components of a coordinated strategy. When a fund maintains offsetting positions across different trading venues, each exchange enforces its own margin requirements and settlement schedules, preventing profits on one platform from covering losses on another even when the trades were designed to offset.
How a profitable hedge becomes a forced bet on price direction
Consider a hedge fund long $4.5 million of Bitcoin on Hyperliquid and short an equivalent $4.5 million through CME futures. If Bitcoin falls 20%, the short position generates roughly $900,000 in gains while the long loses approximately the same amount, leaving the fund essentially flat across its entire portfolio.
Hyperliquid, however, sees only a losing position and demands additional collateral to keep it open. CME recognizes the profitable short but holds those funds in a separate account with distinct margin and settlement terms. The fund must either transfer profits from CME to Hyperliquid, close both positions, or find additional capital before Hyperliquid liquidates the losing side unilaterally. During market downturns or exchange outages, transferring funds between platforms slows or halts entirely, leaving the fund unable to meet margin calls despite sufficient assets across its portfolio.
Once Hyperliquid closes the long position, the fund is left holding an unhedged short that loses money if Bitcoin rebounds, eliminating the entire purpose of the strategy.
Ian Weisberger, CEO of trading technology provider CoinRoutes, pointed to disorderly liquidations during the October 2025 crypto crash as evidence of how severe this problem becomes. Traders with balanced portfolios suddenly faced unhedged exposure because a single exchange closed one side of a hedge without accounting for offsetting positions elsewhere. “The problem isn’t necessarily that the fund made a bad bet; it’s that the money needed to keep the bet alive was sitting somewhere the exchange couldn’t reach,” Weisberger explained to CryptoSlate.
Leverage amplifies the collateral problem across markets
The vulnerability intensifies when funds use borrowed capital and derivatives to magnify their positions. Weisberger described how a hedge fund depositing $1 million in USDC could theoretically control $9 million in Bitcoin exposure by borrowing $2 million and applying leverage on each exchange. The fund allocates $1.5 million to CME and $1.5 million to Hyperliquid, then uses derivatives to establish $4.5 million positions on each platform, combining its own capital with borrowed money and market leverage.
Instead of betting on Bitcoin’s direction, the fund targets small discrepancies between futures prices, perpetual funding payments, or other arbitrage opportunities. If Bitcoin rises 10%, the long position gains roughly $450,000 while the short loses approximately the same, leaving directional exposure neutralized as intended. However, the hedge only works in theory when both exchanges process positions independently of each other. Futures and perpetuals can diverge, funding payments can become expensive, and even a 1% pricing gap between two $4.5 million positions creates a $45,000 margin call that neither exchange will offset against profits held elsewhere.
The efficiency trap worsens as funds optimize capital use. Keeping large deposits at both exchanges to cover all scenarios becomes expensive when the business model depends on extracting small price differences. Instead, funds make the same capital work harder, reducing the cushion available when something goes wrong. “The more exposure a fund can support with every dollar, the more dependent it becomes on being able to access that dollar when something goes wrong,” Weisberger said.
Coordinated collateral management attempts to bridge the exchange divide
CRX Trade, a Swiss institutional prime brokerage built on CoinRoutes technology, is now attempting to solve this fragmentation by coordinating collateral across crypto and traditional markets. The platform allows professional traders to manage Bitcoin, stablecoins, and tokenized assets as a single collateral pool spanning Hyperliquid, CME, and other venues rather than maintaining separate deposits at each exchange. Instead of funding each venue independently and hoping transfers execute quickly during a crisis, funds route positions and financing through one account that monitors total portfolio risk.
The system assesses both position sizes and remaining directional risk when they are combined. A lender might agree to finance a fund controlling nine times its original capital because the fund borrowed only $2 million rather than $9 million, with offsetting positions intended to neutralize directional exposure. CRX’s risk engine monitors the portfolio and can reduce exposure before an individual exchange forces a liquidation. Under delta-neutral liquidation, the system attempts to close both sides of a hedge together, preventing the scenario where an exchange liquidates the losing half and leaves the fund exposed to an unwanted market bet.
These coordination tools cannot eliminate fundamental constraints. Software cannot force an exchange to process orders during an outage, and it cannot guarantee buyers will appear at reasonable prices when markets move rapidly. Exchanges retain the right to liquidate positions failing to meet their margin requirements, and CRX’s ability to keep hedges intact depends on its own operational and custodial arrangements. The platform does not itself provide loans but coordinates financing from independent lenders, and clients’ asset recovery in any insolvency would depend on the underlying contracts and jurisdictions involved.
Converting Bitcoin collateral into cash across markets
The same coordination infrastructure allows funds to use Bitcoin holdings to support trades in markets where Bitcoin itself is not accepted as collateral, such as CME futures.
A client holding $1 million in Bitcoin can transfer it to a crypto exchange, sell $500,000 worth, and replace that portion with $500,000 in Bitcoin futures or perpetuals. The fund now owns $500,000 in spot Bitcoin and $500,000 in derivative exposure, maintaining similar price sensitivity while freeing $500,000 in cash to move through CRX’s USDC infrastructure to CME. Only half the original Bitcoin is sold, and the fund has purchased a contract matching the exposure surrendered, not double-leveraging the capital.
The derivative contract carries its own margin requirements and financing costs, introducing another position vulnerable to liquidation if collateral falls short. Weisberger estimated that borrowing cash directly against Bitcoin typically costs around 8%, while replacing spot exposure with derivatives means paying futures basis or perpetual funding rates instead. The latter could prove cheaper but introduces pricing volatility and additional fees, and the fund still assumes the risks of maintaining another funded position during market stress.
Custody arrangements reduce but do not eliminate exchange risk
CRX employs tri-party settlement where available, keeping collateral with a separate custodian rather than depositing it directly at the exchange. The trading venue processes trades while assets remain with the custodian, with profit and loss settled periodically, typically every eight or 24 hours. This limits the collateral directly exposed to an exchange withdrawal freeze to unsettled profit and loss rather than the entire deposit, reducing but not eliminating exchange-specific risk.
CRX Trade is operated by RAS Capital, a Swiss financial intermediary affiliated with VQF, a regulator-recognized self-regulatory organization. Clients retain legal ownership of assets held in dedicated, segregated wallets and exchange subaccounts according to Weisberger’s statements, but if a client borrows money, the lender receives a lien over the collateral under a separate agreement. The fund owns the Bitcoin, but the lender has an enforceable legal claim if obligations are breached. Meanwhile, exchanges maintain their own margin requirements and contracts, while custodians operate under separate agreements governing asset access and control.
Coordinating these relationships does not eliminate any of them, only makes them easier to manage together.
Collateral kept away from an exchange reduces one type of risk but introduces another: the assets must pass through multiple institutions, each of which has enforceable claims that take priority in any insolvency. CRX did not disclose whether collateral can be pledged onward by lenders or custodians, a detail that could affect asset recovery if any party to the arrangement becomes insolvent. The ultimate availability of collateral in a true crisis depends on contracts and the legal systems governing each relationship.
Loan maturity creates a second collateral crisis
Loans arranged through CRX typically run for 30 to 90 days with agreed leverage limits, collateral weights, and loan-to-value requirements.
When the loan matures, the lender can decline to renew, forcing the fund to repay the money or find alternative financing regardless of whether the trading strategy remains profitable. Exchange margin requirements and derivative funding costs can also shift during the loan term, and the fund may suddenly face additional collateral demands from both its lender and trading venues simultaneously. During market disruptions, when the fund most needs liquidity and lowest costs, transfers become slower and closing positions grows more expensive.
This dynamic exposes the trade-off underlying capital efficiency in institutional Bitcoin trading. Coordinating positions and collateral across exchanges can reduce unnecessary liquidations, free capital, and lower hedging costs. However, it also enables funds to support larger positions without committing additional capital, and larger positions increase the cost when lenders, exchanges, and custodians all need to perform at the same moment. The measure of that efficiency reveals itself not in calm market conditions but when every participant wants their money back simultaneously.
The BlockWest read. Platforms like CRX represent genuine infrastructure progress, but they cannot solve the fundamental problem: when borrowed capital finances large positions across multiple venues, the fund becomes deeply dependent on the continuous cooperation of every lender, exchange, and custodian. Capital efficiency and financial resilience move in opposite directions. The real stress test arrives during the next market dislocation, when basis widens, funding rates spike, and simultaneous collateral calls force unwinds at the worst possible prices.
The next critical test arrives whenever markets face sustained disorder. Funds operating through coordinated collateral systems like CRX will quickly reveal whether their risk management can actually prevent the scenario Weisberger described, or whether coordinating the problem makes it only marginally less severe. The October 2025 crash provided evidence but not a full resolution; the next major Bitcoin drawdown will determine whether prime brokerage solutions have genuinely solved the multi-exchange liquidation trap or merely delayed it until a larger shock arrives.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.