Cryptocurrency investors are accumulating call options as cash traders continue offloading holdings
Bitcoin’s options market is pricing in renewed bullish sentiment while institutional inflows accelerate, yet spot exchange trading remains dominated by sellers. This divergence between derivatives positioning and actual spot demand leaves the market vulnerable to a failed breakout attempt above $80,000.
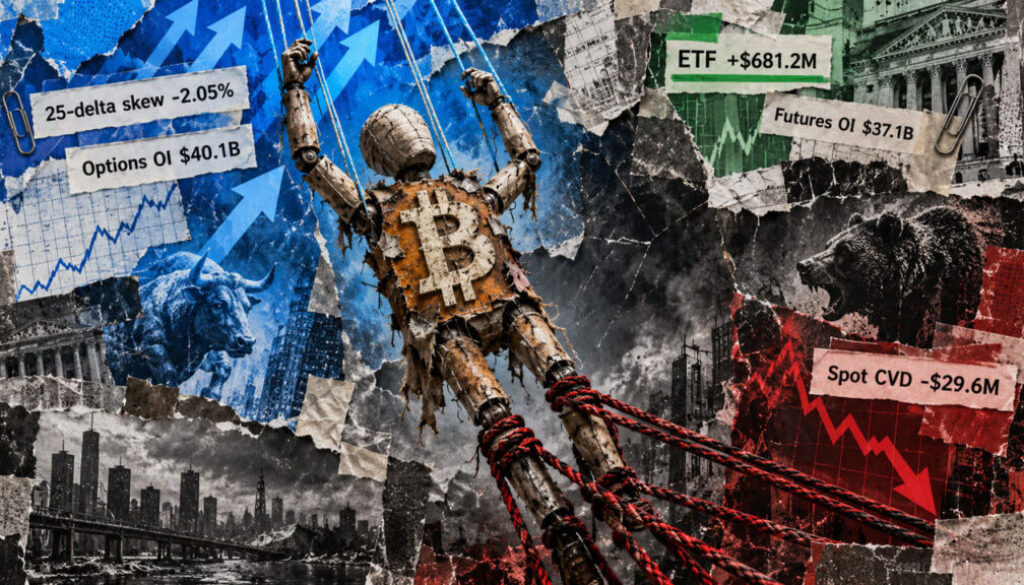
- Bitcoin’s 25-delta options skew shifted to -2.05% from +0.79%, signaling calls have become relatively more expensive than puts
- US spot Bitcoin ETFs recorded $681.2 million in net inflows, up substantially from $247.8 million in the prior week
- Spot cumulative volume delta remained negative at $29.6 million, showing sellers still dominate exchange flow despite easing pressure
- $78,800 Bitcoin’s price on Tuesday after failing to sustain moves above $80,000
- -2.05% Current 25-delta skew, indicating growing relative demand for call options
- $681.2M Weekly US spot Bitcoin ETF inflows, versus $247.8M the prior week
- $37B Open interest in perpetual futures markets, showing leverage remains elevated
Bitcoin’s derivatives market has swung toward bullish positioning even as the spot price struggles to maintain ground above $80,000. Options traders are increasingly willing to pay for upside exposure, institutional capital is flowing into regulated investment vehicles at an accelerating pace, and leverage on futures markets remains substantial. Yet on centralized exchanges, sellers continue to outweigh buyers, creating a fundamental mismatch between what different market participants are signaling about Bitcoin’s near-term direction.
This market divergence reflects a broader structural shift in how Bitcoin trades across different venues and investor classes. The emergence of spot Bitcoin ETFs has created a bifurcated market where institutional capital flows through regulated vehicles at one end of the spectrum while retail traders and professional market makers continue to drive volume on cryptocurrency exchanges. Understanding this split is essential to interpreting the mixed signals emanating from on-chain and derivatives data.
Call Options growing more expensive relative to put Options
The clearest shift has occurred in Bitcoin’s options market, where the 25-delta skew moved to -2.05% from +0.79%, according to Glassnode’s Market Pulse analysis. Under this methodology, the swing indicates that call options have become relatively more expensive than puts, a reversal from the more defensive positioning seen in prior periods.
This pricing shift signals traders are increasingly willing to pay a premium for the possibility of further upside moves. The change reflects genuine conviction among options traders rather than passive positioning, since it requires active bidding up of call prices relative to downside protection. A positive skew typically emerges during risk-off environments when traders want protection, while negative skew suggests bullish conviction.
The options market carries particular significance because it represents forward-looking pricing by sophisticated traders with real capital at risk. Options trading requires precise directional views and timing, making skew shifts meaningful indicators of sentiment shifts across professional desks. However, options markets can also be influenced by hedging activity unrelated to near-term directional views, which adds interpretive nuance to any single data point.
Institutional Inflows into Spot ETFs accelerate sharply
Institutional capital is moving in the same direction as options positioning. US spot Bitcoin ETFs attracted $681.2 million in net inflows over the latest weekly observation period, more than double the $247.8 million seen in the prior week. The acceleration provides real capital behind the more constructive derivatives sentiment and indicates that regulated investment vehicles continue to draw demand from institutional investors despite Bitcoin’s failure to hold above $80,000.
The combination of rising call option demand and accelerating ETF inflows gives bulls more concrete support than options pricing alone would provide. However, this institutional optimism has not yet translated into broad buying pressure on cryptocurrency exchanges. This disconnect matters because it suggests different investor classes hold fundamentally different assessments of Bitcoin’s current price level.
The growth in spot Bitcoin ETF adoption represents one of the most significant structural changes in cryptocurrency markets over the past two years. These vehicles allow institutional investors to gain Bitcoin exposure through familiar regulatory frameworks without managing custody or exchange account logistics. As ETF adoption expands, it creates a growing class of Bitcoin holders who do not actively trade on spot exchanges, potentially explaining why institutional inflows diverge from spot exchange dynamics.
Exchange Spot flow remains net negative despite easing pressure
Glassnode’s spot cumulative volume delta improved sharply but remained negative at $29.6 million, a substantial improvement from the previous week’s -$84.9 million. This metric tracks the balance between aggressive market buying and selling on spot exchanges, with a negative reading indicating that sellers are still executing more volume than buyers, even though the imbalance has narrowed considerably.
The perpetual futures market shows similar hesitation about Bitcoin’s near-term trajectory. Glassnode said perpetual CVD remained negative at -$176, while long-side funding payments declined, suggesting leveraged traders are becoming less willing to pay a premium for bullish exposure. Perpetual futures open interest remains elevated at $37 billion, which means traders have not abandoned leverage entirely, but they are also not showing the aggressive long positioning that would normally accompany confidence in an imminent breakout above resistance.
The distinction between perpetual and spot markets highlights how differently Bitcoin trades across venues. Perpetual futures allow traders to express leveraged directional views without needing to hold actual Bitcoin, attracting professional trading desks and retail speculators. When funding rates decline, it typically indicates reduced enthusiasm among leveraged longs, which can signal vulnerability for near-term price support even if spot ETF demand remains strong.
The result is a market divided by conviction level. ETF investors are allocating capital, options traders are paying relatively more for upside, and exchange sellers are becoming less aggressive, yet none of these developments alone establishes that Bitcoin has the underlying demand needed to hold above $80,000. The mixed signals create risk for traders holding bullish leverage, since a sustained move lower could rapidly reverse the current options positioning and ETF inflows.
The next meaningful test will come from spot exchange flow. If cumulative volume delta turns positive while ETF inflows remain strong, Bitcoin would have evidence that the optimism visible in options is spreading into direct buying pressure. If spot selling persists instead, derivatives traders may find themselves positioned for a breakout that the underlying market still refuses to support. This divergence ultimately determines whether the current institutional and options-market bullishness represents genuine demand or simply positioning by traders betting on moves they cannot sustain through actual purchases.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.