Copper Reaches Record Levels: Understanding The Recent Surge In The Metal’s Value
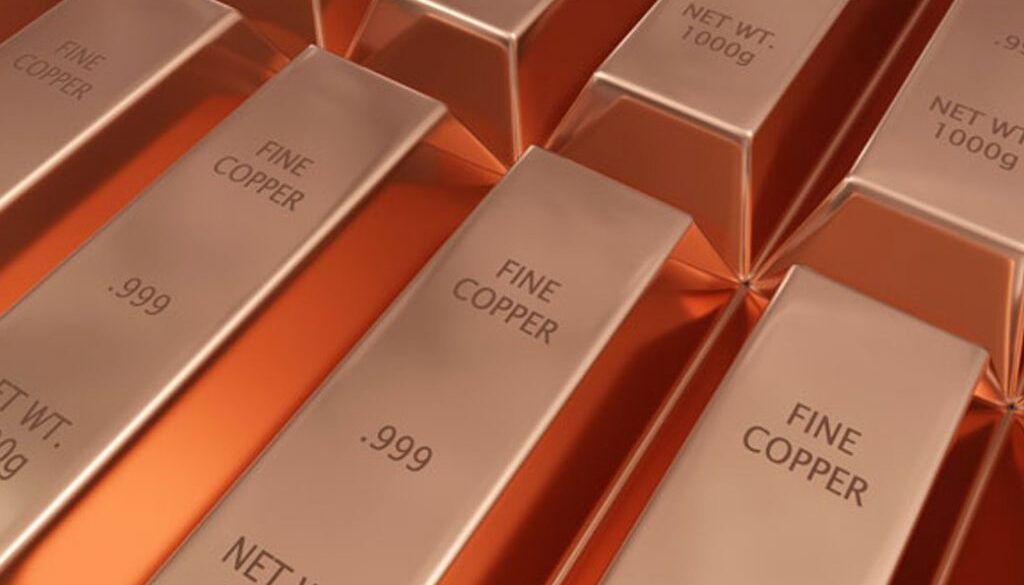
Copper has reached an unprecedented price level amid tariff concerns and surging AI infrastructure demand, creating supply pressures that extend beyond traditional commodity cycles. The move carries implications for tech stocks, renewable energy investments, and broader inflation expectations that markets are closely monitoring.
- Copper futures hit $14,533 per ton on the LME, the highest price on record for the commodity.
- The metal has gained nearly 17% over the past year, driven by tariff anticipation and AI data center expansion.
- Uncertainty remains over whether tariffs will actually materialize and how the Federal Reserve’s rate decisions will affect investor demand.
- $14,533 Copper futures price per ton at all-time high on LME
- 17% Year-over-year price gain for copper since previous January
- 25 bps Potential Federal Reserve rate increase after softer August jobs data
Copper futures on the London Metal Exchange have climbed to $14,533 per ton, marking an all-time high for the commodity. The surge represents a gain of nearly 17% over the past year and reflects a confluence of supply constraints and demand pressures reshaping global copper markets. Two distinct forces are driving the price action: anticipated US trade policy shifts and structural demand from artificial intelligence infrastructure buildout.
Copper’s role as an essential industrial metal makes its price movements particularly significant for the broader economy. The red metal serves as both a direct input to manufacturing and an indirect indicator of economic health, often referred to as the “Dr. Copper” indicator by analysts who view copper price movements as a diagnostic tool for assessing global growth prospects. The current rally suggests markets are pricing in sustained economic activity despite broader macroeconomic uncertainties.
Tariff expectations spark pre-emptive buying and supply disruption
Traders anticipating potential US tariffs on refined copper imports have accelerated shipments into the United States, with hundreds of thousands of tons redirected to beat any incoming duties. This front-running activity has tightened global copper availability and contributed directly to the price spike. The tariff uncertainty has created a genuine supply crunch as material flows shift in response to policy expectations rather than underlying consumption patterns.
Whether President Trump will ultimately extend tariffs to copper remains an open question.
Global copper trade typically flows through major hubs including Chile, Peru, and Congo, which together account for the majority of world production. Disruptions to shipping patterns and inventory management across these supply chains amplify price volatility when traders attempt to frontrun potential policy changes. Port facilities and storage capacity constraints mean that accelerated import activity can quickly exhaust available handling capacity, further tightening spot market conditions.
AI Infrastructure and mining capacity create structural Demand imbalance
Beyond tariff dynamics, copper demand from artificial intelligence data centers and semiconductor manufacturing has grown substantially. Copper is essential to chip production, and significant portions of global supply have been absorbed by the expanding AI industry. This structural demand increase coincides with aging copper mines struggling to expand output at the pace required to meet global needs.
The AI data center buildout represents a genuinely new demand source that differs from cyclical construction and manufacturing patterns. Major technology companies have committed to massive capital expenditure programs for computing infrastructure, creating forward demand visibility that extends beyond typical business cycles. Each data center requires thousands of tons of copper for electrical wiring, transformers, and cooling systems, multiplying across hundreds of planned facilities globally.
Renewable energy projects and power grid modernization represent additional demand vectors that could sustain elevated copper consumption for years. Wind and solar installations require significantly more copper per unit of energy capacity than traditional fossil fuel infrastructure, creating a structural headwind for supply availability. The combination of legacy mining capacity constraints and multiple competing demand centers suggests a persistent supply tightness that could support prices absent a major demand shock.
Interest rate decisions and safe-haven flows present downside risks
The Federal Reserve may raise interest rates by 25 basis points following softer August employment data, a move that could redirect investor capital toward safe-haven assets like gold and away from commodities more sensitive to growth expectations. Higher borrowing costs could also dampen demand in price-sensitive sectors that consume copper for construction and manufacturing.
Historically, copper prices demonstrate significant sensitivity to interest rate expectations, as higher rates increase the opportunity cost of holding non-yielding commodities in investment portfolios. Currency movements accompanying Fed rate decisions also influence copper pricing, since the commodity is traded globally in US dollars. A strengthening dollar would make copper more expensive for international buyers, potentially reducing demand at the margin.
Copper’s trajectory now hinges on three unresolved variables: whether the Trump administration applies tariffs to refined copper imports as traders currently anticipate, the magnitude and timing of any Federal Reserve rate increases, and whether AI infrastructure spending sustains its current pace. Market participants should monitor tariff announcements from US trade officials and the Fed’s communications around interest rate policy in the coming weeks, as either could trigger sharp repricing of copper positions.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.