Bitcoin drops below $80,000 as robust August jobs report shifts expectations for future Federal Reserve interest rate moves
Bitcoin’s drop below $80,000 reflects the cryptocurrency’s acute sensitivity to U.S. labor market data and Federal Reserve policy signals, with inflation now positioned as the decisive factor in the central bank’s near-term rate decisions. The August jobs report’s strength has compressed the case for rate cuts based on employment weakness alone, shifting market focus squarely to price pressures ahead of the Fed’s September meeting.
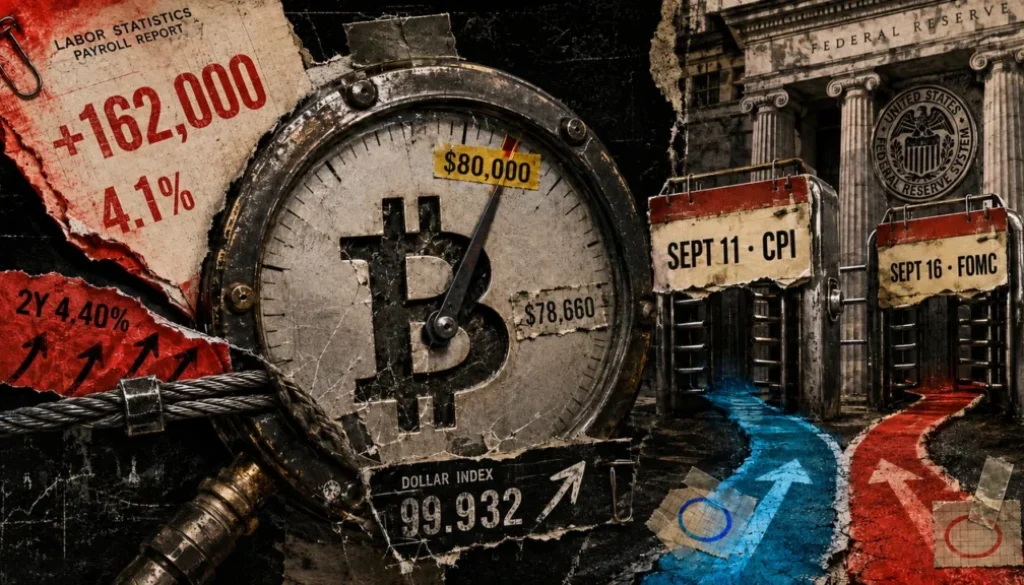
- Bitcoin fell to an intraday low of $78,660 on September 4 following stronger-than-expected August employment data.
- Nonfarm payrolls rose by 162,000 in August, significantly above the prior 12-month average of 31,000 monthly gains.
- August consumer price index data on September 11 becomes the critical catalyst before the Fed’s September 16 policy decision.
- 162,000 Nonfarm payroll gain in August versus prior year monthly average
- 4.40% Two-year Treasury yield post-jobs release versus pre-release 4.33%
- $37.75 Average hourly earnings for private nonfarm workers, up 3.1% year-over-year
- 99.932 Dollar index following jobs data release versus pre-release 99.035
Bitcoin declined sharply on September 4 following the Labor Department’s release of August employment data that exceeded market expectations and reshaped near-term Federal Reserve policy assumptions. The cryptocurrency registered an intraday low of $78,660 before recovering to trade near the $80,000 level. The move reflected broader market repricing of monetary policy expectations, with Treasury yields and the dollar both climbing sharply in response to evidence of labor market resilience.
The two-year Treasury yield rose to near 4.40% from just above 4.33%, while the 10-year yield climbed to near 4.80% from just under 4.75%. The dollar index touched 99.932, up from approximately 99.035 before the data release. These synchronized moves across asset classes demonstrated how tightly interconnected market expectations have become around central bank policy timing and direction.
August payrolls surge well above year-long trend
The Bureau of Labor Statistics reported that nonfarm payrolls rose by 162,000 in August, a significant increase compared to the average monthly gain of just 31,000 over the previous 12 months. The unemployment rate remained steady at 4.1%, indicating no deterioration in labor market conditions. The agency also raised its estimates for prior months, adding a combined 55,000 jobs to June and July through upward revisions, which strengthened the perception of underlying labor market momentum.
Average hourly earnings for private nonfarm workers rose 0.3% in August to $37.75, with annual growth at 3.1% year-over-year, a rate that remains above the Federal Reserve’s 2% inflation target. This wage growth trajectory has long concerned Fed policymakers, as elevated compensation growth can perpetuate inflationary pressures by boosting consumer spending power and potentially feeding back into broader price increases.
Employment gains were unevenly distributed across sectors. Food services and drinking places accounted for 59,000 of the new jobs, while local government education added 42,000. Information employment fell by 23,000, while health care added 13,000 jobs, below that sector’s 32,000 average monthly gain over the prior year. These variations illustrated the uneven nature of labor market expansion despite overall strength, with service industries anchoring the gains while some technology-adjacent sectors showed weakness.
Inflation emerges as primary Fed Policy driver
The stronger-than-expected labor market data narrowed the case for an immediate Federal Reserve rate pause based on employment weakness alone. For much of 2024, policymakers had cited slowing job growth as a key rationale for considering rate cuts to support employment and prevent economic slowdown. That argument now carried considerably less weight as labor market stability became evident.
The shift reflects a fundamental change in the Fed’s policy calculus. With the employment side of the central bank’s dual mandate appearing reasonably healthy, inflation control has moved to the forefront of policy considerations. This reorientation has historically favored tighter monetary conditions and higher real interest rates, conditions that typically pressure asset prices.
Federal Reserve Governor Christopher Waller addressed this policy tradeoff in remarks published the day before the jobs release. Waller described the labor market as satisfactory and stable, with employment near its maximum sustainable level, and said that August inflation would heavily influence his September stance.
Continued progress toward the Fed’s 2% goal would make him willing to hold the policy rate steady, while a hot reading, or evidence that progress had reversed, could make him consider a hike.
Christopher Waller, Federal Reserve Governor
The stronger payroll report removed the obvious labor deterioration that might have counterbalanced a concerning inflation reading, leaving price pressures as the clearer driver of the policy outlook. The Federal Reserve’s dual mandate requires it to pursue both price stability and maximum employment, but with employment clearly stable, inflation trends became the determining factor for decisions ahead.
September 11 CPI release sets market’s next critical test
The August consumer price index is scheduled for release on September 11 at 8:30 a.m. ET. The Federal Reserve has scheduled its policy decision for September 16, creating a five-day window in which inflation data will be the last major economic test before the formal announcement. This timing structure concentrates market focus on a single data release.
For Bitcoin traders, the September 11 CPI release represents the next critical inflection point before the Fed decision. Cryptocurrency markets have become increasingly tied to Fed policy expectations, as higher interest rates typically reduce demand for non-yielding assets like Bitcoin by improving returns available from bonds and cash alternatives.
A cooler inflation reading would align with the conditions Waller outlined for holding rates steady, potentially easing pressure on yields and the dollar that have weighed on the cryptocurrency. Conversely, a hotter inflation print would strengthen the case that price pressures have stalled despite a resilient labor market, potentially pointing toward tighter policy ahead and further pressure on Bitcoin prices.
Bitcoin’s immediate post-payroll decline below $80,000 underscored how sensitive the asset remains to macro conditions that shift expectations around Fed policy. The cryptocurrency’s volatility in response to economic data releases has made it increasingly relevant to mainstream investors tracking monetary policy impacts across asset classes.
The August CPI data arriving on September 11 will be the final major economic indicator before the Fed’s September 16 policy announcement, and market volatility around Bitcoin may be most acute on that inflation release date rather than at the formal policy decision itself.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.