Lagarde to depart ECB before Appia tokenized finance blueprint arrives in 2028
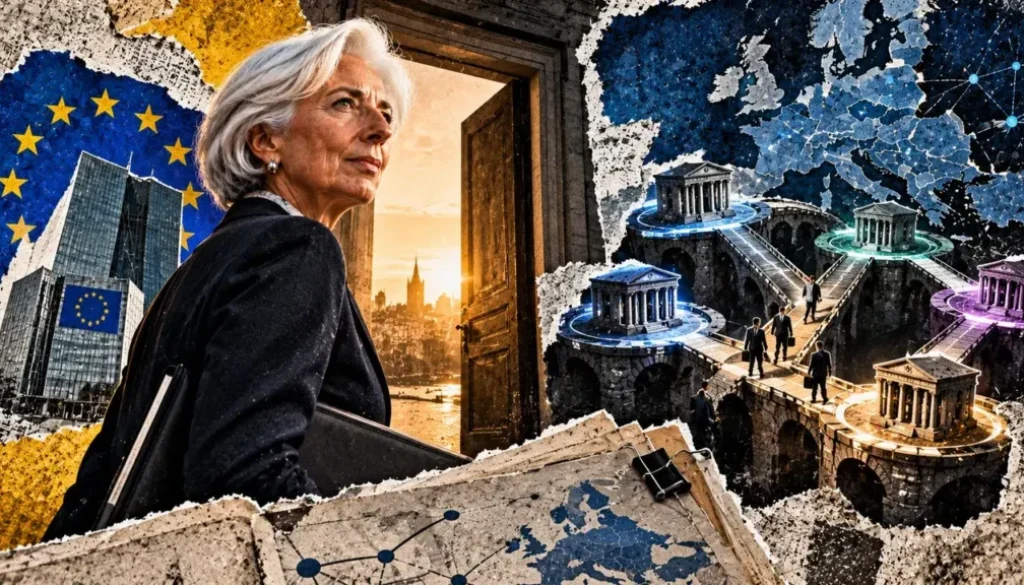
Christine Lagarde’s departure from the ECB in February 2027 leaves Europe’s blueprint for tokenized finance unfinished, with fundamental questions about market structure still unresolved as the Eurosystem races to deliver its Appia roadmap by 2028. Her successor will inherit a complex infrastructure design challenge with no clear consensus on whether to concentrate settlement on a single network or allow multiple competing platforms.
- Lagarde will step down as ECB president on February 7, 2027, before the Appia blueprint is due in 2028.
- The Eurosystem’s consultation on Appia received 127 responses that identified tradeoffs between network efficiency and competitive choice without recommending a single architecture.
- Pontes, the ECB’s tokenized asset settlement platform, launched September 21 with initial services and is planned for 24/7/365 operation by 2028.
- Feb 7, 2027 Lagarde’s departure date as ECB president, five years into her second term
- 127 Respondents to the Eurosystem’s public consultation on the Appia tokenized finance roadmap
- Sept 21 Launch date for Pontes, connecting market DLT platforms to ECB settlement services
- 2028 Target year for both Appia blueprint delivery and Pontes 24/7/365 availability
Christine Lagarde announced on Thursday (October 29) that she will leave her post as president of the European Central Bank on February 7, 2027, departing before the central bank completes its strategic framework for Europe’s emerging tokenized finance markets. According to reporting by CryptoSlate, her exit comes as the Eurosystem weighs competing approaches to organizing settlement infrastructure for tokenized wholesale assets through its Appia initiative. The timing leaves her successor to navigate the final stages of a design process that has exposed fundamental tensions between market efficiency and competitive access.
The Eurosystem published the findings of its Appia public consultation on Thursday (October 29), the same day as Lagarde’s announcement. The consultation report summarized 127 responses on how central bank money should be made available across distributed ledger technology platforms used for tokenized asset issuance, trading and settlement. The submissions reveal a central policy tension: concentrating settlement liquidity on a single network could reduce fragmentation and duplicated investment, but the same arrangement could concentrate control in a way that raises barriers to entry and creates dependence on a particular vendor or technology.
Respondents split on whether a single network or multiple platforms serve Europe better
A single-network model would pool central bank money settlement in one location, allowing common processes and simpler coordination among participants. Supporters noted that concentrated liquidity reduces fragmentation and simplifies how market participants route transactions. The tradeoff is operational risk: stakeholders warned that pooling settlement on one infrastructure could create systemic importance and lock participants into a particular platform, technology or vendor, reducing incentives to innovate and making the system vulnerable to dependence on a single operator.
Multiple competing networks would allow different business models and reduce dependence on any one infrastructure. Banks and other market participants could choose between platforms based on service quality and cost. However, respondents cautioned that competition between platforms could fragment liquidity if central bank money or collateral cannot move efficiently between them. Without enforceable interoperability standards, separate networks risked dividing liquidity, collateral, identity and compliance into new operational silos.
A third option—making central bank money available on a limited number of eligible networks operating under transparent admission criteria and common standards—emerged as a compromise many respondents favored. This model would balance platform choice with common requirements. The report notes, however, that the feasibility of providing central bank money settlement on more than one network while preserving Eurosystem control over that money still requires assessment. An eligible-network approach remains under study rather than an announced entitlement for operators to connect.
Neutrality and access rules will determine whether infrastructure can remain competitive
Respondents placed heavy emphasis on rules governing who can access the shared settlement layer. They sought objective, non-discriminatory admission criteria and a clear separation between common utility infrastructure and commercial services built on top of it. Client-facing services such as issuance, trading, custody and wallets were generally considered unsuitable for shared infrastructure because those are domains where providers should compete.
The concern that motivates this split is practical: a DLT operator that supplies common infrastructure while also selling services to users could undermine the neutrality of the infrastructure those users depend on. Either a Eurosystem-operated network or market-operated networks would need rules that preserve public authority control over central bank money and prevent discriminatory access. The International Capital Market Association, in an April submission to the consultation, favored multiple interoperable networks under harmonized standards, citing competition, concentration risk and market-led innovation as advantages over a single Eurosystem-operated platform.
Pontes operational expansion and Appia’s 2028 deadline shape the delivery roadmap
The infrastructure is already live. Pontes, the Eurosystem’s platform for settling tokenized asset transactions in central bank money, launched on September 21 with initial core services. It connects market DLT platforms with the Eurosystem’s TARGET Services, allowing wholesale tokenized assets to settle in central bank money rather than through private intermediaries.
In a keynote address on Thursday (October 29), ECB Executive Board member Piero Cipollone laid out expansion milestones for Pontes and Appia. Cipollone announced that Pontes will offer significantly longer operating hours by mid-2027 and move to 24/7/365 availability in 2028, with immediate settlement finality on the Eurosystem DLT platform planned as early as 2027. Cipollone also confirmed that T2S, the existing securities settlement platform, will continue operating alongside new tokenized infrastructures.
The Appia blueprint due in 2028 will contain findings, recommendations and principles for the wider ecosystem rather than prescriptive technical architecture.
Cipollone emphasized that Appia aims to develop an integrated European ecosystem for tokenized finance anchored in central bank money, with the consultation confirming broad market support and a willingness among respondents to contribute actively. The report notes that more complex cross-cutting testing is envisaged for 2027, and a forthcoming stakeholder call will cover tokenized deposits, payments, securities and shared network governance, with participation arrangements still to be communicated.
Cipollone noted that since March 30, the Eurosystem has been accepting marketable assets issued in central securities depositories using distributed ledger technology as eligible collateral for its credit operations. Whether assets outside currently eligible settlement systems can qualify, and under what criteria, remains under assessment. That unresolved question—how far the collateral framework will open to on-chain assets—will affect which tokenized instruments can interact with central bank money at settlement.
The BlockWest read. Lagarde’s exit concentrates successor risk in a process already constrained by competing stakeholder interests. The Eurosystem has not signaled a preference between network models, and the consultation report stops short of resolving the fundamental question of whether multiple networks can coexist without fragmenting liquidity and collateral. The next ECB president enters office with 18 months to operationalize a decision that the Governing Council has deferred. Whether Appia delivers a true blueprint or a framework permitting continued deliberation will determine whether European tokenized finance achieves integration or settles for managed competition.
The ECB Governing Council, which brings together the Executive Board and euro-area national central bank governors, remains the main decision-making body for Appia design. Lagarde’s successor will be appointed by the European Council by qualified majority on a Council recommendation after consultation with the European Parliament and the Governing Council, and that successor’s influence over the final architecture choices will depend on both Governing Council consensus and the terms on which market participants choose to operate. The next concrete signals will come from the 2027 cross-cutting testing campaign and the forthcoming stakeholder call on tokenized deposits, payments and network governance; participation arrangements are still to be communicated.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.