XRP hits $1.60 as CME short squeeze claim lacks timing support
XRP’s jump to a $1.60 intraday high on Sept. 22 has been credited by some traders to a short squeeze in CME’s regulated futures market, but the CFTC’s own positioning data show that squeeze happened days before the rally and on a different exchange. A parallel data set from Coinbase Derivatives barely moved over the same week, complicating any single-cause explanation for the price move.
- XRP hit an intraday high of $1.60 on Sept. 22 on roughly $7.4 billion in reported trading volume.
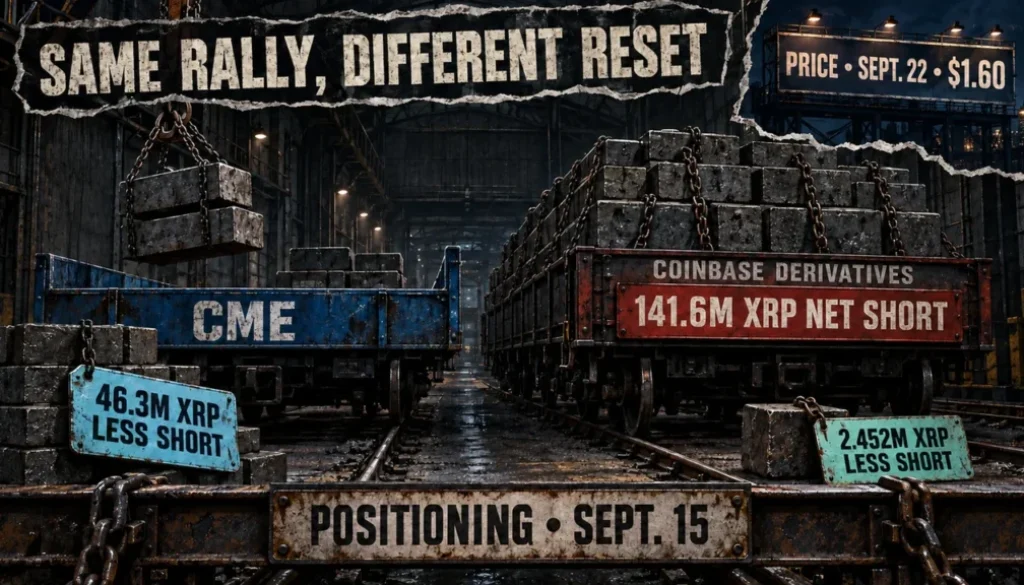
- CFTC data for Sept. 15 show CME leveraged funds cut their net short position by 46.3 million XRP in one week.
- Comparable Coinbase Derivatives positioning fell by only 2.452 million XRP and stayed near 141.6 million XRP net short.
- $7.4B reported XRP trading volume around the Sept. 22 price spike
- $1.60 XRP’s intraday high on Sept. 22, its rally peak
- 46.3M XRP-equivalent net-short cut by CME leveraged funds in one week
- 141.6M XRP still held net short by leveraged funds on Coinbase as of Sept. 15
XRP traded up to an intraday high of $1.60 on Tuesday, Sept. 22, with about $7.4 billion in reported volume, according to CryptoSlate. Some traders pointed to a short squeeze in CME’s regulated XRP futures as the driver, but the timing of the available positioning data undercuts that theory.
The Commodity Futures Trading Commission’s most recent Commitments of Traders snapshot was taken Tuesday, Sept. 15, and released Friday, Sept. 18. That is four days before the Sept. 22 price high, so the report cannot show what happened in futures markets during the rally itself.
CME leveraged funds cut net Short by 46.3 million XRP
The CFTC’s Sept. 15 data set shows leveraged funds in CME’s XRP future, which represents 50,000 XRP per contract, held 1,585 long contracts against 2,304 short contracts. That is a net short of 719 contracts, or 35.95 million XRP.
A week earlier, on Sept. 8, the same category reported 1,280 longs and 2,925 shorts, a net short of 1,645 contracts equal to 82.25 million XRP. The week-over-week change removed 926 contracts of net short exposure, or 46.3 million XRP.
Longs rose by 305 contracts while shorts fell by 621, so the move combined fresh buying with short covering. Total open interest fell by 509 contracts, or 25.45 million XRP, over the same week, consistent with traders closing positions rather than a pure directional bet.
Coinbase derivatives barely moved, still near four times CME’s Short
Coinbase Derivatives lists three separately reported XRP products: a standard future at 10,000 XRP per contract, and two smaller contracts labeled NANO XRP and NANO XRP PERP STYLE, each at 500 XRP per contract. Converted into XRP-equivalent terms, leveraged-fund net short exposure on the standard contract fell from 132.17 million to 128.52 million XRP, a reduction of 3.65 million.
The nano contract’s net short edged down by just 92,000 XRP. The perpetual-style contract moved the other way, with leveraged funds adding 1.29 million XRP of new net short exposure, offsetting part of the improvement in the other two products.
Combined across all three, Coinbase’s leveraged-fund net short fell from 144.0665 million to 141.6145 million XRP, a reduction of only 2.452 million XRP. That left Coinbase’s aggregate net short roughly four times larger than CME’s remaining 35.95 million XRP net short on the same date. The Coinbase perpetual-style product is a regulated, five-year cash-settled future using funding adjustments, which makes it structurally distinct from the unexpiring perpetual swaps common on offshore exchanges.
CFTC’s next snapshot, due Friday sept. 25, will cover the rally itself
CFTC Commitments of Traders reports generally reflect Tuesday positions and are released the following Friday at 3:30 p.m. Eastern time, per the agency’s release schedule. The tentative 2025 schedule lists Friday, Sept. 25, for the report covering Sept. 22, the day of XRP’s price high.
That release will show whether CME leveraged funds kept reducing their short position through the rally, or whether the Sept. 15 reset had already run its course. It will also show whether Coinbase’s much larger net short finally moved.
One gap the data cannot close: under CFTC rules, a market only appears in these reports once at least 20 traders hold positions at or above reporting levels, as described in the agency’s reporting-level filing. CME’s Micro XRP contract is tracked separately and falls outside the four contract codes compared here, so any positioning shift in that product remains unaccounted for.
The BlockWest read. Trading desks that treat CME’s Commitments of Traders data as a market-wide sentiment gauge are extrapolating from one venue to the whole book. Until Coinbase’s much larger net short actually moves, allocators leaning on the CME squeeze narrative to justify chasing XRP are pricing a story the derivatives data does not yet support on the exchange where the bulk of leveraged short exposure sits.
The Sept. 25 CFTC report covering Sept. 22 positions is the next concrete test of whether the CME reset extended into the rally, or whether Coinbase’s still-heavy net short remains the outlier that the current data cannot explain.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.