Coinbase supplies infrastructure for community banks to access stablecoin bridge services
Coinbase and payments platform Moov are enabling community banks to offer stablecoin services to their business customers without those customers having to leave their primary financial institution. The arrangement leaves critical questions unresolved about who controls fees, customer data, settlement destinations, and operational risk in the three-party ecosystem.
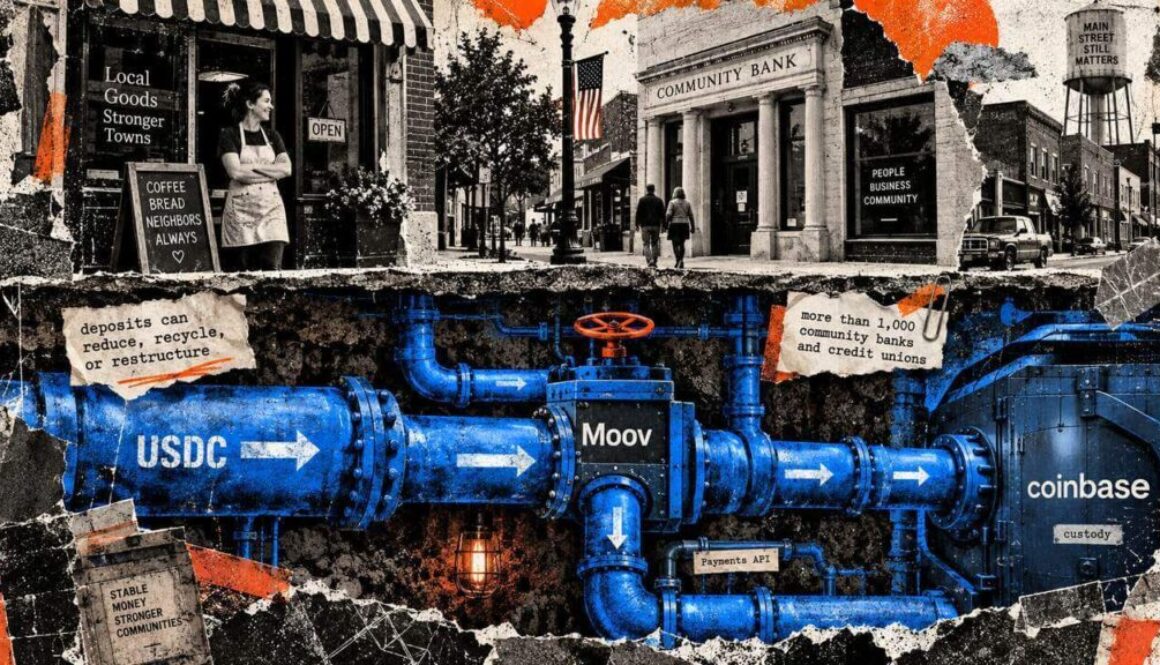
- Moov serves more than 1,000 community banks and credit unions, representing the potential distribution network for stablecoin integration.
- Coinbase will supply custodial wallet accounts and its Payments API to orchestrate stablecoin movement through Moov’s platform.
- The companies have not disclosed implementation timelines, live deployments, or which institutions are actively committed or in pilot phases.
- 1,000+ Community banks and credit unions in Moov’s current customer base
- Sept. 10 Date Coinbase and Moov announced their partnership integration
Coinbase and payments infrastructure provider Moov announced a partnership on September 10 to allow community banks and credit unions to embed stablecoin payment services into their existing customer relationships. Under the arrangement, Coinbase supplies the underlying custody and transaction infrastructure, Moov connects those tools to its bank customers’ systems, and the participating bank remains the face of the service to its business customers. Moov CEO Wade Arnold stated that businesses currently seeking to accept stablecoins have been forced to go outside their primary financial institution, creating an opportunity to bring the capability back into the bank’s existing payments experience.
The partnership reflects a broader industry trend toward embedding cryptocurrency services within traditional financial channels rather than requiring customers to navigate separate crypto platforms. By keeping the customer experience within the bank’s interface, the model aims to reduce friction and compliance complexity while expanding the types of payment flows that banks can support.
Three-Party Architecture Places Infrastructure Control With Coinbase
The partnership creates a stacked arrangement in which Coinbase’s CDP Custodial Wallet accounts hold the stablecoin funds and its Payments API directs the movement of those assets, while Moov embeds these tools into its platform that connects to bank and credit-union systems. The bank retains the primary customer-facing relationship. This design allows a business customer to experience a single bank-branded product even though three separate entities provide different layers of the underlying service.
Coinbase’s standard documentation describes a custodial-account model where crypto can enter an account, remain there as a held and reconciled balance, and exit through either fiat or crypto transfers. Separate custodial wallet documentation specifies that Coinbase provides custody for assets held in those accounts on behalf of the entity using the CDP platform. The structure gives Coinbase a material operational role within any payment chain that depends on both Moov’s platform integration and the participating institution’s customer interface.
This custody arrangement places significant infrastructure control with Coinbase, which will determine the technical parameters for stablecoin handling, transaction speed, and settlement mechanics. The bank’s ability to customize or override these parameters remains unclear from the partnership announcement.
Revenue Split, Data Rights, and Liability Terms Remain Undisclosed
The partnership announcement does not specify which stablecoins each institution will support, which blockchain networks will be enabled, who owns the custodial balances, or how fiat settlement will occur. Equally critical gaps remain in the commercial terms: the companies have not disclosed fees, revenue-sharing arrangements, customer data access rights, compliance responsibilities, or liability allocation.
Those operational details will determine whether the community bank retains economic leverage and control over the customer relationship. A bank’s authority over pricing, settlement destinations, customer data, and risk decisions will define how much value flows back to the institution versus to Coinbase and Moov. The split-control arrangement means community institutions can present stablecoin services to customers while Coinbase and Moov remain essential to the disclosed technology chain, but the actual distribution of power hinges on terms not yet made public.
In similar partnerships between traditional financial institutions and fintech platforms, terms around data ownership have often proven contentious, with disputes arising over which party can use customer payment information for competitive advantage or cross-selling purposes.
Regulatory Uncertainty Over Deposit Insurance and Stablecoin Status
A community bank offering stablecoin access does not change the legal status of the stablecoin itself or alter how customer protection rules apply. The Federal Deposit Insurance Corporation proposed in April 2026 that deposits held at banks as reserves backing a payment stablecoin would be insured as corporate deposits of the stablecoin issuer, subject to applicable insurance limits. Under that proposal, stablecoin holders would receive no pass-through deposit insurance, meaning customer funds converted into stablecoins could lose FDIC protection.
The FDIC’s proposal also draws a distinction between payment stablecoins and tokenized deposits. A financial instrument that meets the statutory definition of a bank deposit remains a deposit regardless of whether it uses tokenized technology or traditional recordkeeping. For a community institution, this distinction has consequences beyond consumer disclosure. A qualifying tokenized deposit remains the bank’s own liability on its balance sheet, while customer access to a third-party stablecoin can keep the payment experience inside the bank’s channel even as the customer’s converted funds may cease to be a deposit at that bank.
A Federal Reserve analysis published in December 2025 found that stablecoins can reduce, recycle, or restructure deposits depending on who purchases them, what assets are converted, and where stablecoin issuers place their reserves.
The Fed identified partnerships, custody services, settlement accounts, and white-label infrastructure as possible mechanisms for banks to remain connected to digital payment flows. The analysis also highlighted a deeper structural risk: stablecoins may separate the payment relationship from the deposit-funded lending model that banks have historically relied on to serve households and businesses. The Moov arrangement with Coinbase embodies both possibilities in a single product design, allowing a bank to retain the customer interaction and gain stablecoin capability without building its own crypto infrastructure, while also potentially routing stablecoin activity and associated balances away from that bank’s balance sheet.
First Live Deployments Will Reveal Actual Control of Economics and Data
The companies have provided no timetable for implementation, and the number of institutions in live, committed, or pilot phases remains unquantified. The initial bank deployments will supply the evidence missing from the public announcement. Adoption counts will demonstrate whether Moov’s network of more than 1,000 community banks and credit unions actually converts into demand for stablecoin services, or whether the integration remains a capability that most institutions do not activate.
Supported assets, account-ownership structures, and settlement paths will show whether stablecoin activity flows value back to the participating bank or routes it toward larger custodial and settlement institutions. Commercial terms disclosed to participating banks will be equally revealing. Pricing, revenue sharing, data access, compliance allocation, and liability provisions will determine whether community banks earn revenue from the service or primarily supply distribution while Coinbase and Moov capture the economics.
Market observers will also monitor whether this model influences regulatory treatment of bank-led stablecoin services, since the arrangement preserves a community bank’s role in customer relationship management while outsourcing the complex infrastructure components to established crypto and fintech providers.
The partnership structure offers community banks a route to remain visible in the stablecoin payment experience, but whether they retain meaningful economic control, access to customer data, and operational decision-making power will depend on terms that the companies have not yet disclosed publicly and will likely only emerge as institutions begin live deployments.