Study finds Ethereum arbitrage enables network developers to gain $5 in revenue for every $1 of tokens burned by the system
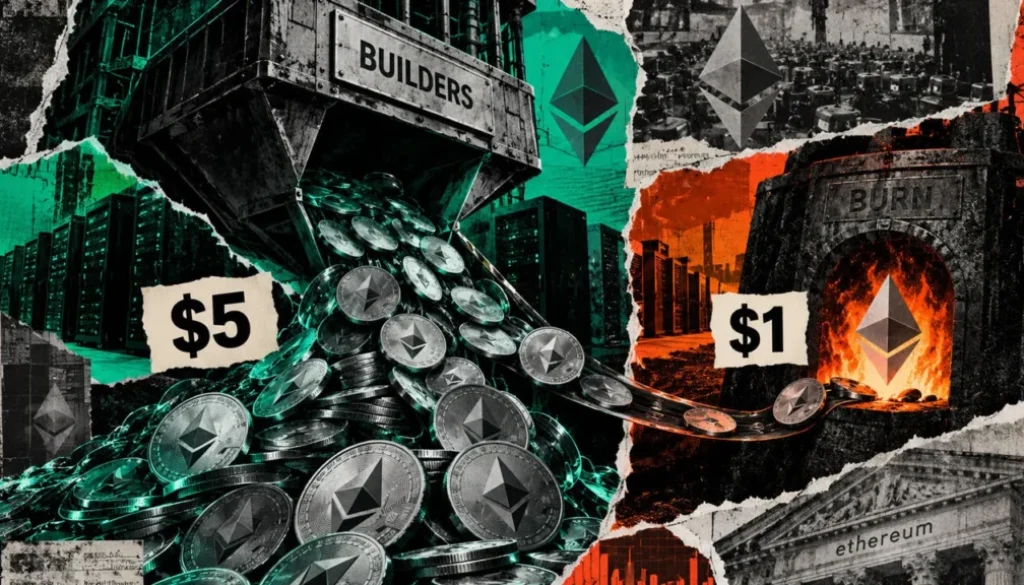
A new analysis of Ethereum’s arbitrage activity reveals how value flows between block builders, validators, and traders, with builders capturing $5.24 in receipts for every $1 of fees burned by the protocol. The findings highlight critical gaps between gross builder revenue and actual profit, a distinction that matters for understanding Ethereum’s economic incentives and token supply dynamics.
- Builders collected $5.24 in receipts for every $1 in fees burned during the 30-day measurement period ending August 29, 2026.
- Of measured arbitrage surplus, 49.3% went to block assembly, 9.4% to burned fees, and 41.3% to trading operators.
- The study did not measure how much builder revenue flows onward to validators, creating uncertainty about actual builder profit margins.
- $5.24 Builder receipts per $1 of protocol fees burned during measurement period
- 49.3% Share of arbitrage surplus directed toward block assembly activity
- 41.3% Share of arbitrage surplus retained by trading operators and searchers
- 9.4% Share of arbitrage surplus from burned fees, lowest allocation segment
Blockchain data provider Bitquery released a 30-day analysis examining how Ethereum’s arbitrage activity distributes value across network participants. The study, verified on August 31, 2026, quantifies the economic incentives operating within Ethereum’s architecture following the transition to proof-of-stake and the adoption of external block builders. The findings reveal a complex value chain where multiple parties compete for and extract different portions of transaction surplus generated by trading activity.
Builders earn substantially more than protocol fees burned
The central finding shows an asymmetry between builder receipts and protocol fee destruction. Builders collected approximately $5.24 in receipts for every $1 in fees burned by the network, indicating that arbitrage activity generates substantial value flowing to block assemblers compared with tokens removed from circulation. This ratio emerges from the sampled arbitrage surplus, where 49.3% directed toward block assembly significantly outweighed the 9.4% going to burned fees.
The distinction reflects how Ethereum’s fee mechanism operates. Base fees are destroyed by protocol rules under EIP-1559, while priority fees paid for transaction inclusion flow to block producers. Arbitrage transactions typically generate both types of fees, but the split between them does not correlate mechanically with builder revenue. A builder may receive substantial payments from arbitrageurs competing for transaction ordering without experiencing a corresponding increase in burned ETH, since priority fees and base fees operate through separate mechanisms.
Ethereum’s separation of these fee components after the Shanghai and Dencun upgrades created conditions where block builders and validators operate as distinct economic actors. This separation enabled the competitive block-building market that now characterizes Ethereum’s production environment. However, it also created opportunities for value capture at multiple layers, with builders occupying a crucial position between searchers and validators.
Gross builder receipts mask significant payments to validators
Bitquery’s measurement of gross builder receipts omits a critical expense: payments builders must forward to validators for proposing blocks. Builders do not retain all incoming revenue; they typically execute validator payments as transactions at the end of their constructed blocks. Without accounting for these onward transfers, the $5.24 figure overstates what builders actually profit.
Builders do not retain all their receipts, however. They must pay validators for proposing blocks, which represents a significant portion of the builder’s incoming revenue.
Bitquery analysis
The study did not measure what fraction of builder receipts flow to validators, representing a significant gap for participants evaluating true profitability in block building. This omission is particularly important given that validator payments typically constitute the largest operating cost for builders and directly determine their competitive position within the builder market.
Research from academic institutions and blockchain monitoring firms has shown that validator payments often absorb 80 to 90 percent of builder revenue in competitive conditions, with the spread dependent on overall network activity and builder competition. Matching sampled trading payments to subsequent validator transfers would require detailed transaction-level data that the Bitquery study did not collect. This distinction matters because a builder receiving high arbitrage payments may immediately pass much of that value onward, limiting actual profit margins and potentially misrepresenting the economic incentives driving block construction.
Arbitrage May differ from network-wide Fee dynamics
The study’s finding that burned fees represented only 9.4% of measured arbitrage surplus does not indicate Ethereum’s overall burn rate across all transaction types. Arbitrage transactions possess different fee characteristics than typical transfers, smart contract interactions, or other activity. The allocation observed in this sample may not generalize to the entire network, since arbitrageurs have higher willingness to pay for transaction ordering than ordinary users.
For token holders evaluating the supply effect of network activity, the relevant measurement is ETH destroyed during a specific period compared with ETH created during that same period, not the ratio of arbitrage surplus components. This approach isolates the actual deflationary impact of transaction fees from the revenue distribution among protocol participants.
Bitquery’s analysis covered Ethereum, BNB Chain, Base, Arbitrum, and Polygon for 12 months through August 29, 2026, but excluded Optimism and Solana. The study used fixed reference prices for the monthly comparison that differ from prices in historical annual series, and wallet reconciliation can reduce apparent earnings further. Establishing whether increased network activity strengthens Ethereum’s supply-reduction case would require comparable burn and issuance measurements tracked consistently over time.
A subsequent analysis would need to measure builder payments forwarded to validators and maintain consistent coverage, time periods, and accounting methods to reliably show whether a busier network produces higher retained revenue for builders, reduces token supply through increased burn, or accomplishes both simultaneously. Understanding these dynamics is essential for predicting long-term token supply trends and evaluating Ethereum’s value proposition as a blockchain platform.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.