How Bitcoin’s Growing Holdings Fail to Boost Shareholder Returns
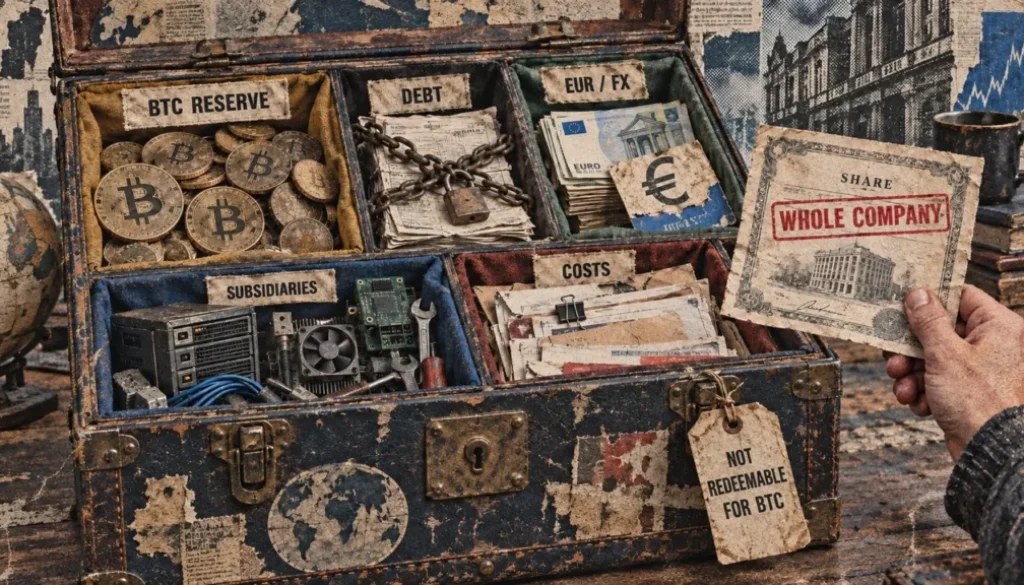
Bitcoin treasury companies can grow their coin holdings while shareholder value stagnates, a dynamic exemplified by Capital B’s recent 12% increase in Bitcoin reserves paired with virtually flat Bitcoin per share. Understanding how management finances acquisitions through share dilution, debt, and warrants is critical for investors evaluating these vehicles against direct Bitcoin ownership or passive products.
- Capital B increased Bitcoin holdings from 3,145 BTC to 3,521 BTC between August 17 and September 7, a 12% increase.
- Satoshis per diluted share remained nearly flat at 736.4 to 736.6 despite the 12% Bitcoin reserve growth due to simultaneous share dilution.
- Capital B finances Bitcoin purchases through share sales with warrants, Bitcoin-denominated convertible debt, and other instruments that expand the shareholder base.
- 3,521 BTC Capital B’s total Bitcoin reserve as of September 7, 2026
- 12% Growth in both Bitcoin holdings and diluted share count over three weeks
- €62.2M Capital B’s net loss in 2025, primarily from Bitcoin impairment charges
- €4.1M Estimated annual treasury-business operating costs for Capital B
Capital B, a French Bitcoin treasury company trading on Euronext Growth Paris, demonstrates a core tension in corporate cryptocurrency holdings: growing the reserve while maintaining per-share value requires financing on terms that don’t dilute existing owners. The company’s recent filings show that when Bitcoin reserves expand by roughly 12% in three weeks, but Bitcoin per diluted share barely moves, the mathematics reveal that new shares and new claims on the company expanded at nearly the same rate as the coins themselves. This dynamic forces investors to evaluate whether management is creating value or merely spreading existing assets across more ownership stakes.
Treasury companies have emerged as an alternative to direct Bitcoin ownership or spot exchange-traded funds, appealing to institutional investors seeking corporate structure and management oversight. The model depends on the premise that company staff can acquire Bitcoin cheaper than markets, or deploy it more efficiently, thereby generating returns superior to passive holdings. However, the financing methods used to build reserves significantly affect whether this premise holds true in practice.
How financing method determines whether shareholders gain or lose
When a treasury company buys Bitcoin, it must answer a foundational question: who pays for it, and what claims do they receive in return? Three primary methods exist, each with different effects on existing shareholders. Using surplus operating cash avoids creating new shares or debt but redirects money that could serve other purposes. Selling new shares brings fresh capital but divides ownership across a larger pool. Borrowing preserves existing shareholders’ ownership percentage but creates an obligation that must be met regardless of investment performance.
The impact on per-share Bitcoin depends entirely on the price at which new shares are issued. A simplified example illustrates the principle: if a company holds 100 BTC in 100 shares (one BTC per share), it could issue ten new shares at €150,000 each and purchase 15 additional coins, leaving 1.0455 BTC per share across 110 shares. The same company issuing ten shares at €80,000 each would purchase only 8 coins, leaving 0.9818 BTC per share. The difference between value creation and value destruction hinges on whether investors pay a premium to the existing per-share Bitcoin value. Once that premium evaporates, issuing shares becomes dilutive.
This distinction separates treasury companies from passive Bitcoin vehicles. An exchange-traded fund holding Bitcoin owns the same asset regardless of fund size; share dilution is mathematically impossible because new investor purchases acquire existing Bitcoin at current market prices. A treasury company, by contrast, must negotiate the terms of each financing round, making execution risk a permanent feature of the model.
Capital b’s Warrant and convertible debt structure creates layered Dilution risk
Capital B does not rely solely on direct share sales. Its August 28 financing package attached four warrants to each share sold, with different exercise prices and five-year maturities. Warrants give holders the right to buy future shares at a predetermined price, creating a claim on capital that isn’t immediately in the company’s account. If exercise becomes attractive when Bitcoin’s price rises, warrant holders will supply additional cash; if it becomes unattractive, they may never exercise, and the dilution never materializes. That uncertainty makes estimating the true dilution burden complex.
Capital B also uses Bitcoin-denominated convertible debt, described in its annual results presentation. This structure creates an additional layer of complexity: when the debt’s repayment obligation tracks Bitcoin’s value, a more valuable reserve can come paired with a more expensive obligation in euros. The company’s 2025 consolidated accounts reported a €62.2 million net loss, with €53.9 million attributable to Bitcoin impairment charges. Separately, the company identified approximately €4.1 million in annual treasury-business operating costs, a fixed burden that must be met whether the Bitcoin reserve grows or shrinks.
These operating costs matter because they represent a permanent drag on performance relative to holding Bitcoin directly. A treasury company must service staff, maintain compliance infrastructure, pay audit fees, and manage investor relations. These expenses reduce returns below the passive Bitcoin alternative even before considering dilution. For Capital B, €4.1 million annually against a 3,500 BTC reserve represents approximately 0.05% annual cost, but over time compounding effects accumulate.
French accounting and euro funding create different investment exposures
Capital B operates under French accounting rules, which treat unrealized Bitcoin gains through balance-sheet entries while unrealized losses may require provisions charged against earnings. This asymmetric treatment differs from US GAAP’s fair-value measurement approach, which recognizes valuation movements in net income, and from IFRS frameworks used by other European companies. The accounting method shapes how reported results move with Bitcoin’s price, even when no coins are sold.
The company also raises capital and reports figures in euros, not dollars. Bitcoin’s price is dominated by dollar quotations, but the euro cost of acquisition depends on both the dollar price and the euro-dollar exchange rate. If Bitcoin holds steady at $100,000, a strengthening dollar could raise the euro cost from €80,000 to €100,000 without any change in the Bitcoin price itself. This currency exposure adds a separate risk dimension not present for US dollar-funded treasury companies like MicroStrategy or Marathon Digital.
European regulatory frameworks for cryptocurrency custody and treasury management also differ from US rules. Euronext Growth Paris imposes different disclosure standards than Nasdaq or NYSE, and Capital B’s choice to operate under French law rather than incorporating in a crypto-friendly jurisdiction like Delaware introduces additional governance complexity. For European investors, however, familiarity with local accounting and regulatory norms may reduce perceived risk relative to US-listed peers.
Shareholders considering Capital B or similar European treasury vehicles must evaluate management’s ability to raise financing on terms that leave existing owners better off after deducting corporate expenses and obligation repayments. The company’s Bitcoin reserve size is only one input; the share count reveals how widely ownership is divided, and the financing contracts show who must be paid. Capital B’s next major test will be whether warrant holders exercise their rights, and at what Bitcoin price that exercise occurs, as this will determine the actual dilution impact of the August 28 financing package. Investors should compare the ongoing dilution burden and operating costs against the simplicity and tax efficiency of holding Bitcoin directly through spot ETFs or custodial services.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.