The US treasury turns to stablecoins for short-term debt financing, yet they cannot resolve its $28 billion long-bond crisis
The U.S. Treasury’s reliance on stablecoins for debt funding is real but severely limited by regulatory constraints that channel reserve demand only into short-maturity instruments. Stablecoin growth cannot directly address the government’s long-bond financing challenge, a distinction that matters for understanding both fiscal markets and digital-asset price dynamics.
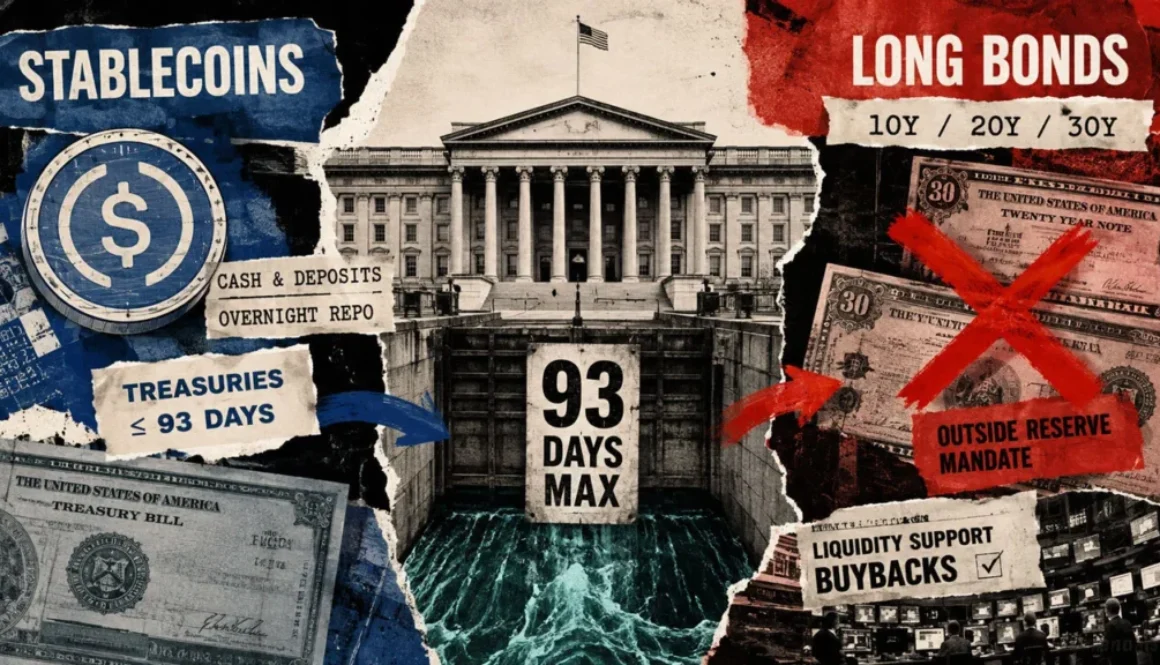
- GENIUS Act requires stablecoin reserves in Treasuries maturing within 93 days or less, excluding all longer-duration bonds.
- Treasury announced at least doubling maximum buyback sizes to $28 billion across 10-to-30-year sectors starting September 9.
- A $3.5 billion stablecoin inflow lowered three-month bill yields by approximately 5 basis points at trough, with no spillover to longer maturities.
- 93 days Maximum maturity for direct Treasury reserve assets under GENIUS framework
- $71.9B Circle USDC reserve assets as of July 31, 2025
- 5 bps Three-month Treasury yield compression from $3.5B stablecoin inflow
- $28B Planned aggregate capacity for long-end buyback operations after doubling
Stablecoin demand is beginning to shape U.S. government debt markets, but the structure of regulatory approval creates a sharp dividing line in how that demand operates. The federal framework governing permitted payment stablecoins channels reserve holdings exclusively into cash-like assets and Treasury securities with 93 days or less remaining to maturity. Meanwhile, the Treasury Department announced on August 19 that it would at least double the maximum size of liquidity-support buybacks in the 10-to-20-year and 20-to-30-year nominal sectors, effective September 9. These two developments expose a fundamental mismatch: stablecoin reserves can reinforce demand for bills and short-term financing, but they remain structurally excluded from supporting longer-duration bonds where the government faces different pressure.
The 93-Day Regulatory Wall Confines Stablecoin Treasury Demand
The GENIUS Act, enacted in July 2025, requires permitted stablecoin issuers to maintain identifiable reserves of at least one dollar for every token in circulation. The eligible reserve menu is extensive on paper but narrow in duration: U.S. currency, Federal Reserve balances, withdrawable bank deposits, Treasuries with an original or remaining maturity of 93 days or less, qualifying overnight repo and reverse repo, government money-market funds, regulator-approved similarly liquid federal assets, and qualifying tokenized versions. A newly issued 10-year note or 30-year bond falls completely outside this direct reserve category.
The framework remains a work in progress. While the law took effect in July 2025, its general effective date is the earlier of January 18, 2027, or 120 days after final implementing rules are issued. The Office of the Comptroller of the Currency proposed its framework in February and stated that the final OCC rule would arrive by November. Current issuer portfolios demonstrate how short-duration reserves function in practice, but they do not yet prove that all issuers operate under a completed federal regime.
Circle’s USDC holdings illustrate the boundary. The issuer reported $71.904 billion in reserve assets on July 31, with $60.717 billion held in the Circle Reserve Fund. Of that amount, $52.723 billion was invested in overnight Treasury repo and $7.179 billion in direct Treasury securities, every one of which matured by September 22. Another $11.187 billion sat outside the fund in regulated bank cash. Both categories kept Circle’s portfolio duration firmly at the front end of the curve.
Stablecoin Growth May Displace Existing Bill Demand Rather Than Create New Treasury Purchases
The scale of stablecoin reserves matters less than where the dollars originate, a distinction that complicates claims about new Treasury demand. During the second quarter of 2025, Circle customers minted $83.004 billion of USDC and redeemed $86.784 billion, leaving $3.780 billion in net redemptions. Quarterly circulation remained 19% above the year-ago level but stood roughly $2 billion below December 2024 balances. Gross issuance measures activity, yet net growth alone leaves the source of those dollars unidentified.
The Treasury Borrowing Advisory Committee, which advises the government on debt management, has drawn the same analytical line. Stablecoin issuance can add short-maturity Treasury demand, but part of that effect may simply displace purchases that would have occurred through bank deposits, money-market funds, or other cash-like instruments already financing bills. Demand from new offshore dollar users would be more additive to Treasury’s borrowing base, but official data do not yet quantify that proportion. Stablecoins can therefore change which balance sheet holds a bill without supplying Treasury with a wholly new lender for every dollar of token growth.
Treasury’s Long-End Buyback Program Operates Outside the Stablecoin Reserve Channel
The Treasury Department’s expanded buyback program targets a separate market segment with no direct stablecoin participation. Operations focus on off-the-run nominal coupons in the 10-to-20-year and 20-to-30-year sectors, with the department describing the purpose as liquidity support for older securities that trade less readily than newly issued bonds. A tentative calendar lists seven affected operations: September 10, September 24, October 1, October 8, October 15, October 27, and November 4.
Raising each operation’s maximum from $2 billion to at least $4 billion lifts aggregate capacity from $14 billion to at least $28 billion across those seven operations. That figure represents a ceiling; Treasury’s guidance sets the minimum at zero and permits the department to accept less than the maximum when offers prove unattractive. The program differs fundamentally from quantitative easing. Treasury retires securities it accepts and finances buybacks like other government spending, meaning each dollar bought back requires another dollar of Treasury issuance. Stablecoin reserves never enter the long-bond buyback as direct purchasers because the GENIUS framework excludes longer-maturity assets entirely.
Empirical Evidence Shows Stablecoin Inflows Compress Bill Yields Without Spillover to Long Bonds
Research from the Bank for International Settlements reinforces the maturity divide. Using data through March 2026, a BIS working paper found that a $3.5 billion stablecoin inflow lowered three-month bill yields by 0.71 basis points on impact, about 4 basis points within 10 days, and roughly 5 basis points at the estimated trough. The effect strengthened under market stress and bill scarcity conditions.
Longer maturities showed limited or no spillover in the same research. That pattern aligns directly with the assets issuers purchase: cash placed into securities maturing within weeks can compress bill yields while leaving investors to bear duration risk in 10-, 20-, and 30-year debt. The current Treasury yield curve confirms this boundary in real time. On August 28, Treasury data put the 10-year yield at 4.73%, the 20-year at 5.21%, and the 30-year at 5.22%. Each maturity sits far beyond the GENIUS ceiling for direct Treasury reserve assets, locating the portion of the curve where a direct stablecoin bid is structurally absent.
Bitcoin’s Connection to Stablecoin Flows Remains Indirect and Uncertain
For Bitcoin, any connection to stablecoin growth or long-end Treasury operations runs through broader financial conditions rather than a direct reserve mechanism. Long-term Treasury yields influence credit costs and discount rates applied to risky assets, while better trading conditions in older bonds can improve overall market functioning. A larger bill-buyer base can support the Treasury’s front-end financing. Those links create a possible macroeconomic channel, not a mechanical price signal tied to stablecoin flows.
A stablecoin inflow may compress bill yields without lowering long-term rates. A Treasury buyback may improve liquidity without reducing net borrowing. Bitcoin can respond to changes in rates, dollar liquidity, and risk appetite while moving for many unrelated reasons simultaneously.
The measurable conclusion is narrow: stablecoins can become a larger source of demand for Washington’s short-term bills, especially when growth represents genuinely new dollar demand from offshore users. The long-bond market continues to depend on investors willing to hold duration, leaving the Treasury’s liquidity operations and any Bitcoin response to financial conditions separate from the regulated stablecoin reserve bid. The key open question is whether second-quarter USDC net redemptions signal a trend toward smaller reserve bases or represent normal portfolio churning, a distinction that will determine whether stablecoin demand materially expands bill financing as 2026 approaches.