How GENIUS Might Expose Digital Currencies to Rapid Blockchain Network Bank Runs
A new Federal Reserve analysis shows how blockchain network congestion can trigger coordinated redemptions of stablecoins even when they remain fully backed by reserves. The finding exposes a gap in the GENIUS Act’s regulatory framework, which polices stablecoin issuers but leaves public blockchain capacity and pricing outside its direct control.
- Federal Reserve economists modeled how transaction fee spikes can erode network effects and shift individual exits into coordinated redemptions, using data from November 2017 through December 2025.
- A one-standard-deviation increase in gas fees of $10.83 was associated with a roughly 0.9 percentage-point rise in weekly stablecoin redemptions when network effects were weak, per the Fed’s empirical panel.
- The GENIUS Act mandates one-to-one reserve backing and issuer oversight but sets no explicit price or capacity standards for the public blockchains that carry stablecoins, leaving a regulatory blind spot.
- $147.3B Ethereum stablecoin supply as of late August 2026, compared to Tron and Solana
- 100% Minimum reserve requirement under GENIUS for payment stablecoin issuers
- 0.9pp Rise in weekly redemptions per $10.83 gas increase when network effects were low
- Jan. 18, 2027 Expected effective date for GENIUS issuer licensing framework
A Federal Reserve staff paper dated June 2, 2026 and updated August 31, 2026 maps an overlooked vulnerability in digital dollar regulation: a perfectly backed stablecoin can become economically unusable if the blockchain carrying it becomes too congested to afford. The study combines theoretical modeling with empirical evidence from five stablecoins across multiple networks, demonstrating how fee pressure can unwind network effects and trigger sudden mass redemptions even without any deterioration in reserve quality. The analysis surfaces a structural gap as the Treasury Department prepares to implement the GENIUS Act, the new federal framework for payment stablecoin issuers, with a licensing regime expected to launch January 18, 2027.
Stablecoins have grown into a critical piece of blockchain infrastructure, particularly on Ethereum where they facilitate trillions of dollars in annual settlement volume across decentralized finance, custody platforms and institutional services. Yet their utility depends entirely on the underlying network’s ability to process transactions at reasonable cost, a factor largely beyond the control of coin issuers. This structural dependency has become more apparent as blockchain networks have scaled, with periods of congestion creating barriers to access even for tokens with fortress-like reserve backing.
How Congestion Erodes Payment Network Value Without Touching Reserves
Traditional stablecoin risk analysis centers on issuer solvency: if reserves weaken or become illiquid, rational users rush to redeem before others do. The Federal Reserve economists deliberately removed that mechanism from their model to isolate a different failure mode.
The fragility instead emerges from the interaction between rising transaction fees and declining payment-network effects.
People value a payment asset because others accept and use it. Under congested network conditions combined with weak network effects, a threshold emerges beyond which the incentive structure flips: higher fees reduce usage, reduced usage makes the token less attractive, and the weakening network then gives more holders reason to exit. The paper finds this dynamic can shift individual redemptions into coordinated, abrupt outflows purely through market mechanics rather than fundamental distress at the issuer level.
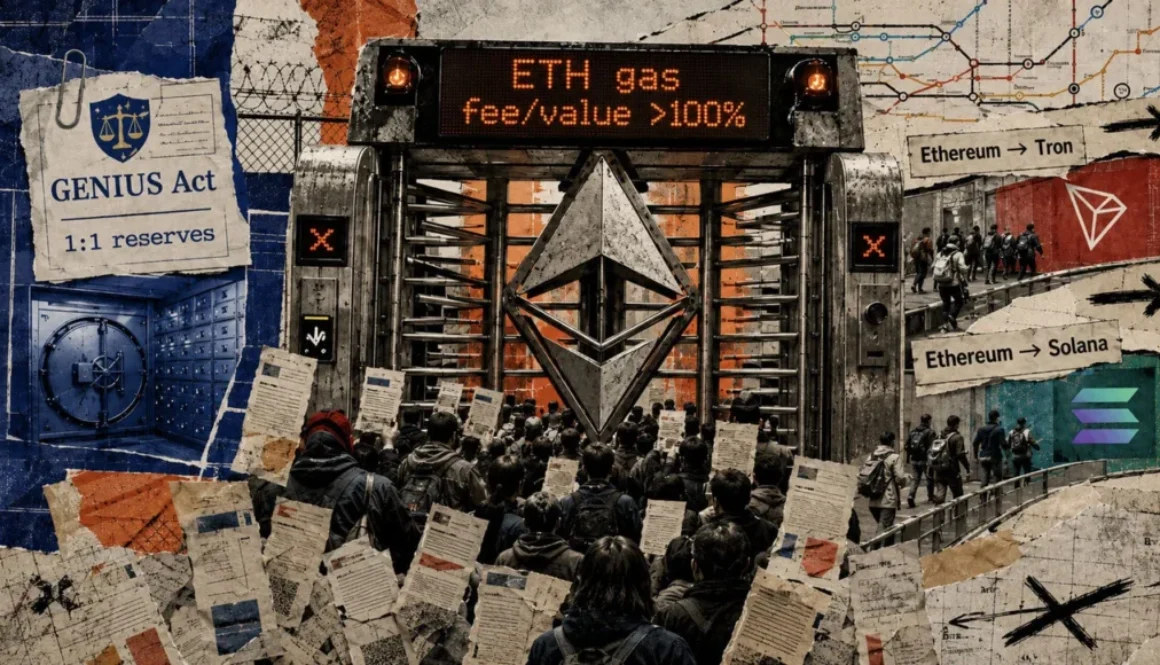
The empirical evidence comes from an unbalanced weekly panel spanning five stablecoins from November 2017 through December 2025. The starkest pattern emerged from 2021 through 2025: for below-median USDC transfers, the fee-to-value ratio at the 75th percentile frequently exceeded 100 percent, meaning transaction costs consumed more than a transfer’s entire value. For above-median transfers, this ratio almost never surpassed 5 percent. During expensive periods, a single network fee could exceed the dollar amount of many small transfers, effectively rationing access by payment size even while the token remained redeemable at par.
This dynamic presents a novel regulatory challenge: traditional payment system oversight typically focuses on issuer health and reserve adequacy. Stablecoin issuers themselves have limited leverage over blockchain congestion, which emerges from network-wide demand and supply dynamics. An issuer cannot unilaterally reduce transaction fees or expand network capacity, creating a mismatch between regulatory authority and practical control over system resilience.
The GENIUS Framework Addresses Issuer Risk But Not Network Risk
The GENIUS Act imposes strict operational requirements on payment stablecoin issuers: one-to-one reserve backing in specified liquid assets, mandatory public redemption procedures, monthly regulatory reporting, examination, certification and supervisory standards covering capital, liquidity, diversification, operations and information technology. These rules directly address critical failure modes including weak assets, opaque redemption terms, undercapitalization and operational breakdown.
The framework gives regulators clear authority over the entity that creates the dollar token, but leaves base-layer blockchain pricing and capacity outside its explicit stablecoin provisions.
Treasury’s August 17 implementation proposal, published in the Federal Register on August 18, focuses on section 3’s restrictions governing who can offer or sell payment stablecoins in the United States. Comments close October 19, with the issuer licensing regime expected to take effect January 18, 2027 and the broader digital asset service provider restrictions expected July 18, 2028. The regulatory text distinguishes direct peer-to-peer transfers from compensated services such as exchanges and custodians that qualify as digital asset service providers. This division allocates compliance duties but does not resolve the underlying economics: a reserve can remain fully liquid while a user still confronts a transaction fee larger than the intended payment, placing the gap between reserve quality and network usability outside the rule’s explicit scope.
Cross-Chain Reallocation Signals Where Stress First Appears
The Federal Reserve analysis identifies which participants experience congestion pressure first and where market rebalancing occurs. Using a database of 1,230 matched USDT transfers across Ethereum and Tron from May 2020 through December 2025, the researchers found that an increase of one dollar in lagged gas fees on Ethereum was associated with 3 to 4 percent more net matched value migrating from Ethereum to Tron. The average matched transfer in this cohort was approximately 176 million dollars, indicating that large intermediaries shift liquidity toward cheaper rails when Ethereum becomes expensive.
The ordering of pressure matters for policy. Small self-custody users feel congestion first: they may delay payments, batch transfers, move to an exchange or exit the chain rather than absorb a fixed network charge. Visible balance movements come next from larger intermediaries including exchanges, market makers, bridges and corporate treasurers, which move enough liquidity to alter chain-level circulation. That rebalancing can test the routes and intermediaries that support stablecoin inventory when users want to transact.
A snapshot taken shortly before drafting showed stablecoin supplies of roughly 147.3 billion dollars on Ethereum, 93.2 billion on Tron and 15.7 billion on Solana, with Ethereum experiencing calm network conditions at 0.127 to 0.128 gwei gas and transfer costs around two cents.
Cross-chain migration patterns also reveal how stablecoin markets already operate as a multi-network system. When one blockchain becomes expensive, users and institutions respond by redeploying capital to cheaper alternatives rather than exiting stablecoins entirely. This substitution effect means network congestion does not necessarily destroy stablecoin value but rather reallocates it, potentially creating winners and losers among different blockchain ecosystems and raising questions about whether regulatory frameworks designed for single-network issuers adequately address multi-chain dynamics.
The Federal Reserve paper frames the blockchain congestion problem as a monitorable risk rather than an imminent event, leaving regulators and market operators to watch fee-to-transfer-value ratios by transaction size, abrupt changes in chain-level stablecoin circulation, matched cross-chain flows and exchange wallet imbalances as early warning signals. Treasury’s implementation process remains open and choices can still change before the January 2027 effective date, creating an opportunity for policymakers to clarify whether the GENIUS framework will address base-layer resilience alongside issuer soundness or whether the next major stress episode may reveal a sound dollar token with inadequate routes of access to it.