
Bitcoin needs to absorb $47 billion in additional profitable supply to reach its next $80,000 milestone
Bitcoin’s path to $80,000 and beyond depends on whether new buyer demand can absorb $47 billion in newly profitable supply without triggering a cascade of profit-taking. Economic data releases in September and the direction of US Treasury yields will determine whether the market has sufficient capital inflows to overcome this structural headwind.
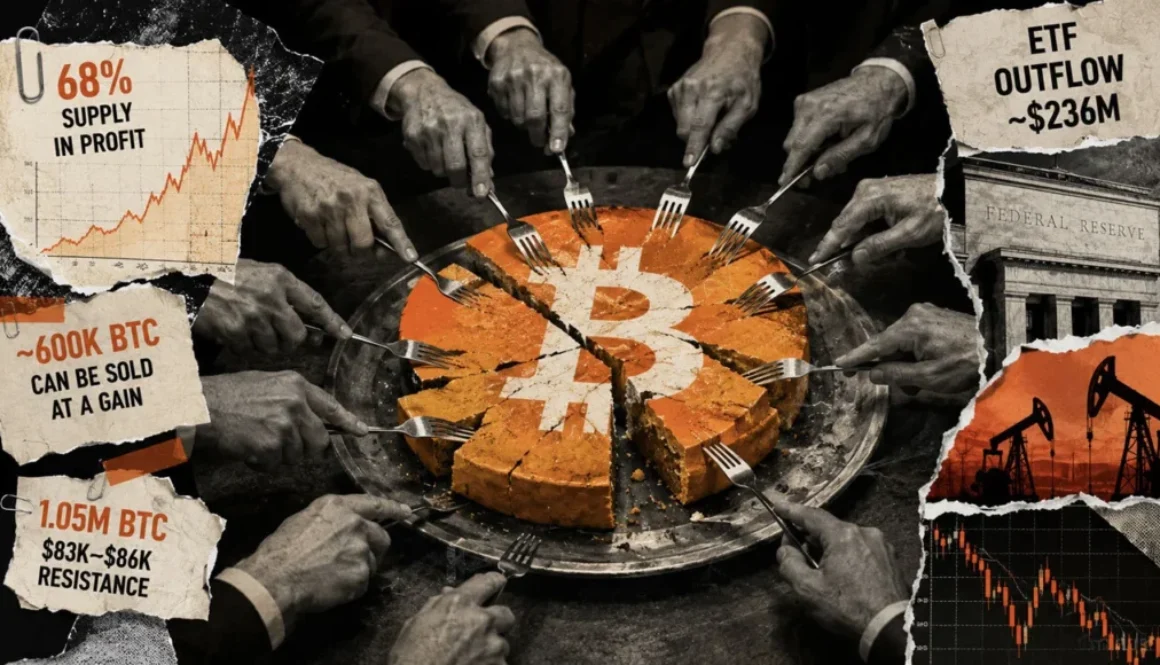
- 68% of Bitcoin’s circulating supply sits in profit at current prices, up from 65% in May, representing 600,000 additional BTC worth $47 billion.
- Long-term holders have concentrated 1.05 million BTC between $83,000 and $86,000, creating a resistance zone tied to their breakeven and target exit levels.
- US spot Bitcoin ETFs averaged $290 million daily inflows during August’s rally but posted $236 million in outflows this week, signaling weakening institutional demand.
- $47B Worth of newly profitable Bitcoin supply that could face selling pressure
- $290M Average daily Bitcoin ETF inflows during August’s rally toward $80,000
- 1.05M BTC held by long-term holders between $83,000 and $86,000 resistance
- $236M Bitcoin ETF outflows posted this week as price declined
Bitcoin is trading near $77,381 while carrying substantially larger profit-taking pressure than when it last visited this price level four months ago. According to on-chain analysis from Glassnode, 68% of Bitcoin’s circulating supply now sits in profit, up from 65% in May, creating a two-layer absorption challenge for buyers seeking to push prices higher. The expansion of profitable supply reflects both newly profitable short-term holders who accumulated during summer consolidation and long-term holders positioned near their breakeven costs at higher price levels.
Summer Consolidation Built Support and Supply Risk Simultaneously
From June through August, Bitcoin’s sideways trading between roughly $60,000 and $71,000 attracted fresh buyers at progressively lower price levels. This accumulation steadied the market’s floor but simultaneously created a larger pool of holders with real gains to protect as price advances. Short-term holder cost basis settled near $71,000, meaning buyers from that range are already profitable at today’s prices without Bitcoin needing to reach new highs.
Roughly 600,000 additional BTC entered profitable territory compared to May, an amount worth approximately $47 billion at current prices that could be sold for gains before Bitcoin reaches its next major resistance band. This supply expansion represents one of the largest concentrations of accessible profit-taking opportunities in recent market history.
Long-term holders have concentrated supply around $83,000 to $86,000, where roughly 1.05 million BTC sits held by investors who maintained positions through the entire correction and now seek to exit whole. This concentration reflects a common pattern in cryptocurrency markets where holders establish psychological exit targets aligned with breakeven or target returns. If Bitcoin reaches this level without sufficient absorption of supply, profit-taking could accelerate quickly.
ETF Demand Fails to Match August’s Rally Momentum
US-traded spot Bitcoin ETFs pulled in seven-day average inflows of $290 million per day during August’s rally toward $80,000, representing real capital that supported the price advance. The introduction of spot Bitcoin ETFs in January 2024 significantly altered market structure by allowing traditional investors easier access to Bitcoin exposure without managing private keys or custodial arrangements. This regulatory breakthrough removed a major friction point that previously limited institutional participation.
However, secondary-market turnover on those same ETFs remained near $3 billion per day throughout the period, a level Glassnode characterizes as well below prior expansionary phases when broader trading activity typically accompanies durable moves higher. This disparity between inflows and trading volume suggests that many new participants are establishing positions but not actively managing them. This week’s $236 million in ETF outflows, led mostly by IBIT, marks the first substantive test of whether sustained inflows can absorb the expanded profit overhang. Strong capital inflows without corresponding trading volume can indicate shallow conviction among new entrants or reluctance to commit large amounts at elevated prices.
The macro backdrop that enabled August’s rally has inverted significantly since then, with US Treasury 10-year yields climbing back near 4.8% after briefly touching 4.6% in mid-August. Higher yields reduce the opportunity cost advantage Bitcoin holds relative to risk-free assets and typically pressure alternative investments.
September Economic Data Will Determine Supply Absorption Capacity
Three distinct scenarios now emerge depending on whether fresh marginal demand arrives at sufficient scale. The bull case requires the August jobs report and cooler CPI data to lower rate hike expectations while ETF flows reverse positive, allowing Bitcoin to close above the $83,000 to $86,000 long-term holder band and open a path toward the options-implied upper range near $89,700. Under this path, the profit overhang absorbs cleanly into new demand, and September’s scheduled economic tests confirm momentum higher.
The base case has macro conditions remain tight but not deteriorating, with ETF flows alternating between inflows and outflows while Bitcoin ranges between $71,000 support and the $83,000 to $86,000 resistance zone. A quarterly options expiry on September 25 carries roughly $14 billion of open interest across Deribit and IBIT exchanges, with meaningful positioning clustered above $80,000, adding volatility risk to the period. This concentrated option positioning often influences price action as market participants hedge their exposures.
The bear case has stronger jobs or inflation data reinforce hike risk while ETF outflows persist, pushing recent buyers to defend gains rather than add capital, potentially forcing a test of the $62,000 to $65,000 accumulation floor. Deteriorating macro conditions could trigger liquidations of leveraged positions and force algorithmic selling across correlated assets.
Bitcoin’s determining factor across all three paths remains identical: whether fresh marginal demand can arrive at sufficient scale to let profitable holders stay put rather than distribute into strength. The jobs report on September 4 will serve as the first signal of whether Fed rate hike odds fall enough to attract ETF inflows large enough to absorb the $47 billion profit overhang now sitting above current prices, with the CPI release on September 11 and the Fed meeting on September 15 to 16 providing additional confirmation or contradiction of the initial trend. Market participants should monitor both headline inflation and labor force participation rates closely, as these data points carry outsized influence on monetary policy expectations.