
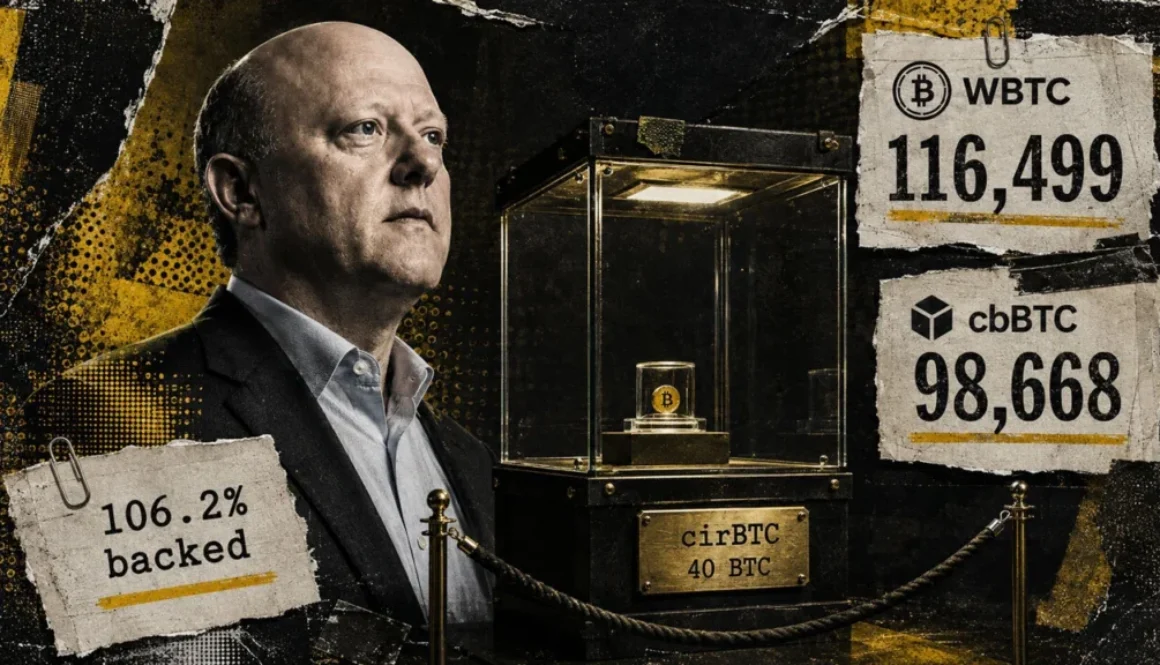
Circle CEO Jeremy Allaire claims the company developed “the platform for the internet financial system”, yet cirBTC holds just 40 BTC
Circle’s wrapped Bitcoin product launched with fortress-grade institutional backing but minimal adoption, revealing a gap between infrastructure quality and market demand. The test will determine whether Circle’s integrated platform can overcome network effects that have entrenched WBTC and Coinbase’s cbBTC as the dominant wrapped Bitcoin standards.
- cirBTC held only 40.02 BTC in circulation as of August 27, about 11 weeks after launch on Ethereum.
- WBTC circulates 2,911 times more cirBTC’s supply, while cbBTC circulates 2,465 times more, showing stark competitive scale gaps.
- No tracked 24-hour trading volume appeared on CoinGecko, and Aave collateral support remained pending as of late August.
- 40 BTC cirBTC outstanding, versus 116,499 WBTC and 98,668 cbBTC in supply
- 106.2% reserve coverage ratio, backed by 42.51 BTC held across 14 disclosed addresses
- $73.3B USDC in circulation at Q2 end, establishing Circle’s platform scale and distribution reach
- Sept. 16 scheduled mainnet launch date for Circle’s Arc settlement network, with 100+ builders participating
Circle International Bermuda Limited launched cirBTC as a federally custodied, institutionally credentialed representation of Bitcoin on Ethereum, backed by Bitcoin held at Circle National Trust, a newly chartered federal trust bank. The product arrived with direct redemption for eligible institutions, a published reserve panel showing 42.51 BTC against 40.02 BTC issued, and integration into Circle’s existing stablecoin and planned settlement infrastructure. Yet eleven weeks after its debut, cirBTC occupied a position of institutional credibility with virtually no visible market presence, exposing what CEO Jeremy Allaire described in Circle’s second-quarter results as “the platform for the internet financial system” to a fundamental test: whether formal structure and custody excellence could overcome the network effects that have entrenched older wrapped Bitcoin tokens.
Wrapped Bitcoin products serve a critical function in the decentralized finance ecosystem by allowing Bitcoin holders to access smart contract protocols on Ethereum and other blockchains without moving their underlying assets off the Bitcoin network. WBTC, launched in 2019, established the category and built a diverse custodian network that gave it early distribution advantages. Coinbase’s cbBTC entered the market in 2024 with the backing of a major exchange and cryptocurrency institution, immediately capturing significant market share and vault integration. Both tokens operate through multiple custodians and integrate seamlessly into existing DeFi protocols, lending platforms, and exchange infrastructure that have accumulated substantial liquidity and user bases over years of operation.
40 BTC Against Six-Figure Incumbents
The supply differential illustrates the adoption challenge in concrete terms. WBTC maintained a 116,499 BTC outstanding supply as of August 29, approximately 2,911 times the cirBTC float, while Coinbase’s cbBTC held 98,668 BTC across multiple blockchains, approximately 2,465 times larger. Supply volume directly correlates with distribution: each minted token represents institutional or retail demand to access Bitcoin value on a smart contract network, and larger floats create larger liquidity pools from which trading, lending and collateral markets can develop.
The market activity data reinforced the gap.
DefiLlama recorded approximately $110.49 million in 24-hour WBTC trading volume and $3.12 billion in maximum observed lending exposure at its August 29 check, while cbBTC showed approximately $338.55 million in volume and $2.817 billion in lending exposure. CoinGecko’s verified cirBTC contract page showed zero tracked 24-hour volume, zero liquidity, and zero recorded transactions, leaving the token invisible to public market data even as a proxy for adoption. This absence from visible market activity suggests minimal engagement from active traders and portfolio managers who might otherwise compare wrapped Bitcoin options based on yield, risk profiles, or trading dynamics.
Institutional Structure Without Market Traction
cirBTC’s design reflected deliberate formality at every operational level. Circle International Bermuda Limited functions as the legal issuer; Circle National Trust, the newly approved federal trust bank, holds the underlying Bitcoin as custodian; and Circle Mint, operated by Circle Internet Financial, LLC, handles distribution and direct redemption for qualified institutions. An eight-decimal ERC-20 contract deployed at address 0x72DFB2E44f59C5AD2bAFE84314E5b99a7cd5075E routes transfers on Ethereum, while monthly transparency panels disclose reserve positions and backing ratios.
The custody credential appeared genuine. The Office of the Comptroller of the Currency granted Circle National Trust final approval in July, establishing federal oversight of the Bitcoin reserves. The 106.2% coverage ratio on August 27, with 42.51 BTC in reserve against 40.02 BTC issued, eliminated any near-term backing uncertainty. However, that institutional wrapper addressed only the custodial question, not the distribution one. Direct minting and redemption remain available only to eligible institutions meeting Circle’s compliance criteria and operating in supported jurisdictions, creating a narrower primary-market access path than WBTC and cbBTC already occupy within established exchange, wallet and lending ecosystems.
Market adoption of a wrapped Bitcoin standard depends not on custody credentials alone but on the breadth and depth of integration across trading venues, decentralized exchange protocols, lending platforms, and wallet applications. Every protocol that chooses to accept cirBTC as collateral or trading pair requires engineering resources, risk assessment, and community governance decisions that become less necessary as dominant standards accumulate further integration. This creates a self-reinforcing dynamic favoring established products.
Adoption will require dealers, market makers, protocols and custodial platforms to integrate cirBTC before its trust architecture becomes useful as collateral at scale.
Arc Mainnet Launch as Next Adoption Checkpoint
Circle scheduled the public mainnet launch of Arc, its planned settlement network, for September 16, positioning it as the near-term catalyst for cirBTC distribution. Arc could create a closed environment connecting Circle’s custody, USDC stablecoin, and wrapped Bitcoin products inside a single settlement layer, with more than 100 builder projects and a validator cohort including major financial and payments companies already committed. That infrastructure would theoretically shorten the path from cirBTC minting to utility and collateral acceptance, removing friction that currently exists when moving the token across third-party venues and protocols.
However, Arc’s role remained prospective rather than proven. Circle’s cirBTC documentation described Arc testnet support as forthcoming as of the August 29 reporting cutoff, leaving the token’s day-one mainnet availability unconfirmed. Until Arc goes live with integrated cirBTC support, USDC liquidity, and active institutional participants, the supply gap persists as evidence that trust credentials and federal custody alone have not overcome the installed base advantages WBTC and cbBTC already command. Live collateral acceptance on Aave, which had a pending governance proposal to onboard cirBTC, would represent another checkpoint, as would visible trading volume and functioning secondary markets where institutions could open, finance and unwind positions efficiently.
Circle’s reserve panel confirmed the backing question at its August 27 snapshot, validating that cirBTC held genuine Bitcoin reserves at 106.2% coverage. The adoption question remains unresolved: whether venues, protocols, market makers and institutions will choose to integrate a third wrapped Bitcoin standard when WBTC and cbBTC already control the liquidity pools and network effects that determine collateral utility. The September 16 Arc mainnet launch will be the first opportunity to measure whether Circle’s integrated platform can accelerate that decision, and whether continued low cirBTC supply after that launch date will force Circle to reconceive its strategy for distributing the product.