The complete US Bitcoin ETF sector experiences a $63 billion cycle of uninterrupted activity
BlackRock’s iShares Bitcoin Trust has captured more inflows than the entire US spot Bitcoin ETF category combined, raising questions about market concentration and resilience. The fund’s dominance reveals how institutional capital consolidates around familiar platforms when entering emerging asset classes.
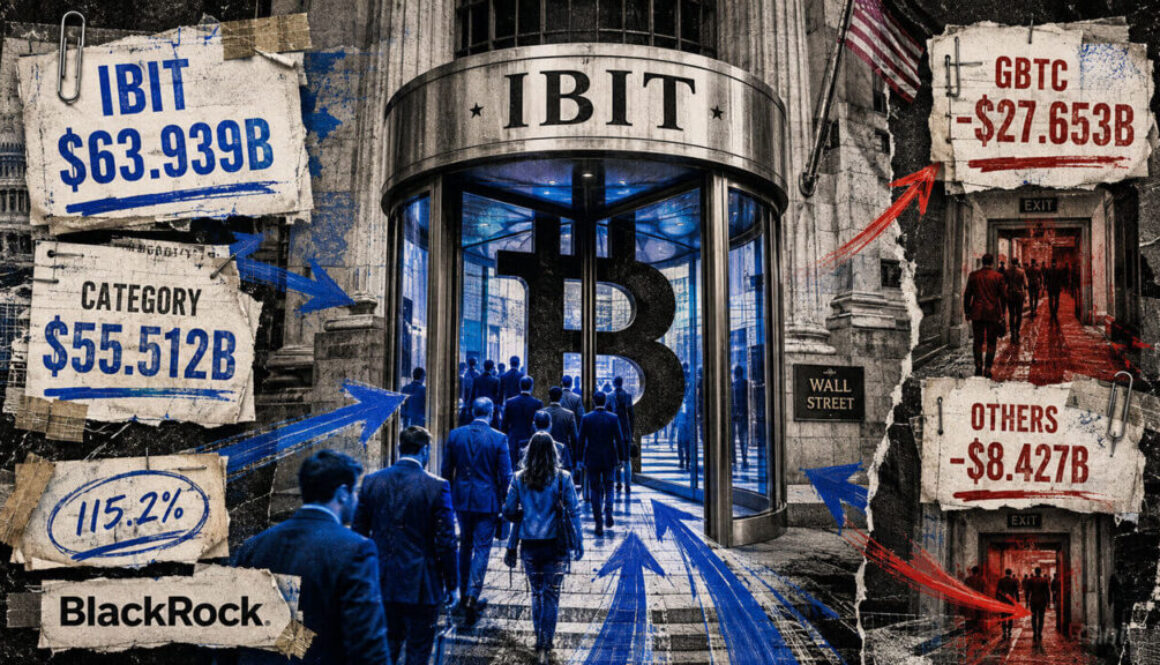
- IBIT collected $63.9 billion in net inflows from January 2024 through September 3, 2026, exceeding the entire category’s $55.5 billion total.
- Grayscale Bitcoin Trust experienced $27.6 billion in net outflows since January 2024 as investors migrated to cheaper competing products.
- IBIT’s structural advantages—institutional custody compatibility, advisor integration, and brand recognition—drive demand independent of fee comparisons alone.
- 115.2% IBIT’s share of total US spot Bitcoin ETF category inflows
- $27.6B Grayscale Bitcoin Trust net outflows since January 2024
- 0.25% IBIT sponsor fee, a competitive rate for institutional buyers
- 77.8% IBIT’s share of category flows in mid-August to early September period
BlackRock’s iShares Bitcoin Trust has emerged as the dominant vehicle shaping the US spot Bitcoin ETF market since its launch in January 2024. From that date through September 3, 2026, IBIT accumulated over $63.9 billion in cumulative net inflows, according to Farside Investors’ fund ledger. During the same period, the entire US spot Bitcoin ETF category retained only $55.5 billion in net inflows, meaning all other Bitcoin ETFs combined suffered $8.4 billion in net outflows. This disparity reveals a concentrated market structure where one product has captured more capital than the category it belongs to has gained in total.
IBIT’s Dominance Exceeds the Entire ETF Category’s Net Gains
IBIT accounted for 115.2% of the category’s total net inflows—a figure that reflects a straightforward reality rather than mathematical impossibility.
The fund brought in enough capital to cover withdrawals from competing products and still add additional capital to the overall category. This role has positioned IBIT as an informal market stabilizer, though one without the mandate or resources of a traditional buyer of last resort. The concentration reflects broader trends in asset management, where dominant platforms increasingly capture disproportionate flows across new markets as institutional investors favor familiar infrastructure.
Recent momentum has only intensified this pattern. During 14 trading sessions from August 17 through September 3, IBIT drew $2.843 billion of the group’s $3.655 billion in net inflows, representing 77.8% of category flows. This acceleration suggests mounting institutional preference for the largest vehicle despite the availability of cheaper alternatives.
Grayscale’s $27.6 Billion Exodus Reshapes Market Structure
Much of the outflow from other products came from Grayscale Bitcoin Trust, the legacy Bitcoin fund that converted to an ETF structure. GBTC recorded $27.6 billion in net outflows since January 2024, as the conversion gave shareholders a redemption route while cheaper competing products offered an obvious destination for those seeking lower fees. When removing both IBIT and GBTC from the calculation, the remaining market of cheaper products led by Fidelity and smaller issuers took in $19.2 billion.
IBIT still brought in more than three times their combined sum, suggesting that cost considerations alone do not explain investor preferences.
The fund charges a 0.25% sponsor fee and maintains a 0.02% 30-day median bid-ask spread, both competitive metrics for institutional buyers. As of September 3, BlackRock reported approximately $63.44 billion in IBIT net assets, with 1.375 billion shares outstanding. Yet cost advantage is not the primary driver of IBIT’s dominance over competing low-fee options, pointing instead to structural advantages that extend beyond the fee schedule.
Institutional Infrastructure Advantages Drive Flows Beyond Fee Comparison
IBIT’s appeal rests on structural advantages unavailable to other Bitcoin entry points. Financial advisers can place IBIT inside model portfolios using familiar processes developed over decades of equities and fixed-income investing. Companies can hold it through conventional custody arrangements, and retirement investors gain exposure without managing private keys or learning exchange operations. Heavy daily trading facilitates large orders, while BlackRock’s established reputation reduces the need for advisers to justify the allocation to skeptical compliance teams and clients.
The fund operates across two distinct markets that shape its role in the Bitcoin ecosystem. In the secondary market during regular trading hours, investors buy and sell existing IBIT shares on Nasdaq. Billions of dollars can trade while the number of shares and the trust’s Bitcoin holdings remain unchanged. The underlying pool expands through the primary market, where authorized participants submit orders for large blocks of new shares. The trust receives Bitcoin or cash through the creation process, while redemptions run the same mechanism in reverse.
Arbitrage ensures the fund stays close to net asset value by incentivizing creation when IBIT trades above Bitcoin’s value per share and redemption when it trades below. Daily flow estimates measure primary-market expansion and contraction. Net creations indicate fresh capital entering the vehicle, while redemptions signal capital departing. Trading volume, by contrast, shows only how many shares moved between existing investors without changing the trust’s size or Bitcoin holdings.
IBIT Functions as Market Stabilizer Without a Central Bank Mandate
IBIT’s role as a market stabilizer differs fundamentally from how central banks function as traditional buyers of last resort. A central bank has a public mandate and can create money to support markets. IBIT expands only when investors place orders for new shares, so its backstop depends entirely on continued investor demand rather than institutional obligation.
The fund’s capacity to offset category-wide selling is conditional and directional. On September 1, IBIT lost $201.2 million while Fidelity’s fund lost $43.7 million, combining for a $236.5 million category outflow. One session later, IBIT brought in $115.4 million, helping the category finish positive despite a $56.2 million outflow from GBTC. The fund can offset other products’ selling one day and join it the next because the mechanism faithfully follows investors in both directions.
The same structure that makes IBIT appear dependable also defines its limits.
It carries no reserve fund waiting for a Bitcoin crash and receives no instruction to buy when price falls. Persistent inflows create the appearance of a backstop only as long as that crowd keeps adding capital. Under a base case, IBIT remains the dominant inflow vehicle while Bitcoin demand continues routing through one main US ETF, normalizing concentrated access. A bull case would see IBIT absorb rival outflows while adding fresh capital, strengthening Bitcoin’s marginal bid as the wrapper becomes the preferred institutional rail. A bear case would find IBIT joining category-wide outflows, transforming the buyer of last resort into a sell channel with the same structure amplifying downside. Under a stress scenario, heavy redemptions meeting weak liquidity could add pressure during fragile market conditions, as a backstop without a mandate can disappear quickly.
Bitcoin’s Evolution Into Mainstream Finance Through Concentrated Infrastructure
Bitcoin emerged from a desire to exit conventional finance, attracting participants skeptical of traditional institutions. Its newest large buyer is a conventional product that lets a much wider population enter while keeping the same accounts, advisers, tax documents, and trading habits they already use. The demand behind IBIT is broader than BlackRock itself, yet far more concentrated than the ticker alone makes it appear.
Creations can generate demand for Bitcoin in the underlying market, though the price effect depends on available liquidity, execution methods, derivatives hedges, and seller willingness. Flow data captures one powerful source of marginal demand within a much larger market, which is why Bitcoin can fall during an inflow day or climb during an outflow day. IBIT’s share of weekly flows reveals how dependent the category has become on one product. Days when IBIT offsets redemptions elsewhere indicate whether the informal backstop remains active. Shares outstanding confirm whether the trust is expanding, while the premium or discount to net asset value shows how tightly arbitrage is working.
The paradox of IBIT’s position illustrates how new asset classes evolve from outsider status to mainstream adoption through the infrastructure of existing institutions. Observers should track whether IBIT maintains its share of category inflows during periods of Bitcoin weakness, whether competing products stabilize their own redemption rates, and whether concentrated custody arrangements through a small group of authorized participants create liquidity risks during market stress.