
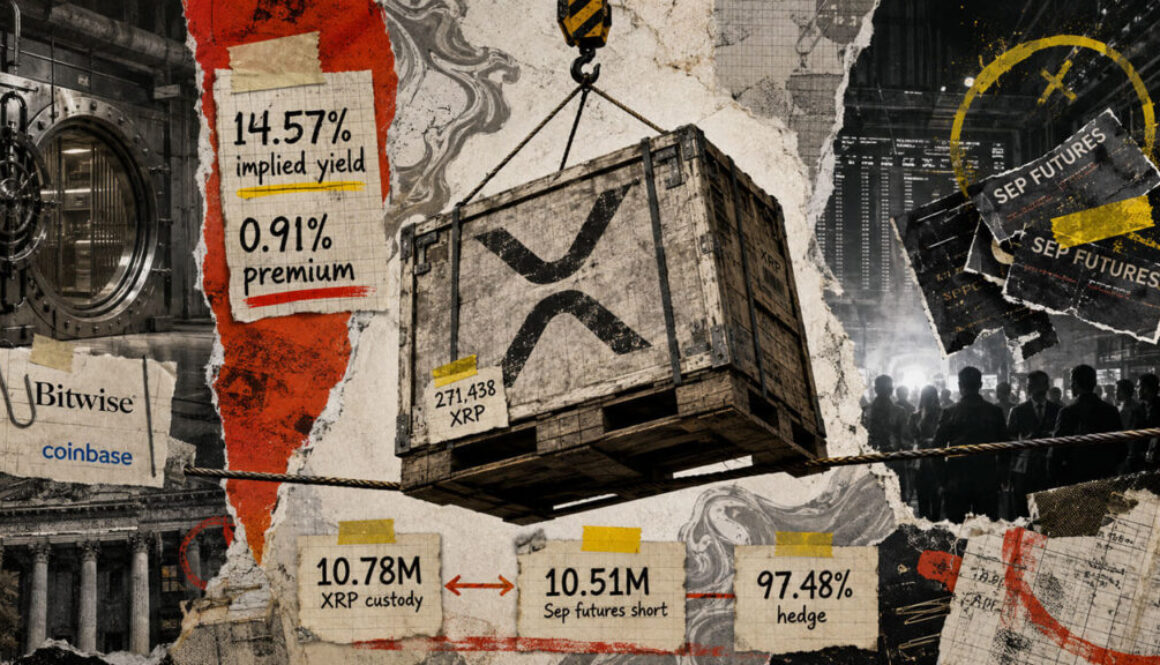
Institutional investors exploit 14% yield gap in XRP futures by quietly draining capital from retail traders, Bitwise analysis reveals
Bitwise’s newly disclosed XRP carry trade reveals how institutional investors are locking in futures premiums over spot prices while neutralizing directional risk. The structure shows a sophisticated strategy to extract yield from crypto markets that retail traders may not fully appreciate or access.
- Bitwise Crypto Carry Fund held 10.78 million XRP in custody paired with 10.51 million XRP short futures for 97.48% hedge coverage.
- The fund’s September Coinbase XRP futures displayed a 14.57% annualized implied yield, derived from a 0.91% spot-to-futures premium.
- Leveraged funds held 13,822 short contracts in XRP futures as of August 25, positioning them on the opposite side of institutional basis trades.
- 14.57% Annualized implied yield on XRP futures premium versus spot price
- 97.48% Quantity hedge ratio between spot holdings and futures short position
- $232,776 Notional value difference between custody and futures legs of trade
Bitwise’s Crypto Carry Fund (ticker: USCC) has offered an unusually transparent window into how large financial institutions are monetizing short-term inefficiencies in XRP futures markets. The fund’s published holdings as of September 1 documented a structured position that paired substantial XRP holdings against nearly equal short futures positions, creating a market-neutral trade designed to capture the premium that forward contracts were trading above spot prices. The strategy reveals institutional sophistication in extracting yield from digital asset markets while hedging away directional exposure that would interest retail investors.
Crypto carry trades have become increasingly common as institutional capital has entered digital asset markets over the past several years. The strategy operates similarly to fixed-income arbitrage in traditional finance, where investors profit from pricing discrepancies rather than market direction. Unlike equity or commodity markets, cryptocurrency futures markets have historically displayed persistent premiums due to factors including storage costs, regulatory uncertainty, and structural differences between spot and derivatives venues.
How Bitwise Structured a Nearly Perfect Hedge
USCC’s position centered on a 97.48% quantity match between its XRP custodial holdings and XRP futures shorts. As of September 1 at 4 p.m. EDT, Bitwise disclosed 10,781,438.36 XRP held in custody and a displayed futures short position of negative 10,510,000 XRP. This near-perfect offset left only 271,438.36 XRP, or about 2.5% of the total position, exposed to XRP’s directional price movement.
The fund’s remaining price exposure was minimal by design.
By maintaining this tight hedge, USCC eliminated most risk from parallel price swings between spot and futures markets. Instead, the fund’s returns would flow primarily from convergence between the two prices at futures settlement, a process called cash-and-carry. The structure represents exactly how institutional investors use crypto derivatives markets to generate fixed-income-like returns without maintaining open directional bets. This approach mirrors strategies that insurance companies, pension funds, and other institutional managers have employed in traditional commodity and financial derivatives markets.
The 0.91% Premium Annualized to 14.57% Yield
The mathematical foundation of USCC’s position rested on a simple but meaningful gap between spot and futures pricing. Using the notional values disclosed in Bitwise’s holdings table, the spot-equivalent price worked out to approximately $1.3222 per XRP, while the September Coinbase futures equivalent marked at roughly $1.3342. That 1.2-cent gap, or 0.91% premium, was the economic source of the fund’s yield.
Bitwise’s methodology converts that single-month premium into an annualized figure by assuming the position would be held to maturity or rolled at similar terms through the full year. Under that calculation, the 0.91% spread became 14.57% on an annualized basis. The fund separately reports a 30-day yield figure and deducts a 0.75% management fee from investor returns, meaning the actual realized yield would differ from the headline annualized rate.
Bitwise’s public disclosures do not specify treatment of execution costs, financing charges, custody fees, margin requirements, or roll costs associated with moving into subsequent futures contracts. The 14.57% figure therefore represents the firm’s annualized implied rate specific to the displayed XRP futures holding, not a guaranteed or net return to investors. In crypto markets, where liquidity can shift rapidly and funding rates on derivatives venues fluctuate significantly, actual implementation costs may vary considerably from theoretical calculations.
Leveraged Funds Hold the Opposite Side of the Trade
Understanding who benefits from the opposite side of an institutional basis trade requires looking at the broader XRP futures market structure. As of August 25, standard Coinbase XRP futures carried 20,518 contracts of open interest. Dealer and intermediary accounts held 17,853 long contracts, while asset manager and institutional accounts added 1,800 longs. On the short side, leveraged funds held 13,822 outright short contracts with no outright longs in that category.
Bitwise’s USCC fund operates as a qualified-purchaser vehicle specifically designed to capture futures premiums across crypto markets. The fund’s disclosed hedging strategy aligns with the institutional pattern visible in CFTC data, where asset managers and dealers on the long side of XRP futures are collecting premiums from buyers who are willing to pay above spot to establish forward exposure. Leveraged funds, positioned predominantly as shorts, serve as a potential source of demand for those forward contracts at elevated prices. This market structure suggests that retail traders using leverage to establish XRP positions may be indirectly financing the carry yields that institutional investors capture.
The data leaves Bitwise’s exact counterparties and institutional-wide breakdown between directional and basis trading demand unresolved.
Bitwise’s Separate XRP ETF Reveals Different Product Strategy
Within Bitwise’s own product ecosystem, a sharp contrast exists between the carry fund’s basis-trading approach and its XRP ETF’s simpler structure. The Bitwise XRP ETF reported 361,995,068.31 XRP in trust as of September 2, valued at approximately $531.3 million. That fund’s SEC filings define its sole objective as providing exposure to XRP’s value, net of expenses, with XRP as its only holding.
The ETF pursues straightforward spot exposure while USCC pairs spot and futures positions to eliminate directional risk and capture premiums. Both products hold the same asset under the Bitwise name but serve fundamentally different investor needs: the ETF caters to investors seeking XRP price appreciation, while USCC targets institutional investors seeking yield from market structure rather than directional returns. This dual-product approach reflects how crypto asset managers are segmenting investor demand across both return drivers and risk profiles.
Bitwise’s disclosures raise an open question about the broader institutional demand for XRP: the 14.57% annualized yield on USCC’s basis trade demonstrates that near-term premiums are substantial enough to attract dedicated capital, but the fund’s hedging strategy explicitly excludes exposure to whether that premium persists or collapses. Whether similar carry trades proliferate across other institutional players, and whether the availability of such yield ultimately compresses the spot-to-futures gap, remains dependent on how much additional capital enters this market structure and how futures settlement dates approach. As cryptocurrency derivatives markets mature and attract more institutional participation, the competitive dynamics around basis trading will likely influence overall market efficiency.