Bitcoin falls below $84,000 as US real yields jump to 2.76%
Update (Sep 25, 9:06am): New draft reports Bitcoin fell below $85,000 and previously climbed above $87,000, with updated price levels and different framing of the rebound narrative not present in published version.
Bitcoin’s slide below $84,000 traces less to crypto-specific selling than to a sharp jump in US real yields, which raise the opportunity cost of holding an asset that pays no interest. For traders watching leverage and macro positioning alike, the coming days of Treasury yield moves and Friday’s options expiry will determine whether $84,000 holds as support or gives way toward $77,000.
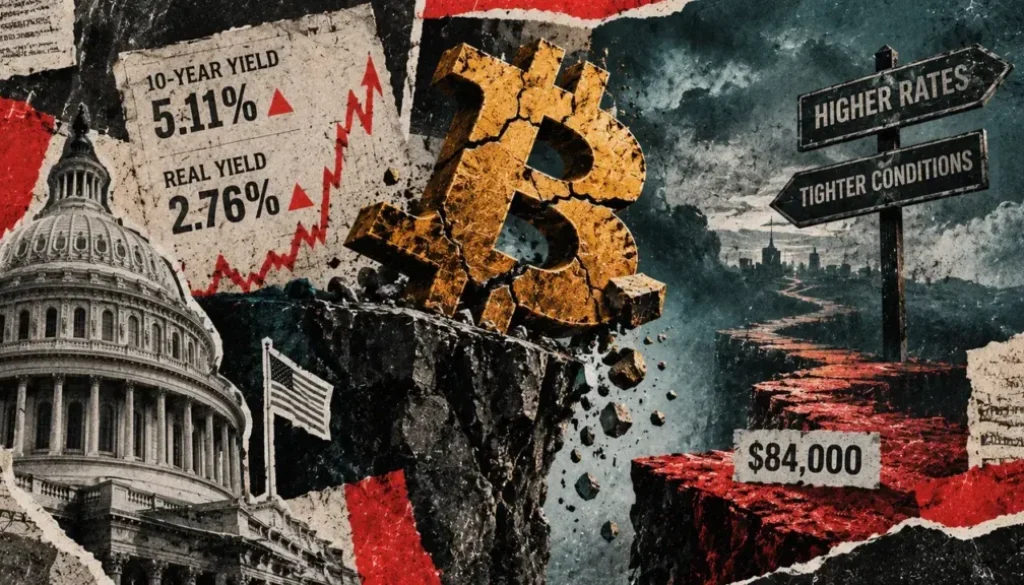
- Bitcoin hit an intraday low of $83,500 on Sept. 23 as the 10-year Treasury yield jumped 15 basis points to 5.11%.
- The 10-year real yield rose from 2.63% to 2.76%, accounting for 13 of the 15 basis points added to the nominal yield.
- Spot Bitcoin ETFs pulled in roughly $1.3 billion over five days, ending two weeks of outflows, according to Glassnode.
- 5.11% 10-year Treasury yield, up from 4.96% a day earlier
- 2.76% 10-year real yield, up 13 bps from 2.63%
- $84,000 Glassnode’s key support zone versus $77,000 downside marker
- $1.3B five-day spot Bitcoin ETF inflows ending prior outflow streak
Bitcoin dropped to an intraday low of $83,500 on Sept. 23, the same session in which the US 10-year Treasury yield closed at 5.11%, a 15 basis point jump from 4.96% the day before, according to reporting by CryptoSlate. The move followed a hotter-than-expected reading on US business activity that prompted traders to reprice how long the Federal Reserve will keep policy restrictive. Roughly $280 million in long positions were liquidated as Bitcoin broke below $84,000, according to CoinGlass data cited in the report.
The selloff was driven almost entirely by real rates, not inflation expectations. Implied 10-year inflation compensation moved just 2 basis points, from about 2.33% to 2.35%.
Real Yields climb 13 basis points as PMI hits 58.4
The trigger was S&P Global’s September Purchasing Managers’ Index, whose composite reading jumped to 58.4 from 56.0, the strongest expansion in the survey since July 2021. Services activity came in at 58.7 and manufacturing at 57.0. The data landed one week after the Fed’s Sept. 16 rate move to a 3.75% to 4.00% target range, leaving markets to conclude the central bank has less room to cut further.
The 10-year real yield, which strips out expected inflation and is tracked on Treasury’s real yield curve, rose from 2.63% to 2.76%, absorbing 13 of the 15 basis points added to the nominal 10-year Treasury yield. Intraday reports put the 10-year near 5.058% within minutes of the PMI release before Treasury’s end-of-day curve settled at 5.11%.
A higher inflation-adjusted return on government debt directly raises the cost of holding an asset like Bitcoin that generates no yield of its own. That dynamic, more than any single crypto-market event, explains the drop on Sept. 23.
Glassnode places support at $84,000 against $77,000 downside marker
Glassnode’s Sept. 23 report identifies $84,000 to $85,000 as the price band where the largest cluster of long-term holder supply was acquired, making it the nearest on-chain support zone. Below that sits the True Market Mean at $77,000, which Glassnode describes as the primary downside reference if the $84,000 zone fails on sustained daily closes. From Bitcoin’s roughly $84,282 quote, that level implies an 8.6% decline.
On the upside, Glassnode’s mean MVRV price puts the next major resistance at $96,700, about 14.7% above current levels. The framework rests on closing prices rather than intraday wicks, meaning a brief dip through $84,000 does not by itself break the support structure. A string of closes below the zone would be needed to shift focus toward $77,000.
Demand data collected by Glassnode shows spot Bitcoin ETFs took in about $1.3 billion over five days as the recent short squeeze unfolded, ending two weeks of outflows. Twenty-four-hour spot trading volume across exchanges rose 121% from its August trough over the same period. Separate figures from Farside Investors show $999 million in ETF inflows on Sept. 21, $714.7 million on Sept. 22, and $346.9 million on Sept. 23, with IBIT leading the second day at $350.3 million, FBTC at $257.4 million, and MSBT at $99 million.
Friday’s $16 billion Options Expiry sets next test
Farside’s Sept. 23 figures show ETF inflows continued through Wednesday’s bond selloff, though at a slower pace than the two prior sessions. Glassnode’s on-chain and ETF data run mostly through Sept. 21, with spot-volume figures through Sept. 22, leaving a gap in confirming whether demand held up as yields moved.
Friday (Sept. 25) brings roughly $16 billion in Bitcoin options expiring on Deribit, alongside US durable goods and consumer sentiment data and CME’s September Bitcoin futures settlement in the afternoon. In the bull scenario described in the report, the 10-year real yield retraces below about 2.65% while ETF inflows and spot volume on up days both hold positive, opening a path toward Glassnode’s $96,700 resistance. In the bear scenario, real yields extend toward 2.85% to 2.90%, Bitcoin closes persistently below $84,000, and the $77,000 True Market Mean becomes the active downside target.
The BlockWest read. The dip shows how exposed leveraged Bitcoin positioning has become to a single macro input, real rates, rather than crypto-native catalysts. Allocators treating Bitcoin as a portfolio hedge should note that ETF inflows kept coming even as yields spiked, suggesting institutional buyers are pricing this as a rate story, not a confidence break. Balance sheets holding BTC on leverage remain the more fragile piece of this trade.
The next Treasury real-yield print and Bitcoin’s daily closes into Friday’s (Sept. 25) $16 billion options expiry will show whether the $84,000 to $85,000 zone holds or whether Glassnode’s $77,000 True Market Mean comes into play.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.