Tether drives USDT expansion into fragile $3 trillion Wall Street debt market amid record defaults across top-tier investment firms
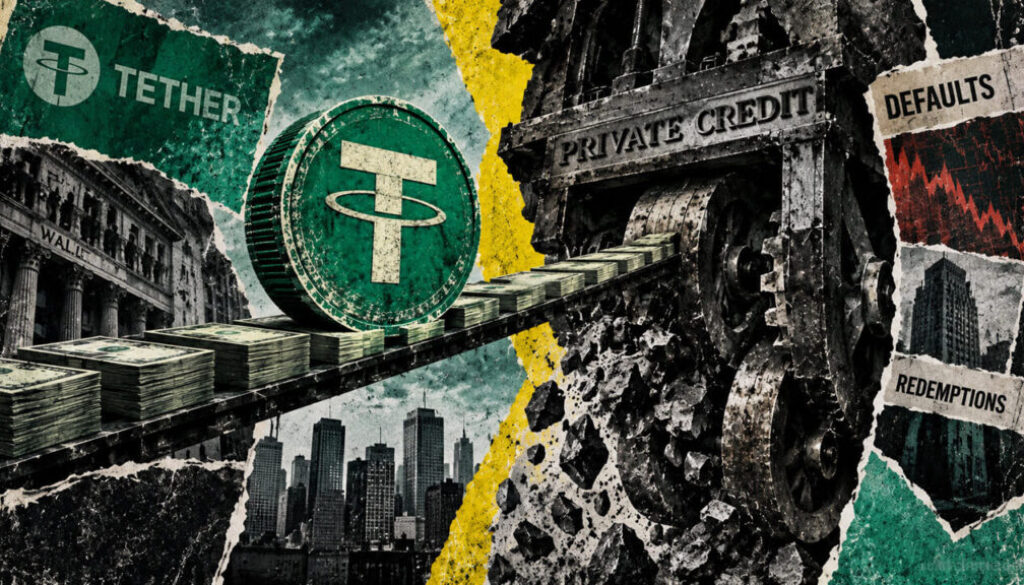
Tether is expanding beyond crypto lending into the $3 trillion private-credit market, a sector now facing rising defaults and investor scrutiny. The move signals confidence in USDT’s institutional utility but arrives as credit quality deteriorates across major Wall Street funds.
- Tether and Fasanara Capital launched StableFund on September 9 with $400 million in sponsor capital and plans to raise up to $3 billion more.
- Tether controls approximately 60% of the $23 billion centralized crypto-lending market, holding roughly $13.5 billion in outstanding secured loans as of June.
- Default rates at major private-credit funds reached their highest levels since at least 2021, with Blue Owl’s default rate hitting 2.8% in the second quarter.
- $3 trillion Total size of the private-credit market Tether is now entering
- 60% Tether’s estimated share of the centralized crypto-lending market
- 2.8% Blue Owl’s default rate in Q2, its highest in five years
- $400M Combined sponsor capital deployed in StableFund at launch
Tether is moving aggressively beyond its crypto-native lending dominance into Wall Street’s private-credit ecosystem. On September 9, the stablecoin issuer partnered with London-based Fasanara Capital to establish StableFund, combining $400 million in initial sponsor capital with plans to eventually raise up to $3 billion from institutional investors. Fasanara will serve as the fund’s investment manager, while Tether will originate financing opportunities through its stablecoin network, provide settlement infrastructure, and source deals from its global user base spanning more than 60 countries.
Tether controls 60% of crypto lending, now targeting larger market
The private-credit market represents a significantly larger opportunity than the crypto-lending space where Tether has already built dominant market share. Galaxy Research estimates that as of the end of June, Tether controlled around 60% of the $23 billion centralized crypto-lending market, translating to roughly $13.5 billion in outstanding secured loans. StableFund extends that operational leverage into asset-backed lending for small and medium-sized businesses, consumer financing, and supply-chain credit across Fasanara’s network of more than 60 countries.
Private credit has emerged as one of the fastest-growing segments of alternative asset management over the past decade, as regulatory constraints on traditional bank lending and persistent low interest rates pushed institutional investors and corporations toward non-bank lenders. Major asset managers including Blackstone, Ares Management, and Apollo Global Management have built substantial private-credit divisions by underwriting loans directly to mid-market companies, real estate developers, and other borrowers unable or unwilling to access traditional banking channels. The market’s growth has accelerated particularly after the 2008 financial crisis, as tighter banking regulations created structural supply constraints that private lenders filled with capital.
Tether’s precise financial exposure through StableFund remains undisclosed, leaving key terms unresolved.
The companies announced a joint $400 million anchor commitment but did not divide that capital between the two sponsors or specify whether either party would absorb losses before third-party institutional capital. The announcement also did not clarify fund leverage, fee structures, whether USDT will serve as loan principal or collateral, or the fund’s redemption terms. Those gaps matter significantly if private-credit defaults continue their current trajectory, as they determine how much downside risk Tether assumes relative to outside investors.
For Tether, entry into private credit represents a natural extension of its institutional ambitions beyond cryptocurrency settlement. The company has positioned USDT as critical infrastructure for dollar-denominated transactions across decentralized finance, emerging markets, and fintech platforms. By incorporating USDT into private-credit origination and settlement, Tether gains visibility into institutional capital flows while diversifying beyond its existing crypto-lending concentration. The partnership with Fasanara, an established credit manager with $6 billion under management, provides portfolio management expertise and regulatory credibility that Tether alone might lack.
Private-Credit Defaults hit five-year highs amid investor scrutiny
StableFund’s arrival coincides with measurable stress across the private-credit industry. An August Wall Street Journal analysis of publicly traded funds managed by Ares Management, Blackstone, Blue Owl Capital, and Golub Capital found deteriorating loan health and worsening investor returns. Defaults at those vehicles reached their highest levels since at least 2021, while Blue Owl’s default rate rose to 2.8% in the second quarter, marking its worst performance in at least five years.
Major fund managers have argued that these increases, while notable, remain below stress levels experienced during more severe economic episodes such as the Covid-19 shock and do not signal a systemic crisis. However, the credit deterioration coincides with redemption pressure from investors and growing concern about heavily indebted borrowers, particularly software companies that may face disruption from artificial intelligence capabilities. In May, the Financial Stability Board warned that private credit has never been tested through a prolonged economic downturn and flagged weaker borrower quality, high leverage, opaque valuations, and growing links between private funds, banks, and insurers as potential vulnerabilities.
The timing of Tether’s expansion raises questions about cyclical risk exposure. Institutional private-credit investors typically expect returns between 8 and 12 percent, premiums justified by illiquidity, credit risk, and the historical absence of major defaults in funds structured as evergreen vehicles. As interest rates stabilized at higher levels in 2023 and 2024, borrowers who refinanced during the low-rate environment faced pressure when debt matured or reset. Software-as-a-service companies, leveraged buyout targets, and real estate operators with floating-rate debt exposure became particular concerns for credit investors.
Stablecoin issuer enters market as regulators watch Private Credit
The regulatory environment surrounding private credit is intensifying just as Tether attempts to tap the same institutional capital base. The Financial Stability Board highlighted the rising use of payment-in-kind arrangements and accelerating defaults as evidence of borrower stress, and specifically warned that liquidity pressures could amplify financial stress when investors seek redemptions from evergreen vehicles that allow continuous capital deployment rather than fixed termination dates. StableFund is structured as an evergreen fund, though Tether and Fasanara have not publicly disclosed its redemption terms.
Fasanara’s existing portfolio management expertise may differentiate StableFund from riskier corporate direct-lending strategies now under regulatory scrutiny.
Fasanara manages more than $6 billion and plans to focus StableFund on short-duration, asset-backed loans rather than the corporate direct-lending strategies highlighted in recent stress reports. That portfolio composition differs from vehicles managed by Ares, Blackstone, and Blue Owl where defaults have recently spiked. Tether’s role as co-originator and adviser gives it visibility into deal flow across its fintech network, potentially surfacing lower-risk opportunities before they reach broader Wall Street markets. However, Fasanara retains final investment management responsibility and underwriting authority, limiting Tether’s direct control over portfolio decisions.
Tether’s entry into private credit also reflects broader institutional acceptance of stablecoins as settlement vehicles for non-crypto financial activity. Several major asset managers have begun experimenting with blockchain-based settlement for securities and private-market transactions, viewing tokenization as a mechanism to accelerate trade settlement, reduce counterparty risk, and access emerging markets with underdeveloped financial infrastructure. Tether’s dominance in stablecoin markets and its established presence in more than 60 countries position USDT as a potential settlement layer for cross-border private-credit flows.
The critical unresolved question is whether Tether will disclose its financial commitment structure and loss-absorption rank within StableFund, and how aggressively it plans to deploy USDT beyond crypto settlement use cases if institutional inflows materialize as projected.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.