Federal Reserve’s $6 billion bond purchase serves as hidden gauge for Bitcoin’s future direction
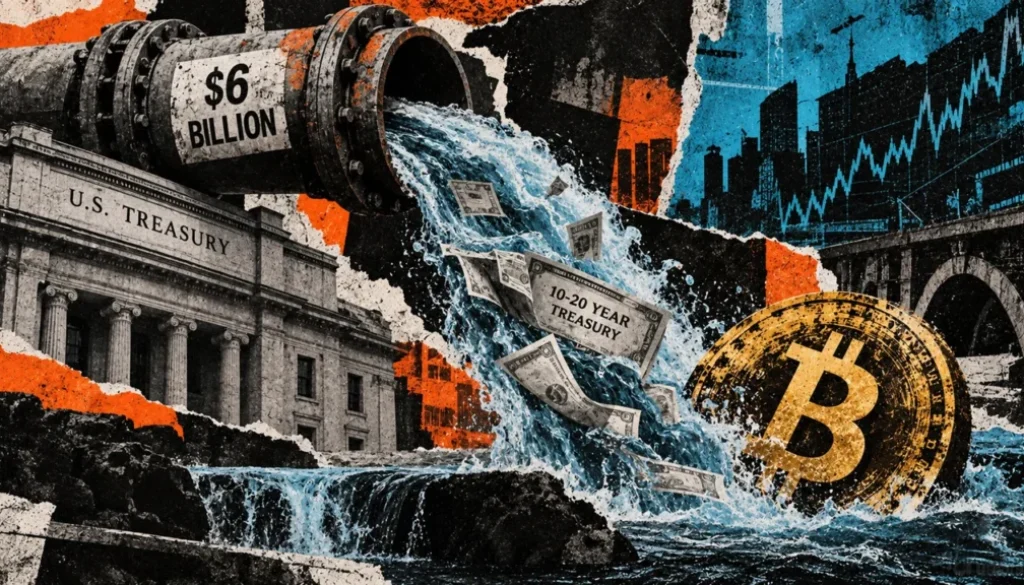
The Treasury’s expanded bond buyback program tests whether targeted interventions in debt markets can ease broader financial conditions that affect digital asset liquidity. For Bitcoin investors, the outcome will reveal whether dealer relief translates into measurable improvements in funding markets beyond traditional fixed income.
- Treasury raised the Sept. 10 buyback ceiling to $6 billion, triple the previous $2 billion limit and exceeding the $4 billion minimum announced in August.
- The operation targets 10- to 20-year Treasury securities with settlement on Sept. 11, with the final securities list due at 11 a.m. Eastern on operation day.
- Success hinges on whether dealer relief extends to broader financing conditions, a connection that remains empirically unproven for cryptocurrency markets.
- $6B Treasury bond buyback ceiling on Sept. 10, compared to prior $2 billion limit
- $4B Minimum buyback amount Treasury committed to in August announcement
- 10-20 Year maturity range of eligible Treasury securities for repurchase
- May 2025 IMF working paper date analyzing Treasury buyback liquidity effects
The US Treasury announced a $6 billion ceiling for a Sept. 10 buyback operation targeting longer-dated Treasury bonds, representing a significant expansion of its debt-management toolkit. The operation focuses on off-the-run securities with 10 to 20 years remaining maturity, with eligible issues spanning Sept. 11, 2036, through Sept. 10, 2046. Treasury published the tentative schedule on Sept. 9, with the operation scheduled for 1:40 p.m. to 2 p.m. Eastern and settlement two business days later on Sept. 11. The $6 billion ceiling triples the previous $2 billion limit and exceeds the $4 billion minimum Treasury announced on Aug. 19.
Treasury’s expansion aims to ease Dealer inventory strain
The buyback program operates distinctly from cash-management operations that smooth government cash balances. Instead, it functions as a predictable outlet for dealers to offload older bond holdings, reducing the balance-sheet burden of carrying off-the-run securities. When Treasury retires purchased bonds at settlement rather than lending them back into markets, it permanently removes inventory from dealer hands, easing intermediation pressures.
Dealer balance-sheet constraints have become an increasingly important factor in financial markets since the 2008 financial crisis intensified regulations on bank capital and leverage ratios. Unlike the pre-crisis era when dealers could accumulate large inventories of bonds indefinitely, modern regulations require dealers to hold capital against their positions, making inventory reduction economically meaningful. A predictable buyback program allows dealers to plan their hedging activities more efficiently and reduces the cost of holding securities between customer trades.
A May 2025 IMF working paper by Jing Zhou examined Treasury buyback effects and found modest improvements in bond trading liquidity and reduced dealer holdings, with stronger effects when inventories were elevated. The research suggests that providing an outlet for older bonds can materially ease the friction dealers face in intermediating between buyers and sellers, though the magnitude of benefit depends on initial conditions. The IMF analysis indicates that buyback programs work most effectively when executed during periods of elevated dealer stress rather than during normal market functioning.
Bitcoin’s Liquidity thesis remains empirically unconfirmed
The connection between Treasury operations and cryptocurrency funding conditions is theoretical rather than established. Proponents argue that easier dealer intermediation in bond markets could ease broader financing conditions, including repo markets and securities-backed borrowing that indirectly affect digital asset liquidity. That chain of causation requires multiple steps: dealer relief in Treasuries must flow through to general funding markets, then reach venues where crypto-collateralized lending occurs.
The mechanism linking Treasury market functioning to crypto funding relies on several assumptions about market interconnectedness. When traditional funding markets operate smoothly, institutional participants have easier access to leverage, potentially freeing capital that might flow into alternative asset classes including digital currencies. Conversely, when Treasury markets experience stress and dealer intermediation deteriorates, broader financial conditions tend to tighten, reducing the availability of leverage across markets including cryptocurrency lending platforms.
Measuring success requires looking beyond simple metrics like yield changes or purchase size. The strength of the operation’s signal depends on whether bond market functioning improves measurably, as evidenced by narrower bid-ask spreads, reduced pricing stress between old and new issues, and sustained relief in funding costs. A large purchase would confirm dealer demand, but only market structure improvements would demonstrate whether the operation accomplished its core purpose of easing intermediation.
Sept. 11 settlement opens window for market response
The Sept. 10 accepted purchases and Sept. 11 settlement represent distinct milestones for assessing program impact.
Observers should monitor bond market functioning over the days and weeks following settlement to determine whether dealer relief translates into measurable improvements. The stronger signal for any spillover into Bitcoin or broader crypto funding markets would be sustained improvement in Treasury trading and funding conditions, rather than a one-time purchase. A successful operation would show persistent narrowing of spreads and stable dealer willingness to intermediate bonds, which historically correlates with improved conditions in broader credit and funding markets.
The success of Treasury buyback programs depends partly on their frequency and predictability. Markets respond more positively to well-signaled, recurring operations than to one-off interventions, as they allow dealers to incorporate the buyback outlet into their inventory management and pricing strategies. Treasury’s announcement of the tripled $6 billion ceiling, exceeding the previously communicated $4 billion minimum, sends a signal of commitment to supporting market functioning.
The final securities list is due at 11 a.m. Eastern on Sept. 10, and the operation runs from 1:40 p.m. to 2 p.m. Eastern the same day, with settlement on Sept. 11. Markets will then need to demonstrate whether bid-ask spreads narrow, funding rates ease, and dealer balance-sheet pressure remains relieved, establishing whether the Treasury’s intervention has created conditions favorable for the broader financial ecosystem, including digital asset markets.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.