Ripple Prime offers institutions synthetic exposure to Hyperliquid perpetuals
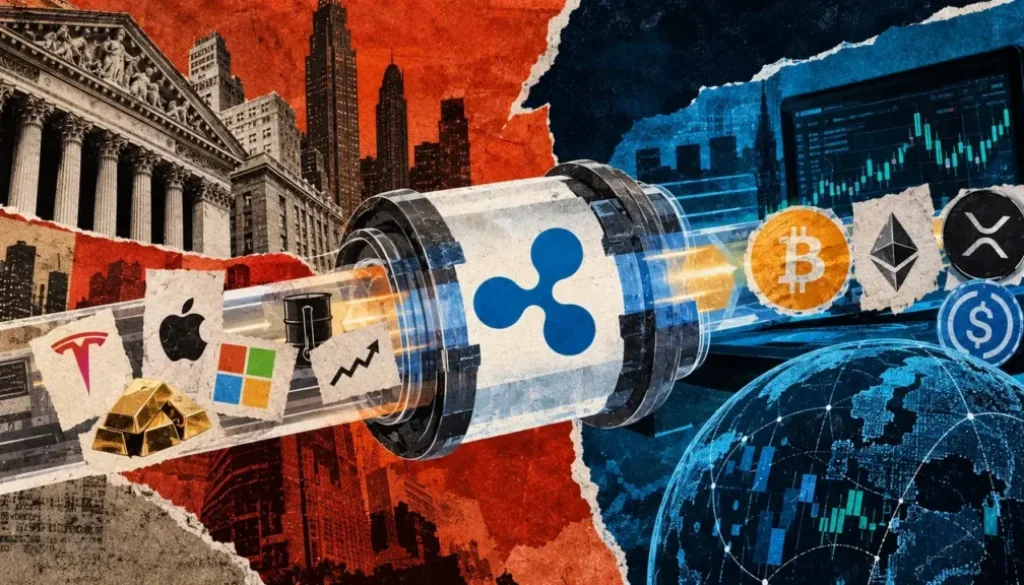
Ripple has opened a channel for Wall Street institutions to trade perpetual contracts on Hyperliquid, a decentralized exchange, through synthetic derivatives that settle in stablecoins and accept XRP’s RLUSD token as collateral. The move tests whether prime brokerage infrastructure can bridge traditional finance and on-chain markets while regulators scrutinize the margin and liquidity risks that such arrangements create.
- Ripple Prime now offers 24/7 total-return swaps referencing 110 perpetual markets listed on Trade.xyz, covering stocks, indices, ETFs, metals, energy and foreign exchange.
- Trade.xyz handled $59.4 billion in perpetual volume during September, representing 23.9% of Hyperliquid’s total trading activity across all markets.
- Ripple’s setup accepts RLUSD collateral with pooled margining across asset classes, while regulatory bodies including the CFTC and SEC are working on rules for 24/7 trading and margin harmonization.
- $59.4B Trade.xyz perpetual volume in September versus Hyperliquid total
- $2.6B RLUSD reserves reported as of October 8 against circulation
- 70.7% Weekend Hyperliquid prices closer to reopening than Friday close
- $13.2M Margin requirement before pooling in $100 million portfolio example
CryptoSlate reported on October 15 that Ripple Prime, the institutional arm of Ripple, launched swaps that allow institutions to gain synthetic exposure to perpetual contracts on Hyperliquid through Trade.xyz. The product operates as total-return swaps settling in USDC, with Ripple Prime acting as principal counterparty, and accepts RLUSD as eligible collateral subject to jurisdiction. The structure runs through Ripple Prime’s British Virgin Islands entity, with additional regional rollouts planned. It builds on earlier integrations announced in February and August that connected Ripple to Hyperliquid and expanded its derivatives offerings across equities, indices and digital assets.
Trade.xyz captures nearly a quarter of Hyperliquid’s perpetual volume
According to 0xArchive market data, Trade.xyz processed $59.4 billion of perpetual volume in September, accounting for 23.9 percent of Hyperliquid’s total activity. The venue lists 110 perpetual markets and averaged $541 million in daily volume on weekends. Trade.xyz’s oracle switches between external pricing during traditional market hours and its own internal order book when those sessions close, gradually shifting its reference price over a 30-minute window to reduce discontinuities at market reopenings.
An 0xArchive study of 614 market-weekends found that Hyperliquid’s weekend closing prices ended closer to the following Monday reopening price than to Friday’s close in 70.7 percent of observations. The median absolute error in price discovery fell from 113.3 basis points to 53.4 basis points, suggesting the oracle’s blended pricing method tracks cash market expectations during closure windows. The sample required at least $1 million of weekend volume per observation, and the Hyperliquid Policy Center funded the research.
Pooled margining and collateral haircuts create compounding liquidity pressure
Ripple Prime’s structure allows consolidated margining across asset classes, reducing collateral requirements when positions offset. Virtu Financial executive Scotte Moegling cited efficiency gains from 24/7 cross-margining. In a hypothetical $100 million portfolio comprising $60 million in equity swaps at 12 percent margin and $40 million in energy swaps at 15 percent margin, an assumed 25 percent offset would cut collateral needs from $13.2 million to $9.9 million. If an institution posts $15 million of RLUSD at a 5 percent haircut, it retains $4.3 million in headroom. However, a 6 percent decline in equities, 7 percent decline in energy, and RLUSD trading at $0.99 would create a $2.2 million shortfall.
A prime broker’s margin methodology determines when collateral calls arrive and how quickly institutions can adjust positions. The Bank for International Settlements’ March 2026 summary on margin liquidity identified leverage, concentration, interconnectedness and rapid collateral calls as sources of systemic vulnerability, drawing lessons from the Archegos Capital collapse in 2021 and the United Kingdom’s pension fund stress in September 2022. Regulators working on harmonized rules now face the added complexity of venues that operate without traditional market closures.
Regulatory framework for 24/7 derivatives still incomplete
The CFTC issued guidance on 24/7 trading in May 2026, and the SEC and CFTC jointly requested comment in June on portfolio-margin harmonization across securities, futures and swaps.
Ripple’s announcement describes the product structure but leaves material details undisclosed: position sizes, Virtu’s volumes, collateral haircuts, margin schedules and default protections remain unspecified. Each client position can be hedged on Hyperliquid, in another market, or internally, creating multiple pathways for volume to reach Ripple Prime’s books. Standard Custody and Trust Company, a New York-regulated trust company, issues RLUSD, and Ripple’s October 8 dashboard reports $2.6 billion in reserves against over $2.4 billion in circulation, representing 105.8 percent coverage on issuer-reported balances.
Ripple’s general risk disclosures cover collateral calls, basis risk, liquidity constraints, counterparty and insolvency exposure, operational failures and stablecoin depegging.
The BlockWest read. Ripple Prime’s structure succeeds only if weekend price discovery on Hyperliquid holds and margin haircuts remain stable. The bigger question is leverage migration: if institutions can now fund perpetual contracts through a regulated prime broker using RLUSD collateral, volume that would have stayed in traditional derivatives venues could shift to blockchain-settled markets. XRP’s role remains strategic but uncommitted; the token sits outside both collateral and settlement mechanics, leaving Ripple’s path to capture stablecoin collateral demand still unquantified.
The FSB’s December 2024 liquidity guidance calls for stress testing, diversified collateral, and active counterparty engagement, but leaves each firm to determine how far those principles extend into 24/7 venues operating under different margin rules. The SEC and CFTC’s June consultation on portfolio-margin harmonization will signal whether U.S. regulators plan to impose uniform haircuts and margin methodologies across swaps, futures and securities, or whether Ripple Prime’s BVI entity can operate under lighter scrutiny if it serves only non-U.S. clients.
BlockWest is a news publication. Nothing here is investment advice. Read our disclaimer and editorial policy.