
Bitcoin selling pressure hits lowest level in a month while long-term investors reduce profit taking activity
Bitcoin’s on-chain sell pressure has declined sharply as long-term holders pull back from profit-taking, reducing one key metric of potential selling force to its lowest level in a month. However, a large cache of older coins sitting at prices above current market levels remains dormant supply that could still weigh on any sustained rally.
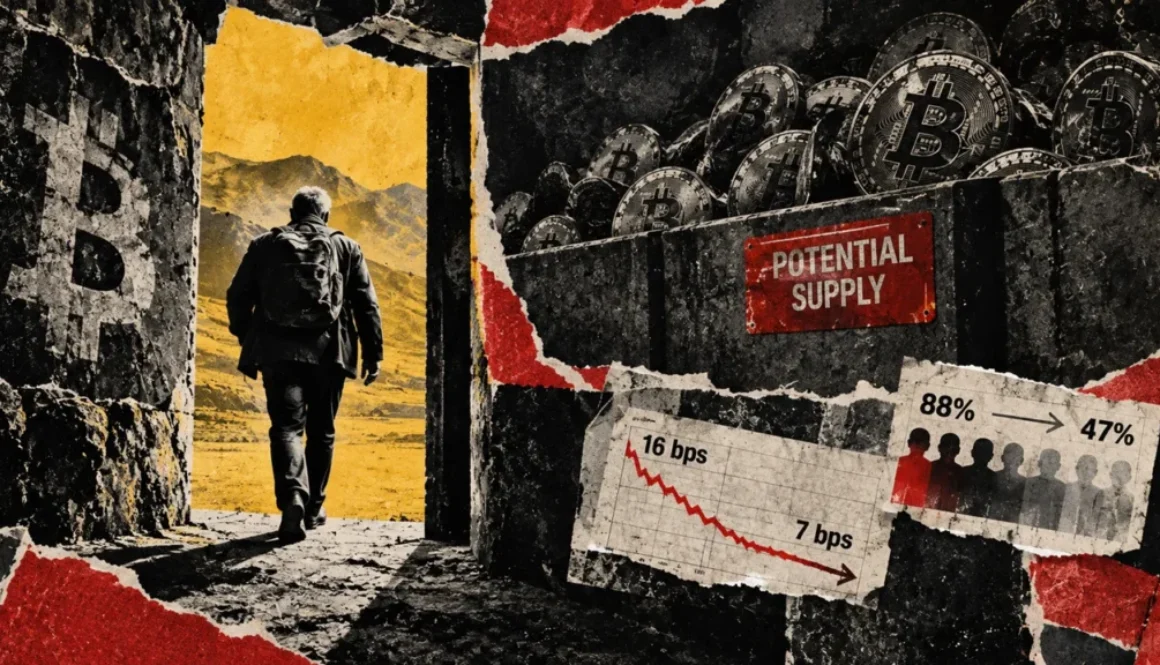
- Glassnode’s Sell-Side Risk Ratio fell to 7 basis points per day, down from 16 basis points at August’s peak, as of September 7.
- Long-term holders accounted for 47% of realized profit in early September, compared with 88% at August’s peak, showing reduced profit-taking by older holders.
- Approximately 1.07 million BTC acquired between $83,000 and $86,000 remains held almost entirely by long-term holders with minimal movement over 30 days.
- 7 bps/day Sell-Side Risk Ratio as of September 7, down from August peak
- 47% Share of realized profit from long-term holders in early September
- 1.07M BTC Held between $83,000 and $86,000 price levels by long-term holders
- 88% Long-term holders’ share of realized profit at August’s peak
Bitcoin’s on-chain selling pressure has retreated significantly from summer highs, with analytics firm Glassnode reporting that its Sell-Side Risk Ratio fell to 7 basis points per day on a seven-day average through September 7, down more than half from the 16 basis points recorded at August’s peak. The metric, which divides total on-chain profits and losses by realized capitalization, serves as a barometer for potential selling force relative to the total capital base. The decline suggests that holders are realizing fewer profits and losses in proportion to Bitcoin’s market value, easing one form of downward pressure on price.
Understanding these metrics requires context about how on-chain analysis informs market behavior. The Sell-Side Risk Ratio is particularly useful during periods of volatility because it isolates the proportion of transactions that carry profit or loss motivation. When this ratio falls, it typically signals that the market has transitioned from a phase of aggressive profit-taking to one of consolidation. This shift can reduce the immediate supply overhang and provide relief to price action if demand remains steady.
Long-Term Holders Retreat From Profit-Taking
Long-term holders, who typically hold Bitcoin for extended periods and are presumed to have stronger conviction, have significantly reduced their share of market profit-taking. Their contribution to realized profit fell to 47% in early September from 88% at August’s peak, indicating a marked pullback in how much of the market’s realized gains came from older holders during the recent period. This shift does not measure their total share of all Bitcoin sales, only the portion of profits flowing from long-term positions.
Notably, long-term holders also took less profit in raw terms. Glassnode separately measured the realized-profit spike on September 3, which came in at less than half the magnitude of August’s spike, again reflecting quieter realization activity across the holder base. Together, these metrics point to a market where both the intensity and composition of profit-taking have shifted, with older holders stepping back from active realizations.
This behavioral change is significant because long-term holders are often viewed as a stabilizing force in Bitcoin markets. When they maintain positions despite the opportunity to cash out profits, it can signal confidence in longer-term prospects. Conversely, their aggressive profit-taking during August suggested caution or at least a desire to lock in gains after a rally. The September reversal may indicate renewed patience among this cohort of investors.
Dormant Supply Near Key Price Levels Remains an Overhang
Despite the pullback in profit-taking, a substantial cache of older Bitcoin remains poised as potential overhead supply. Glassnode identified approximately 1.07 million BTC acquired between $83,000 and $86,000, almost entirely held by long-term holders, with minimal change in holdings over the previous 30 days. These coins sit above current market prices, meaning holders are underwater or holding near break-even, reducing the immediate incentive to sell.
The distinction between holdings and recent realizations is material. Treating that entire 1.07 million BTC block as immediate selling pressure would overstate the actual near-term risk, since the data on reduced profit-taking shows that holders are not aggressively liquidating even when they hold profits. However, a sustained advance through and above these price levels would still require buyers to absorb whatever supply does eventually come to market from these holders.
The size of this dormant supply is noteworthy in the context of Bitcoin’s overall circulation. At present market valuations, 1.07 million BTC represents a meaningful percentage of all Bitcoin, making it a factor that institutional traders and market participants monitor closely. If prices rise significantly above this range, the potential unlocking of this supply could act as a natural resistance point.
Exchange Flow Dynamics Signal Continued Selling Pressure at Market Level
While on-chain realization metrics have eased, exchange-level trading data reveal a different picture. Reports of negative exchange spot flow on September 8 indicated that aggressive selling still outweighed aggressive buying on centralized venues. The Spot Cumulative Volume Delta, which tracks the balance of executed trades, remained negative despite improving, meaning sell-side pressure persisted in the order flow despite the easing of on-chain profit realization.
This divergence between on-chain and exchange metrics highlights the complexity of Bitcoin market structure. On-chain metrics capture all transactions occurring on the Bitcoin network, while exchange data reflects only the subset of activity occurring on centralized trading platforms. Both provide valuable but incomplete pictures of market dynamics. The fact that exchange selling pressure persisted even as on-chain profit-taking declined suggests that different cohorts of traders were active at different stages.
The divergence between easing on-chain profit-taking and continued negative exchange flow underscores that Bitcoin’s near-term price action will hinge on whether buyers can sustain demand and absorb supply as it reaches the market, rather than on the total amount of dormant capital held above current prices.